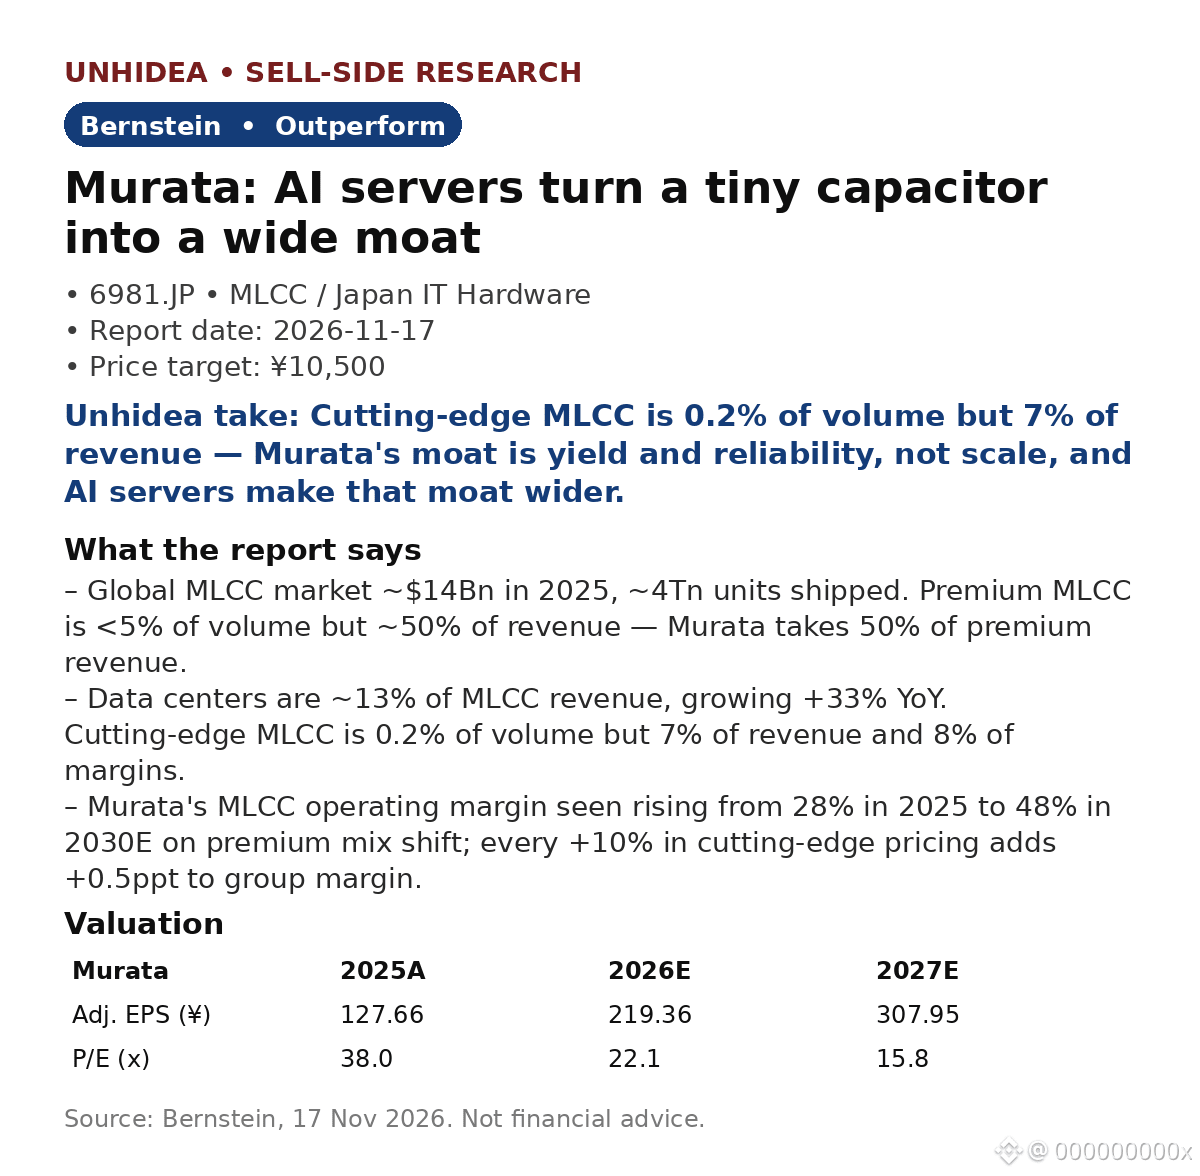
Murata (6981.JP): Bernstein sees ~116% upside as AI servers turn a tiny capacitor into a wide moat — target ¥10,500 vs ¥4,855 close on 16 Nov
- Global MLCC market ~$14Bn in 2025, ~4Tn units. Premium is <5% of volume but ~50% of revenue — Murata takes 50% of premium revenue.
- Data centers ~13% of MLCC revenue, +33% YoY. Cutting-edge MLCC: 0.2% of volume, 7% of revenue, 8% of margins.
- AI-server MLCCs must run 24/7 for 10+ years, near-zero failure — a bar most rivals can't clear at scale. Murata R&D is 9% of revenue vs 4–7% for peers.
- Mix shift, not price hikes: Murata MLCC margin seen rising 28% (2025) to 48% (2030E). Every +10% in cutting-edge pricing adds +0.5ppt to group margin.
- Bernstein reiterates Outperform, TP ¥10,500. Adj. EPS ¥219.36 in 2026E (+72% YoY), ¥307.95 in 2027E; 22.1x / 15.8x P/E.
Unhidea take: the AI trade has been about GPUs and power — but every AI rack needs thousands of MLCCs that cannot fail. Murata's edge is the boring, certified, yield-driven kind that compounds quietly.
Unhidea take: Bernstein gives China 5–10 years to catch up on premium MLCC. The AI buildout is happening now, and the qualified supplier list is effectively two names long — that window is the investment case.
Risks: Murata is reluctant to raise prices, so mix shift must deliver; an AI server slowdown or weak smartphone/auto demand would hit volumes.
Source: Bernstein, 17 Nov 2026. Not financial advice.
- Global MLCC market ~$14Bn in 2025, ~4Tn units. Premium is <5% of volume but ~50% of revenue — Murata takes 50% of premium revenue.
- Data centers ~13% of MLCC revenue, +33% YoY. Cutting-edge MLCC: 0.2% of volume, 7% of revenue, 8% of margins.
- AI-server MLCCs must run 24/7 for 10+ years, near-zero failure — a bar most rivals can't clear at scale. Murata R&D is 9% of revenue vs 4–7% for peers.
- Mix shift, not price hikes: Murata MLCC margin seen rising 28% (2025) to 48% (2030E). Every +10% in cutting-edge pricing adds +0.5ppt to group margin.
- Bernstein reiterates Outperform, TP ¥10,500. Adj. EPS ¥219.36 in 2026E (+72% YoY), ¥307.95 in 2027E; 22.1x / 15.8x P/E.
Unhidea take: the AI trade has been about GPUs and power — but every AI rack needs thousands of MLCCs that cannot fail. Murata's edge is the boring, certified, yield-driven kind that compounds quietly.
Unhidea take: Bernstein gives China 5–10 years to catch up on premium MLCC. The AI buildout is happening now, and the qualified supplier list is effectively two names long — that window is the investment case.
Risks: Murata is reluctant to raise prices, so mix shift must deliver; an AI server slowdown or weak smartphone/auto demand would hit volumes.
Source: Bernstein, 17 Nov 2026. Not financial advice.