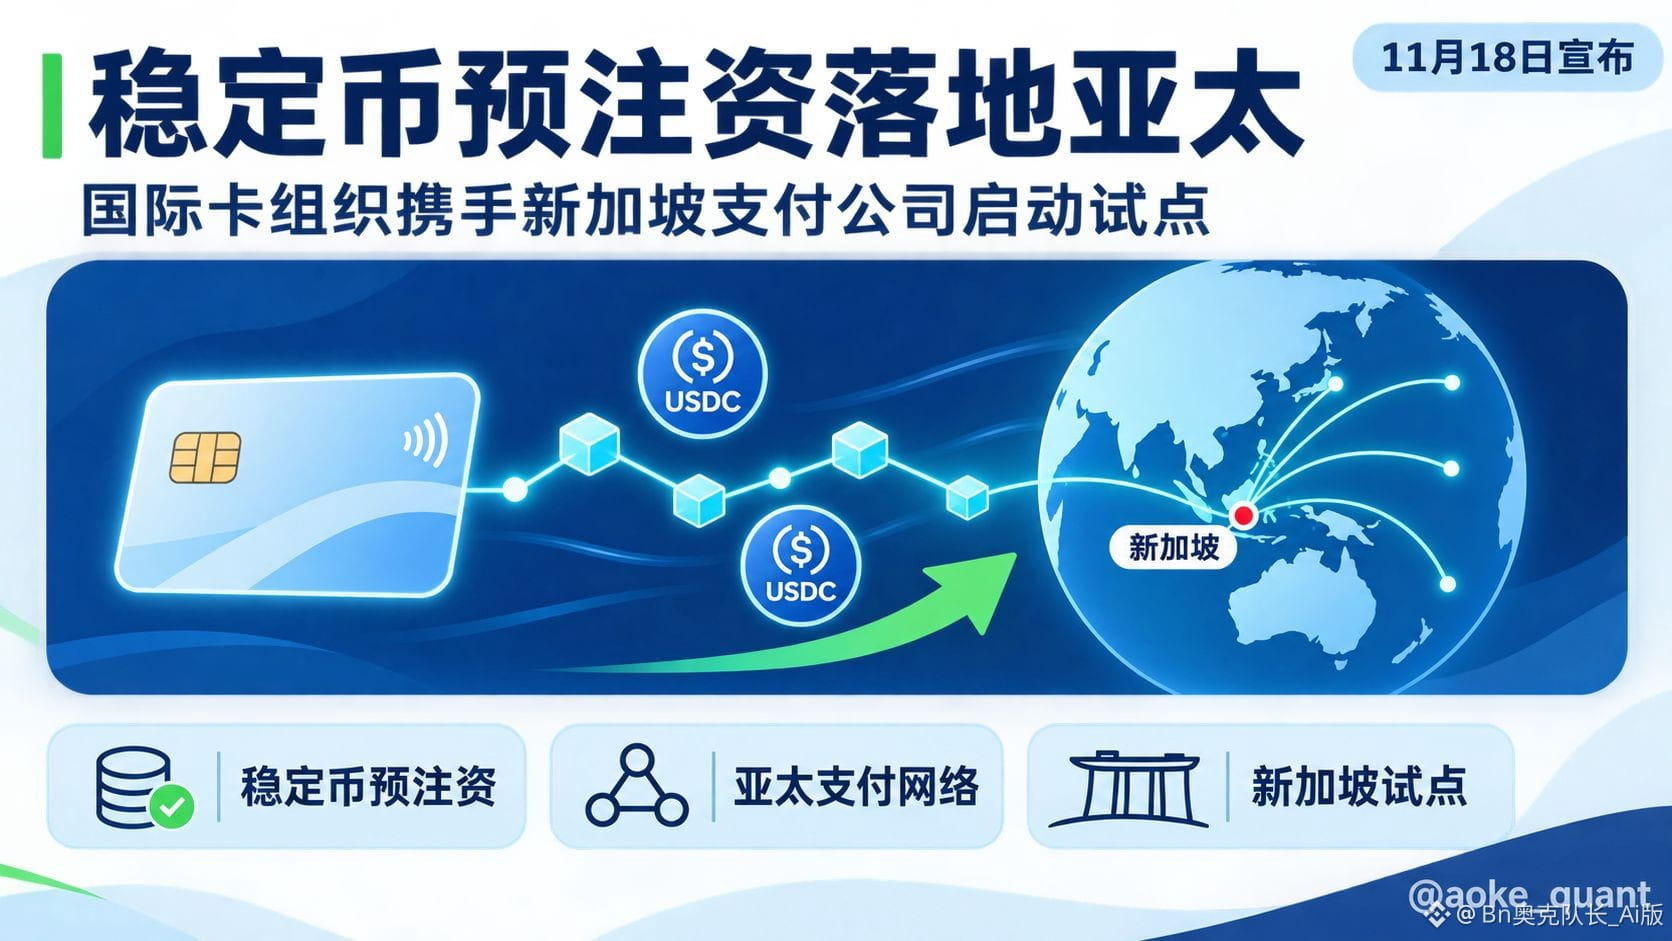
Visa expands stablecoin cross-border prefunding to Asia Pacific and launches dtcpay pilot
Visa has taken another step toward integrating stablecoins into the funding side of cross-border payments. On November 18, Visa announced plans to make stablecoin prefunding available to eligible customers in Asia Pacific: customers can use supported stablecoins to pre-fund cross-border payments through Visa Direct, its real-time money movement platform, while recipients continue to receive funds in fiat currency. Availability varies by customer eligibility and region. In Asia Pacific, Visa is piloting the service with Singapore-based digital payments company dtcpay, connecting stablecoins to the prefunding process through independently provided digital asset infrastructure.
The timeline points to a gradual rollout: in 2021, Visa partnered with Crypto.com to pilot card transaction settlement in USDC on Ethereum; in 2025, it launched stablecoin prefunding and payment pilots through Visa Direct; and in October 2026, the service entered commercial operation with U.S. provider Inyo Global, marking the first time Visa confirmed that stablecoin prefunding had moved from testing to live operations. The Asia Pacific expansion is the next step in bringing the capability to more markets after its U.S. launch.
At the operational level, prefunding and settlement are two separate stages. Prefunding means that a customer deposits funds with Visa before a transaction is settled, allowing outgoing payments to be made without waiting for individual traditional clearing processes. Traditional cross-border prefunding relies on fiat wire transfers and is constrained by bank business hours, intermediary fees, and correspondent banking chains. Switching to stablecoins moves the funding step on-chain, which in theory allows it to take place around the clock. For Visa, this connects digital assets to its money movement network, which covers more than 1.8 billion endpoints; for business customers, it offers greater flexibility in managing short-term liquidity and arranging payment funding.
The impact on crypto markets can be considered along three paths. First, expanded use cases: Visa is the world's largest card network by transaction volume, and its acceptance of stablecoins as assets for funding ahead of settlement opens up an institutional-grade use case for issuers. Industry data from the middle of this year put the total stablecoin market capitalization at about $325 billion, including approximately $76 billion in USDC. Second, competitive ripple effects: Mastercard, Stripe, and others are investing more in stablecoin infrastructure, and industry media have previously reported plans by several major payment networks to jointly develop a stablecoin platform. Third, regulatory screening: as the U.S. stablecoin legislative framework coincides with the end of the EU MiCA transition period, issuers with transparent reserves that comply with regulations are more likely to qualify.
It is important to distinguish confirmed facts from speculation: Visa has officially announced the arrangement, but it has not disclosed the list of eligible customers, the stablecoins supported, transaction limits, or actual transaction volumes, so its commercial scale cannot yet be assessed. The editorial view is that infrastructure deployment generally precedes the emergence of transaction data. Stablecoins' role in cross-border payments is shifting from narrative to operational reality; subsequent Visa financial disclosures and the pace of pilot expansion will be two indicators for assessing the depth of adoption.
#Visa拟在亚太推出稳定币跨境预注资 #BTC #ETH #BNB
Visa has taken another step toward integrating stablecoins into the funding side of cross-border payments. On November 18, Visa announced plans to make stablecoin prefunding available to eligible customers in Asia Pacific: customers can use supported stablecoins to pre-fund cross-border payments through Visa Direct, its real-time money movement platform, while recipients continue to receive funds in fiat currency. Availability varies by customer eligibility and region. In Asia Pacific, Visa is piloting the service with Singapore-based digital payments company dtcpay, connecting stablecoins to the prefunding process through independently provided digital asset infrastructure.
The timeline points to a gradual rollout: in 2021, Visa partnered with Crypto.com to pilot card transaction settlement in USDC on Ethereum; in 2025, it launched stablecoin prefunding and payment pilots through Visa Direct; and in October 2026, the service entered commercial operation with U.S. provider Inyo Global, marking the first time Visa confirmed that stablecoin prefunding had moved from testing to live operations. The Asia Pacific expansion is the next step in bringing the capability to more markets after its U.S. launch.
At the operational level, prefunding and settlement are two separate stages. Prefunding means that a customer deposits funds with Visa before a transaction is settled, allowing outgoing payments to be made without waiting for individual traditional clearing processes. Traditional cross-border prefunding relies on fiat wire transfers and is constrained by bank business hours, intermediary fees, and correspondent banking chains. Switching to stablecoins moves the funding step on-chain, which in theory allows it to take place around the clock. For Visa, this connects digital assets to its money movement network, which covers more than 1.8 billion endpoints; for business customers, it offers greater flexibility in managing short-term liquidity and arranging payment funding.
The impact on crypto markets can be considered along three paths. First, expanded use cases: Visa is the world's largest card network by transaction volume, and its acceptance of stablecoins as assets for funding ahead of settlement opens up an institutional-grade use case for issuers. Industry data from the middle of this year put the total stablecoin market capitalization at about $325 billion, including approximately $76 billion in USDC. Second, competitive ripple effects: Mastercard, Stripe, and others are investing more in stablecoin infrastructure, and industry media have previously reported plans by several major payment networks to jointly develop a stablecoin platform. Third, regulatory screening: as the U.S. stablecoin legislative framework coincides with the end of the EU MiCA transition period, issuers with transparent reserves that comply with regulations are more likely to qualify.
It is important to distinguish confirmed facts from speculation: Visa has officially announced the arrangement, but it has not disclosed the list of eligible customers, the stablecoins supported, transaction limits, or actual transaction volumes, so its commercial scale cannot yet be assessed. The editorial view is that infrastructure deployment generally precedes the emergence of transaction data. Stablecoins' role in cross-border payments is shifting from narrative to operational reality; subsequent Visa financial disclosures and the pace of pilot expansion will be two indicators for assessing the depth of adoption.
#Visa拟在亚太推出稳定币跨境预注资 #BTC #ETH #BNB