Nvidia won again. The question is no longer whether it can sell, but how much longer it can keep growing at this pace. 🧐
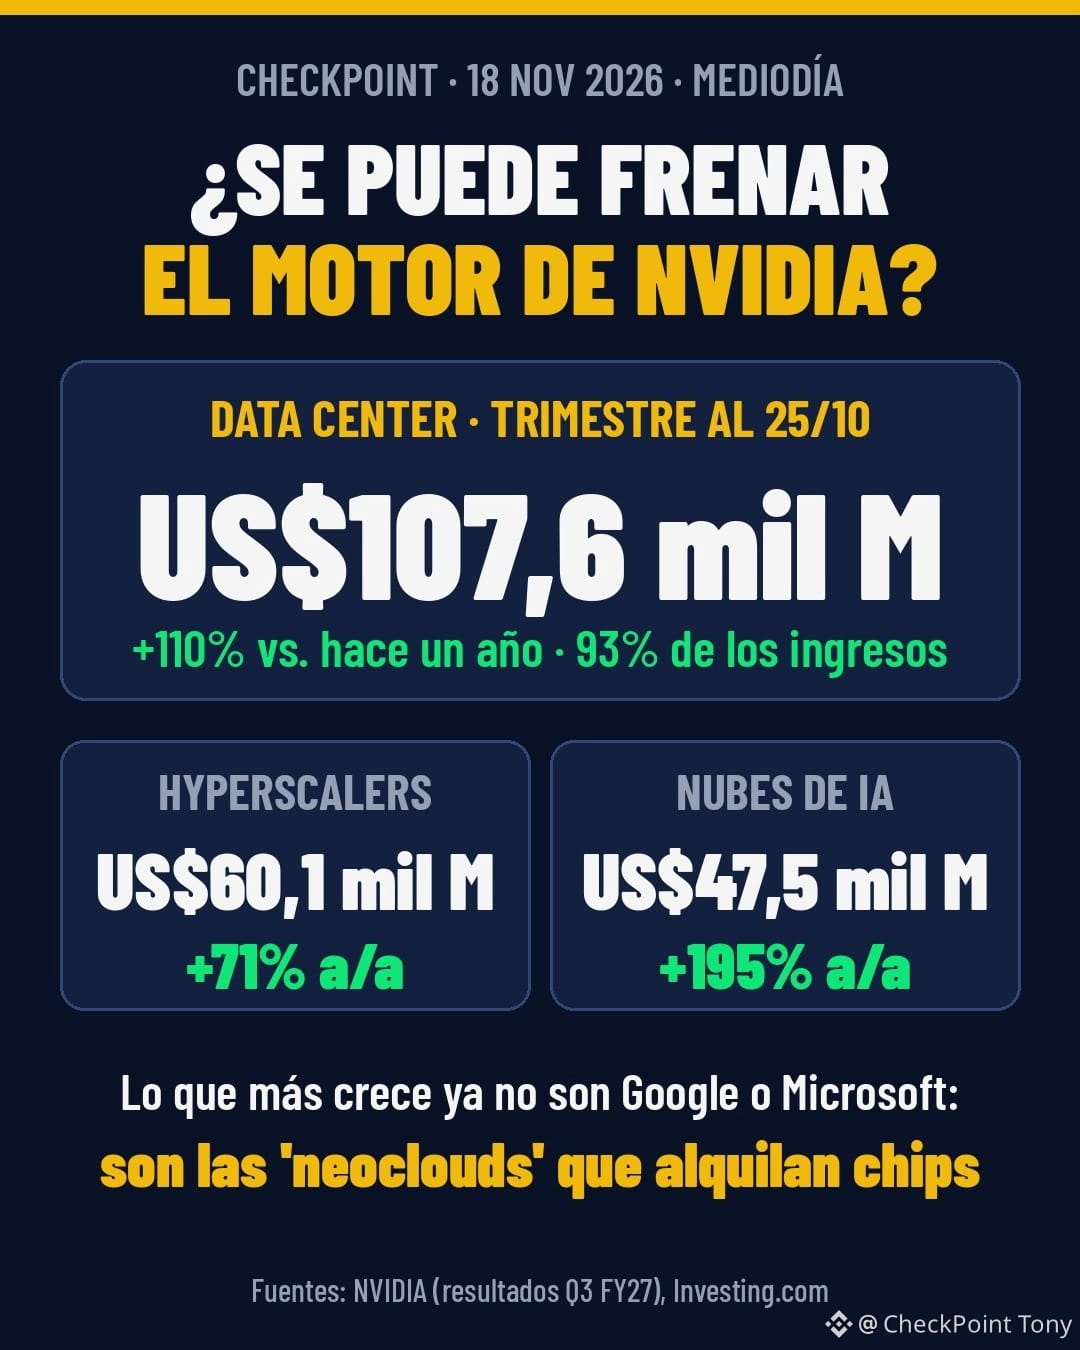
Its data center business brought in US$107.6 billion in the quarter ended 10/25: up 110% year over year and nearly 93% of the company’s total sales.
The most interesting part is inside that number:
🏢 Hyperscalers (the cloud giants): US$60.1 billion, +71%
☁️ “AI clouds” (the neoclouds that rent out chips): US$47.5 billion, +195%
In other words, growth is shifting toward newer, smaller customers. That’s fuel… and also a risk.
🟢 What’s driving growth:
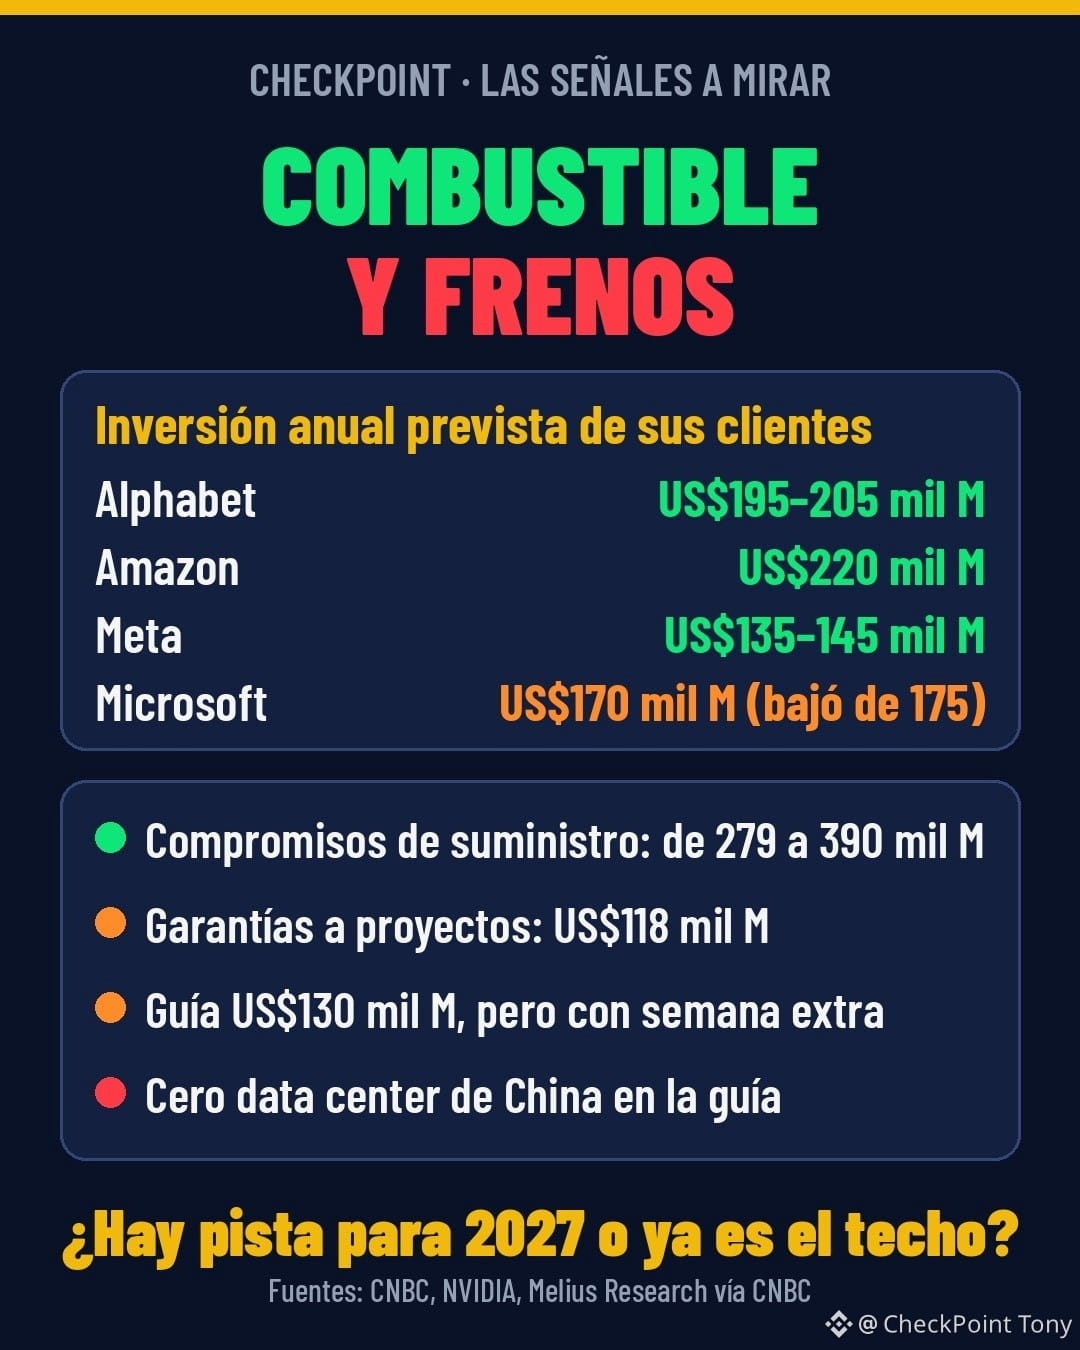
• Supply commitments rose from US$279 billion to US$390 billion in three months (CNBC).
• Next quarter’s guidance: US$130 billion (±3%), versus the US$125.1 billion the market expected (LSEG).
• It raised its fiscal 2028 growth forecast from 70% to 75%.
🔴 What could slow it down:
• Part of the jump in guidance comes from an extra week in the quarter: Melius estimates that accounts for US$9–10 billion.
• The guidance excludes data center sales to China.
• Nvidia has US$118 billion in guarantees for projects, US$105 billion of which is for an OpenAI campus. CFO and interim CEO Colette Kress promised to be “disciplined and selective.”
• Its biggest customers pulled back a little: Microsoft lowered its expected annual investment from US$175 billion to US$170 billion, while Alphabet (195–205), Amazon (220), and Meta (135–145) held steady.
The market celebrated with a gain of more than 5% after hours, but Jensen Huang’s succession remains unresolved, bringing volatility.
My take: as long as big tech keeps writing checks for hundreds of billions, the engine has fuel. The day that capex curve flattens, we’ll see it first among the neoclouds.
Do you think Nvidia’s data center business can keep doubling, or are we already seeing the ceiling? 👇
Follow Checkpoint to understand the market without the jargon.
Sources: NVIDIA, CNBC, LSEG, Investing.com.
This is not financial advice.
#CanNvidia’sDataCenterGrowthContinue? #Nvidia #AI
Its data center business brought in US$107.6 billion in the quarter ended 10/25: up 110% year over year and nearly 93% of the company’s total sales.
The most interesting part is inside that number:
🏢 Hyperscalers (the cloud giants): US$60.1 billion, +71%
☁️ “AI clouds” (the neoclouds that rent out chips): US$47.5 billion, +195%
In other words, growth is shifting toward newer, smaller customers. That’s fuel… and also a risk.
🟢 What’s driving growth:
• Supply commitments rose from US$279 billion to US$390 billion in three months (CNBC).
• Next quarter’s guidance: US$130 billion (±3%), versus the US$125.1 billion the market expected (LSEG).
• It raised its fiscal 2028 growth forecast from 70% to 75%.
🔴 What could slow it down:
• Part of the jump in guidance comes from an extra week in the quarter: Melius estimates that accounts for US$9–10 billion.
• The guidance excludes data center sales to China.
• Nvidia has US$118 billion in guarantees for projects, US$105 billion of which is for an OpenAI campus. CFO and interim CEO Colette Kress promised to be “disciplined and selective.”
• Its biggest customers pulled back a little: Microsoft lowered its expected annual investment from US$175 billion to US$170 billion, while Alphabet (195–205), Amazon (220), and Meta (135–145) held steady.
The market celebrated with a gain of more than 5% after hours, but Jensen Huang’s succession remains unresolved, bringing volatility.
My take: as long as big tech keeps writing checks for hundreds of billions, the engine has fuel. The day that capex curve flattens, we’ll see it first among the neoclouds.
Do you think Nvidia’s data center business can keep doubling, or are we already seeing the ceiling? 👇
Follow Checkpoint to understand the market without the jargon.
Sources: NVIDIA, CNBC, LSEG, Investing.com.
This is not financial advice.
#CanNvidia’sDataCenterGrowthContinue? #Nvidia #AI