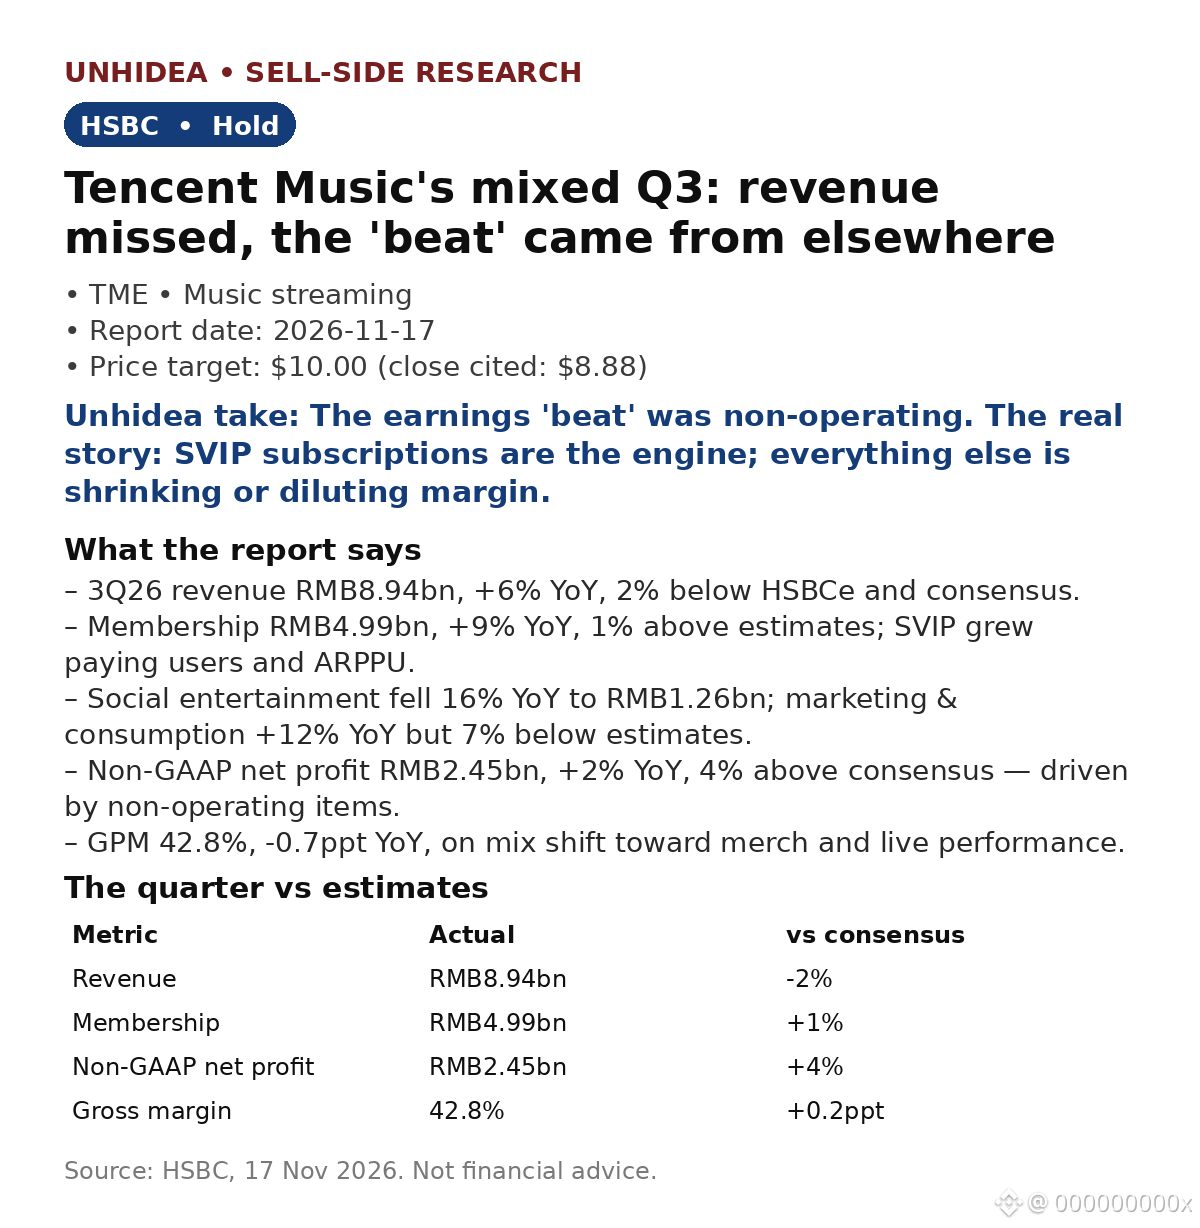
$TME: 3Q revenue missed — RMB8.94B, +6% YoY, 2% below Street — but HSBC keeps Hold, $10.00 PT
- Membership did the work: RMB4.99B, +9% YoY, 1% above estimates, with SVIP growing paying users and ARPPU.
- Social entertainment fell 16% YoY to RMB1.26B; marketing & consumption grew 12% but missed by 7%.
- Non-GAAP net profit RMB2.45B, +2% YoY, 4% above consensus — but the beat came from non-operating items, not the business.
- GPM 42.8%, -0.7ppt YoY, as merch and live performance took a bigger mix share.
- Buyback: 34.7m ADSs for ~$300M in Q3 — 2.1% of market cap in one quarter.
Valuation: $10.00 PT is ~13% above the $8.88 close cited (16 Nov).
Unhidea take: a "beat" built on non-operating items is not an operating beat — strip it out and the quarter was a miss, with non-GAAP operating profit flat YoY.
Unhidea take: TME is quietly becoming a subscription company — SVIP is the durable engine; judge it on membership ARPPU, not blended revenue.
Risks: Ximalaya integration costs, SE decline, margin mix pressure.
Source: HSBC, 17 Nov 2026. Not financial advice.
- Membership did the work: RMB4.99B, +9% YoY, 1% above estimates, with SVIP growing paying users and ARPPU.
- Social entertainment fell 16% YoY to RMB1.26B; marketing & consumption grew 12% but missed by 7%.
- Non-GAAP net profit RMB2.45B, +2% YoY, 4% above consensus — but the beat came from non-operating items, not the business.
- GPM 42.8%, -0.7ppt YoY, as merch and live performance took a bigger mix share.
- Buyback: 34.7m ADSs for ~$300M in Q3 — 2.1% of market cap in one quarter.
Valuation: $10.00 PT is ~13% above the $8.88 close cited (16 Nov).
Unhidea take: a "beat" built on non-operating items is not an operating beat — strip it out and the quarter was a miss, with non-GAAP operating profit flat YoY.
Unhidea take: TME is quietly becoming a subscription company — SVIP is the durable engine; judge it on membership ARPPU, not blended revenue.
Risks: Ximalaya integration costs, SE decline, margin mix pressure.
Source: HSBC, 17 Nov 2026. Not financial advice.