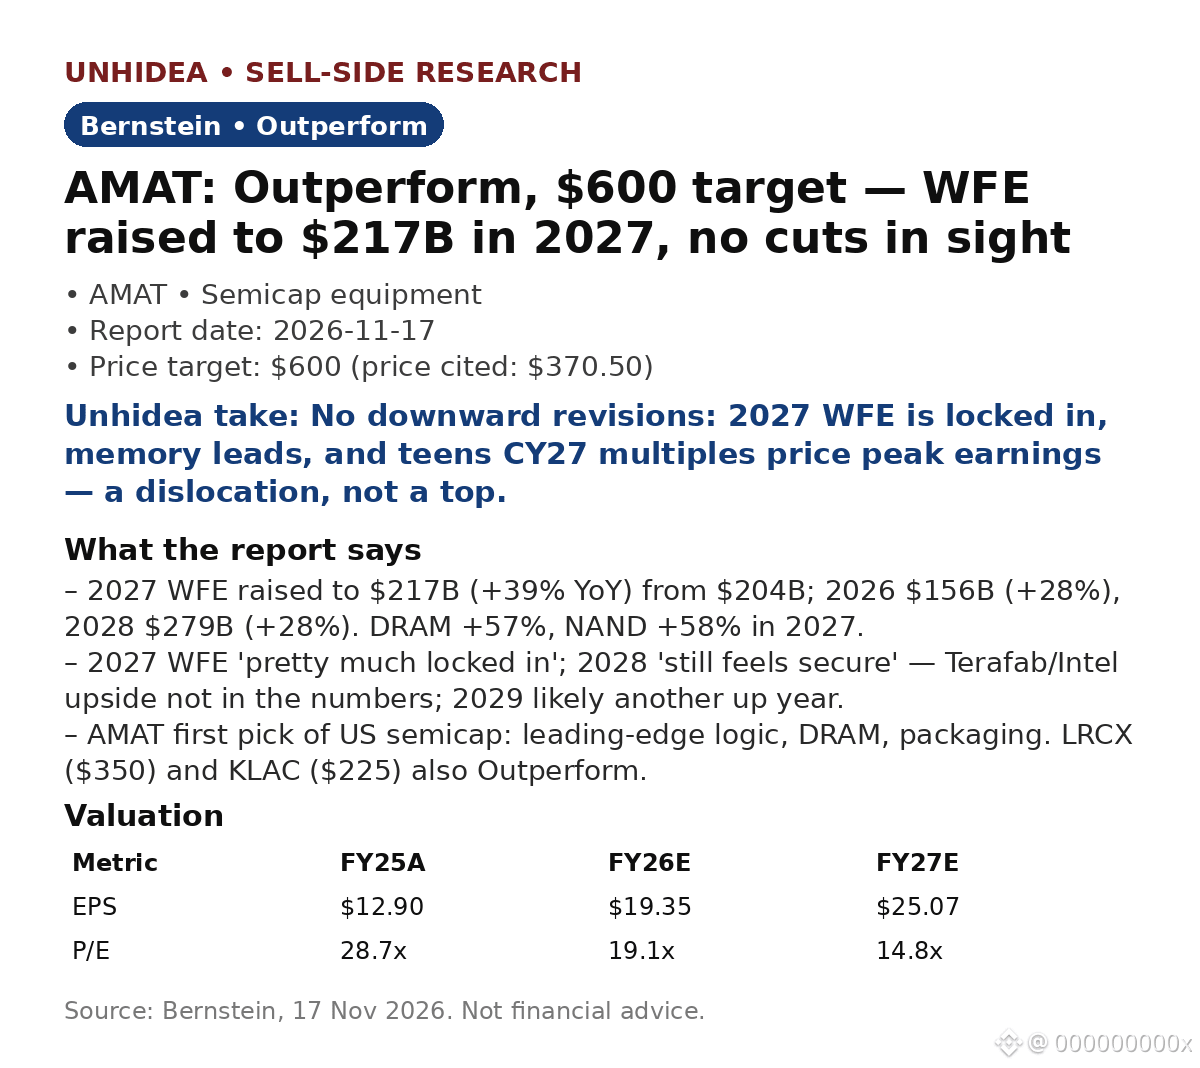
$AMAT: Bernstein raises 2027 WFE to $217B (+39% YoY) — no cuts in sight. AMAT Outperform, $600 target, ~62% above the $370.50 price cited in the report.
WFE raised across the board: 2026 $156B (+28% YoY) from $148B; 2027 $217B (+39%) from $204B; 2028 $279B (+28%) from $259B. DRAM +57%, NAND +58% in 2027; logic/foundry +27%.
2027 WFE is "pretty much locked in", 2028 "still feels secure" — Terafab/Intel upside not in the numbers; 2029 likely another up year.
AMAT is Bernstein's first pick in US semicap — leading-edge logic, DRAM and packaging, "a bit cheaper". EPS $19.35 FY26E → $25.07 FY27E (+30% YoY), 14.8x FY27E P/E. LRCX ($350) and KLAC ($225) also Outperform.
Stocks trade at teens CY27 multiples, pricing peak(ish) earnings — Bernstein calls it a dislocation with upside "when the dust settles".
Unhidea take: memory is now the marginal WFE driver — DRAM/NAND growing ~2x logic's rate in 2027 — so HBM and memory pricing set the pace of revisions.
Unhidea take: China is the swing factor — WFE $57B → $108B by 2028 — so export-control headlines matter more than order books near term.
Risks: foundry push-outs; memory price correction; China export controls; AI capex slowing. Source: Bernstein, 17 Nov 2026. Not financial advice.
WFE raised across the board: 2026 $156B (+28% YoY) from $148B; 2027 $217B (+39%) from $204B; 2028 $279B (+28%) from $259B. DRAM +57%, NAND +58% in 2027; logic/foundry +27%.
2027 WFE is "pretty much locked in", 2028 "still feels secure" — Terafab/Intel upside not in the numbers; 2029 likely another up year.
AMAT is Bernstein's first pick in US semicap — leading-edge logic, DRAM and packaging, "a bit cheaper". EPS $19.35 FY26E → $25.07 FY27E (+30% YoY), 14.8x FY27E P/E. LRCX ($350) and KLAC ($225) also Outperform.
Stocks trade at teens CY27 multiples, pricing peak(ish) earnings — Bernstein calls it a dislocation with upside "when the dust settles".
Unhidea take: memory is now the marginal WFE driver — DRAM/NAND growing ~2x logic's rate in 2027 — so HBM and memory pricing set the pace of revisions.
Unhidea take: China is the swing factor — WFE $57B → $108B by 2028 — so export-control headlines matter more than order books near term.
Risks: foundry push-outs; memory price correction; China export controls; AI capex slowing. Source: Bernstein, 17 Nov 2026. Not financial advice.