$BTC
MVRV has dropped to 1.1. Let me say this first: it’s a sign we may be near a bottom, not a signal to buy the dip.
Data just released by CryptoQuant puts MVRV at around 1.1, below 1.2.
This compares market value with on-chain cost basis. On average, holders are only up about 10%, putting us in the valuation range seen near the 2022 bear-market bottom.
This is the third time this year: once in February near $60,000, and once in June or July near $57,000. Neither time did the market immediately V-recover afterward.
Glassnode’s November 11 report lines up with this too: short-term holders’ cost basis is clustered between $62,000 and $66,000, and we’re now moving around within that range.
But don’t rush to call a bottom. Other data still looks rough: 30-day apparent demand is down 247,000 BTC, the one-year figure is down 1.21 million BTC, and spot ETFs saw net outflows of $1.07 billion last week.
Put simply: prices are cheaper, but buyers haven’t returned. MVRV measures valuation, not whether anyone is actually willing to put money in.
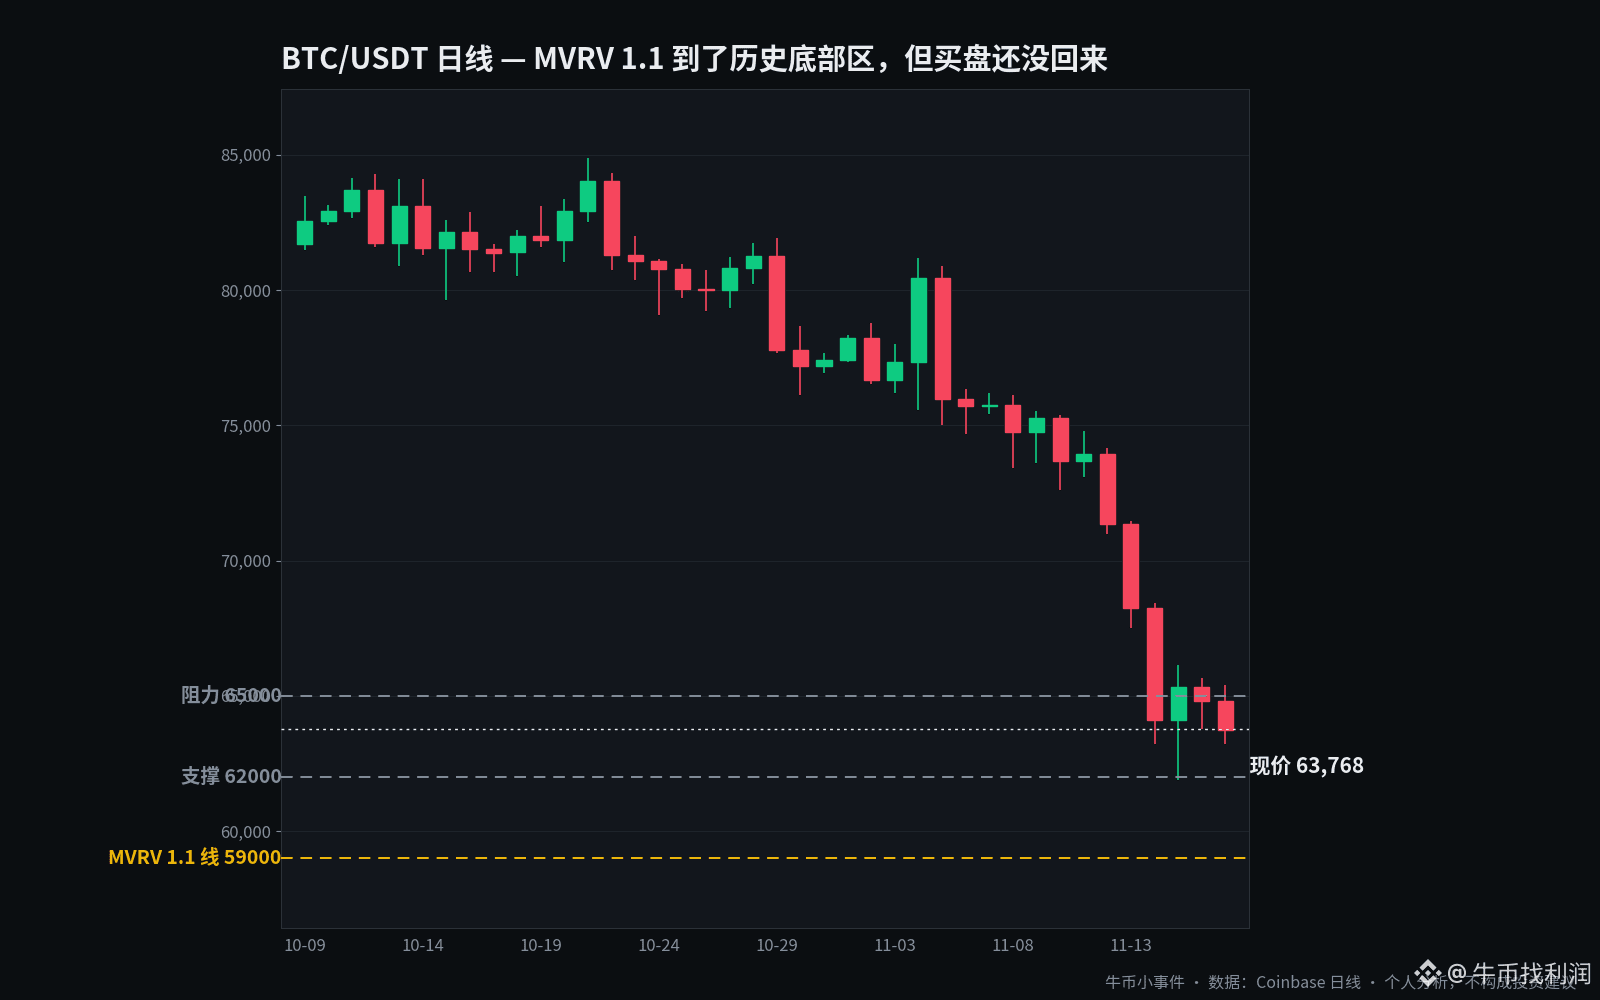
One analyst says the MVRV 1.1 level corresponds to roughly $59,000. If that level doesn’t hold, let’s not talk about a bottom just yet.
I’m still staying out and watching from the sidelines. I’ve accepted and closed out the stop-loss at $64,000 from my post overnight—no point dwelling on it.
I’m watching $62,000 below; if that breaks, then $60,000, and below that is the $59,000 MVRV level.
To the upside, I’d only consider going long after we reclaim $65,000. If we can’t get back above it, it’s off the table.
If you really want to buy the dip, wait until the price stabilizes first. Buying here isn’t buying the bottom—it’s buying the lonely middle of the mountain.
This is my personal analysis and not investment advice.
#MVRV
MVRV has dropped to 1.1. Let me say this first: it’s a sign we may be near a bottom, not a signal to buy the dip.
Data just released by CryptoQuant puts MVRV at around 1.1, below 1.2.
This compares market value with on-chain cost basis. On average, holders are only up about 10%, putting us in the valuation range seen near the 2022 bear-market bottom.
This is the third time this year: once in February near $60,000, and once in June or July near $57,000. Neither time did the market immediately V-recover afterward.
Glassnode’s November 11 report lines up with this too: short-term holders’ cost basis is clustered between $62,000 and $66,000, and we’re now moving around within that range.
But don’t rush to call a bottom. Other data still looks rough: 30-day apparent demand is down 247,000 BTC, the one-year figure is down 1.21 million BTC, and spot ETFs saw net outflows of $1.07 billion last week.
Put simply: prices are cheaper, but buyers haven’t returned. MVRV measures valuation, not whether anyone is actually willing to put money in.
One analyst says the MVRV 1.1 level corresponds to roughly $59,000. If that level doesn’t hold, let’s not talk about a bottom just yet.
I’m still staying out and watching from the sidelines. I’ve accepted and closed out the stop-loss at $64,000 from my post overnight—no point dwelling on it.
I’m watching $62,000 below; if that breaks, then $60,000, and below that is the $59,000 MVRV level.
To the upside, I’d only consider going long after we reclaim $65,000. If we can’t get back above it, it’s off the table.
If you really want to buy the dip, wait until the price stabilizes first. Buying here isn’t buying the bottom—it’s buying the lonely middle of the mountain.
This is my personal analysis and not investment advice.
#MVRV