AMM automated market makers, explained in a few sentences:
The more of a token is bought from a pool, the scarcer it becomes in the pool and the higher its quoted price, so large swaps can cause significant slippage.
AMM quotes are calculated solely from the ratio of the two tokens in the liquidity pool. When they diverge from the external market price, arbitrage trades push the quotes back toward it.
For tokens with shallow liquidity pools, check the estimated price impact before making a large one-time trade, and split it into several trades if necessary.
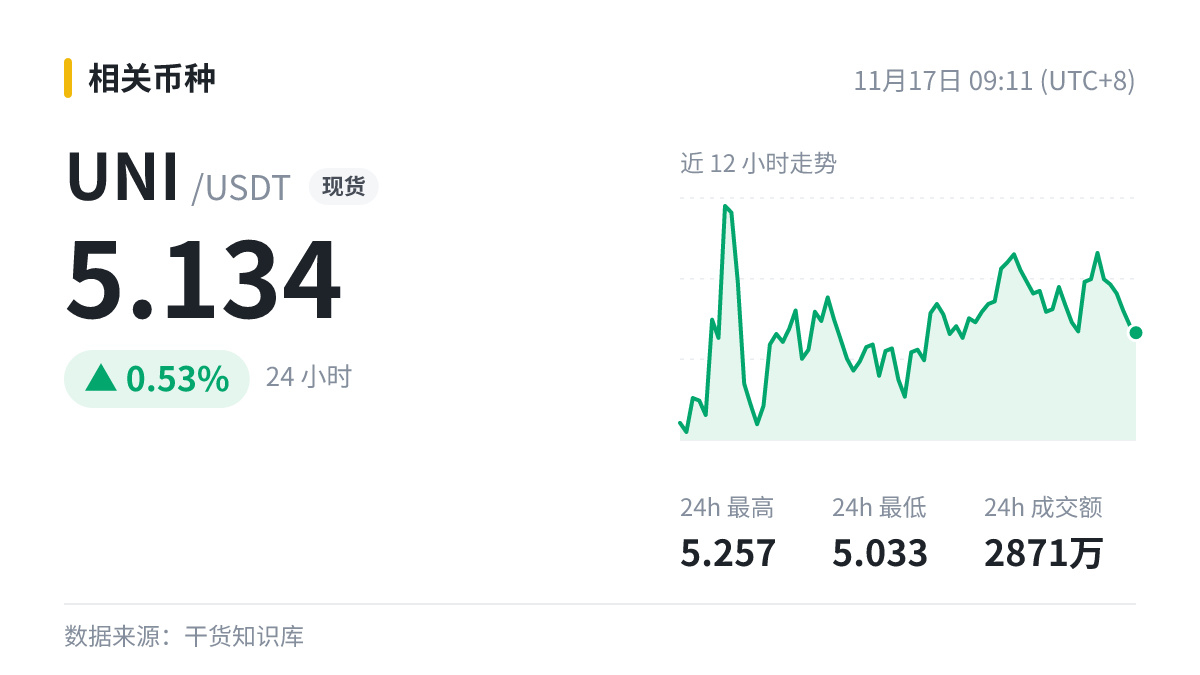
$UNI 5.134 (+0.53%)
The more of a token is bought from a pool, the scarcer it becomes in the pool and the higher its quoted price, so large swaps can cause significant slippage.
AMM quotes are calculated solely from the ratio of the two tokens in the liquidity pool. When they diverge from the external market price, arbitrage trades push the quotes back toward it.
For tokens with shallow liquidity pools, check the estimated price impact before making a large one-time trade, and split it into several trades if necessary.
$UNI 5.134 (+0.53%)