AI hardware bottlenecks are tightening, yet suppliers are getting crushed.
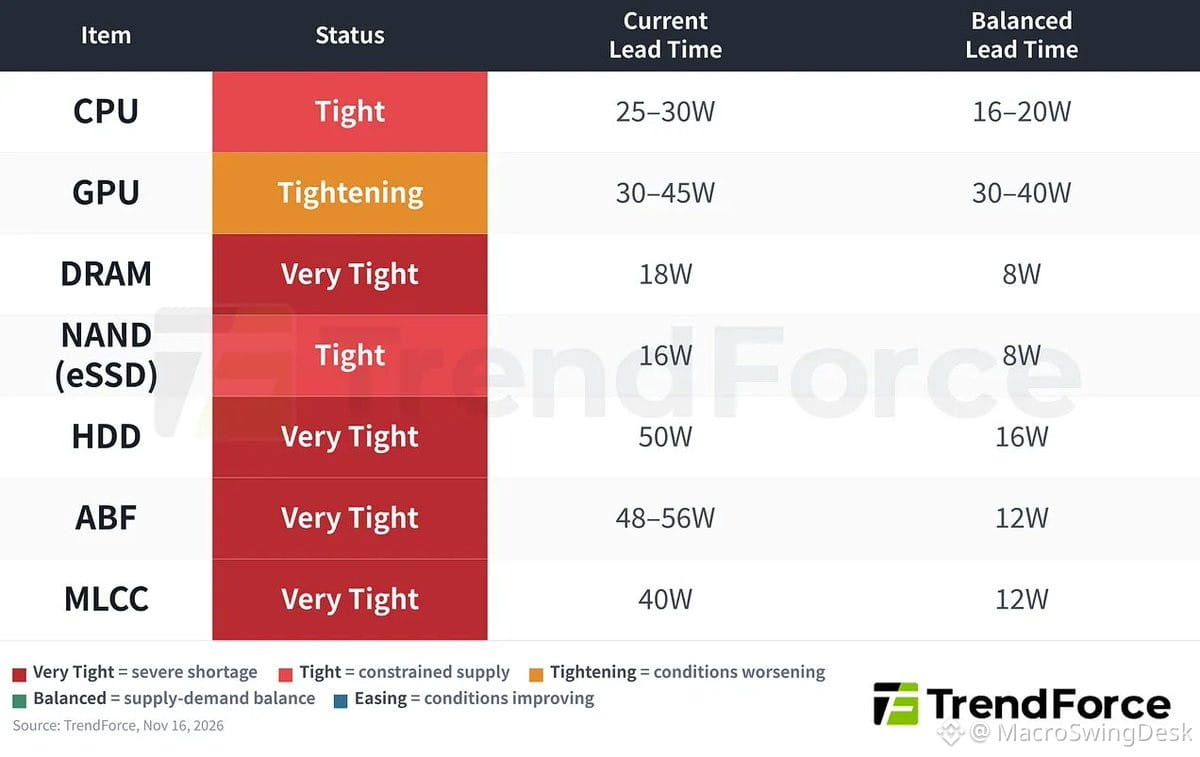
MLCC lead times now at 40 weeks per Trendforce — "very tight" supply. Content per system is exploding. $AMD's MI450 boards using 632% more of certain parts vs prior gen.
Yet Murata, Samsung Electro-Mechanics, and other suppliers? Sold off hard.
Market is pricing in broad capex cuts post-2027, but missing the nuance: demand for specific bottleneck components can still accelerate even if overall AI spending moderates. Supply constraints + rising content = pricing power.
This disconnect creates asymmetric opportunities in overlooked AI supply chain plays. Don't conflate macro capex concerns with micro component dynamics.
MLCC lead times now at 40 weeks per Trendforce — "very tight" supply. Content per system is exploding. $AMD's MI450 boards using 632% more of certain parts vs prior gen.
Yet Murata, Samsung Electro-Mechanics, and other suppliers? Sold off hard.
Market is pricing in broad capex cuts post-2027, but missing the nuance: demand for specific bottleneck components can still accelerate even if overall AI spending moderates. Supply constraints + rising content = pricing power.
This disconnect creates asymmetric opportunities in overlooked AI supply chain plays. Don't conflate macro capex concerns with micro component dynamics.