
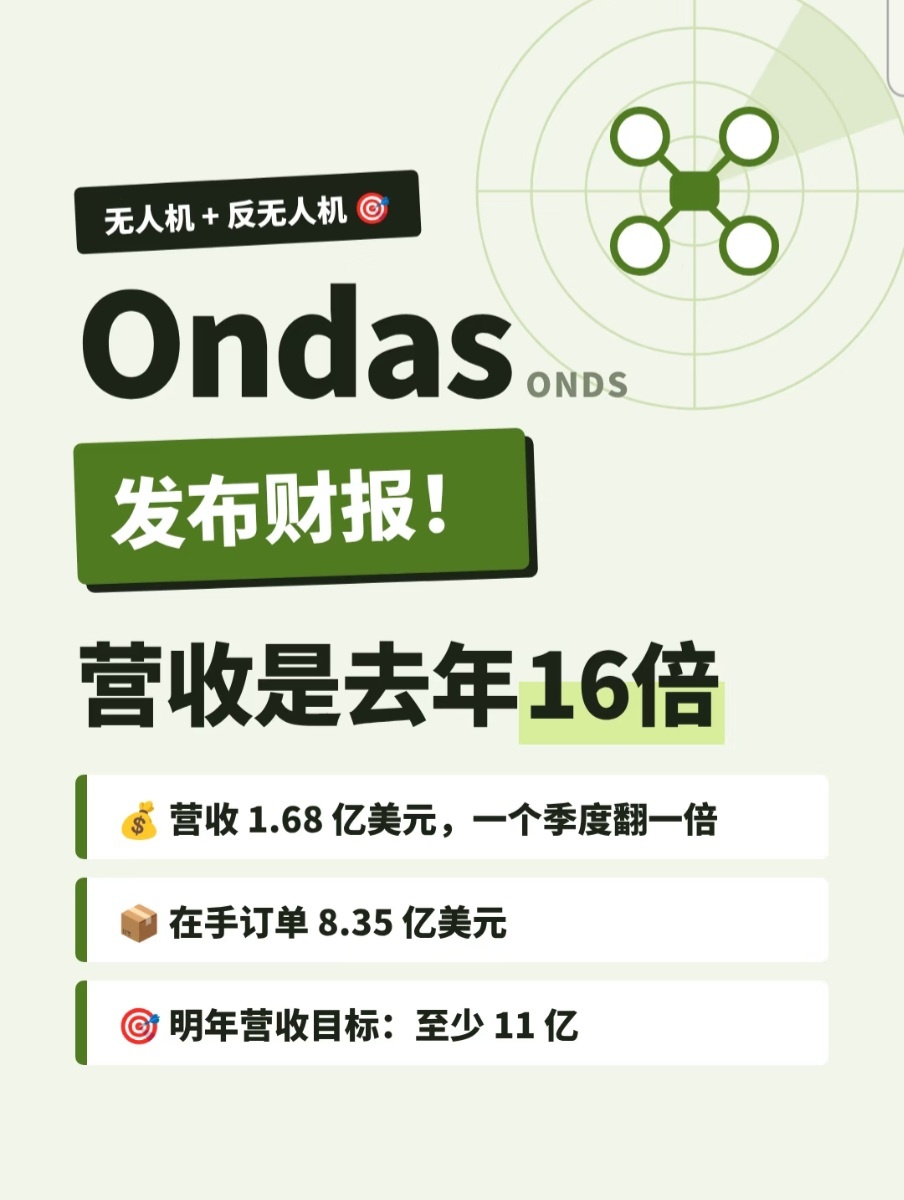
Drone and counter-drone systems maker Ondas (ONDS) just reported earnings, and its revenue is taking off 👇
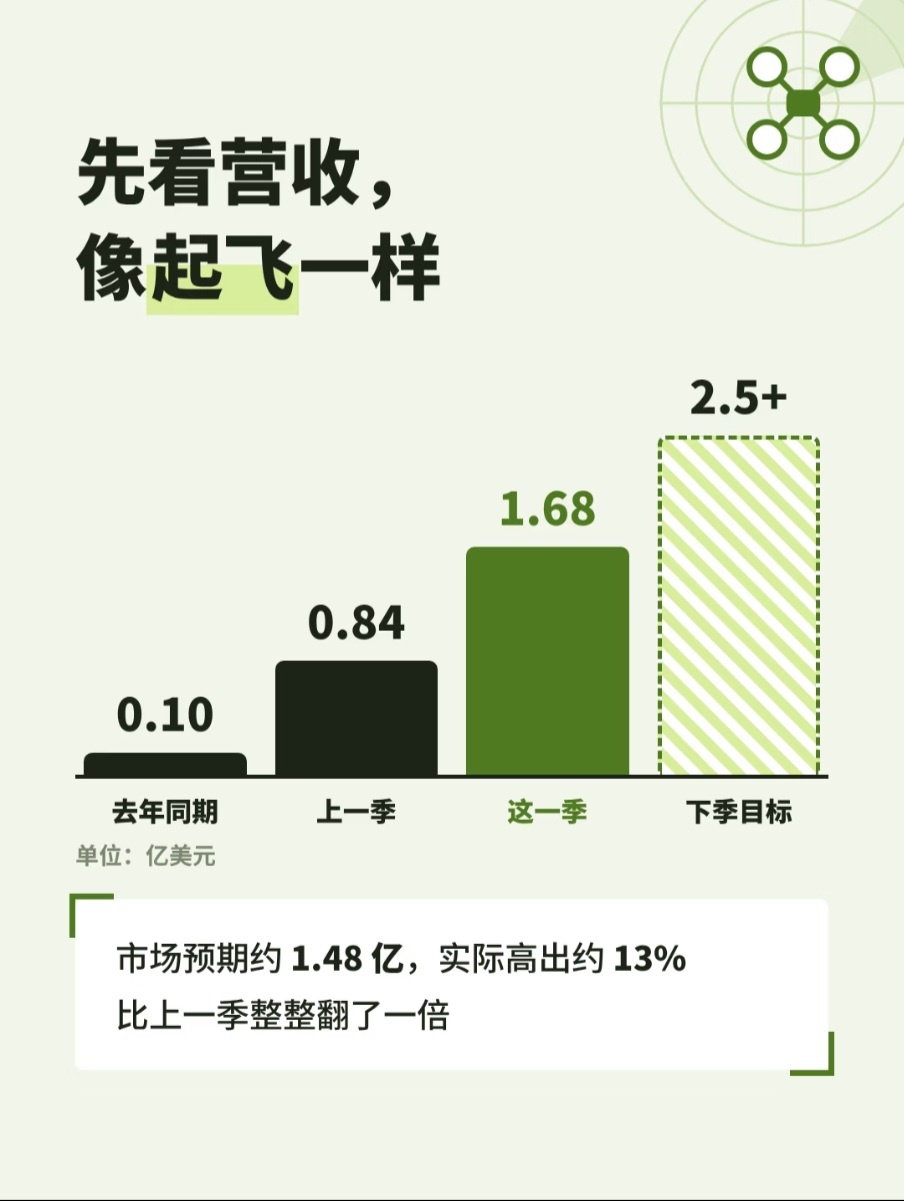
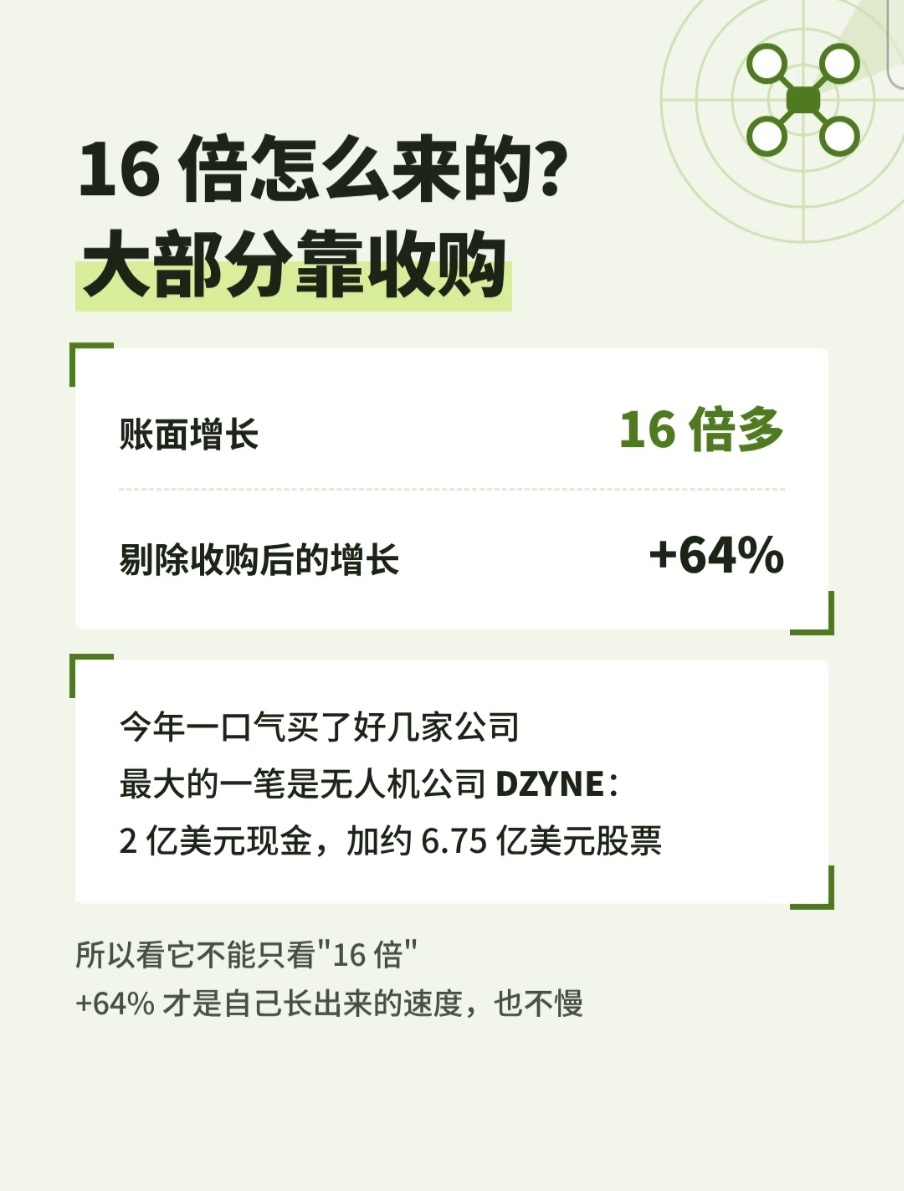
💰 Revenue: $168 million, versus just $10 million in the same quarter last year—more than 16x higher in a year. It doubled from the previous quarter, beat market expectations of around $148 million by about 13%
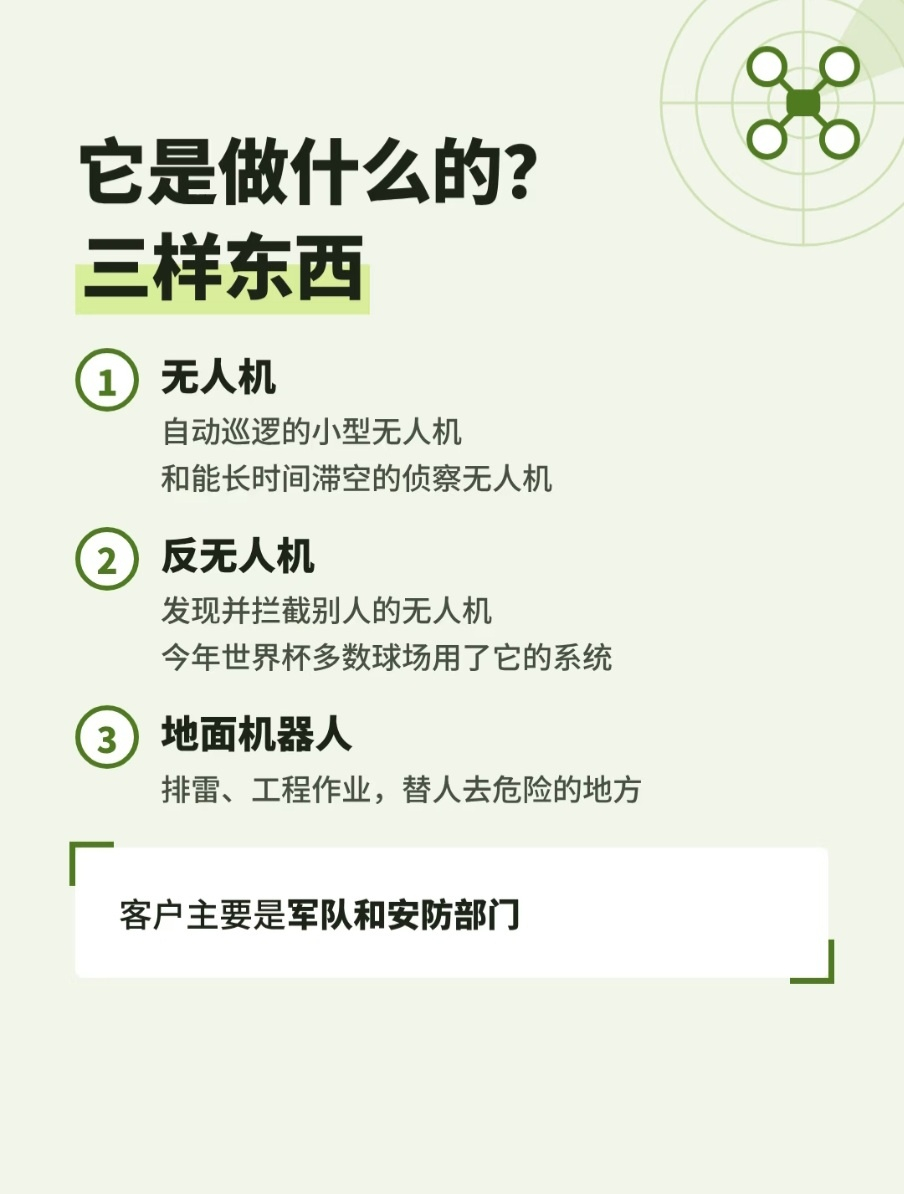
🛸 What does it do? Drones, counter-drone systems (detecting and intercepting other people's drones), and ground robots. Its customers are mainly the military and security agencies. Most World Cup stadiums this year used its counter-drone systems
🧩 Where did the 16x growth come from? Mostly acquisitions: it bought several companies in one fell swoop this year, with drone maker DZYNE being the biggest deal. Excluding acquisitions, organic growth was +64%—that's how fast the business itself is growing
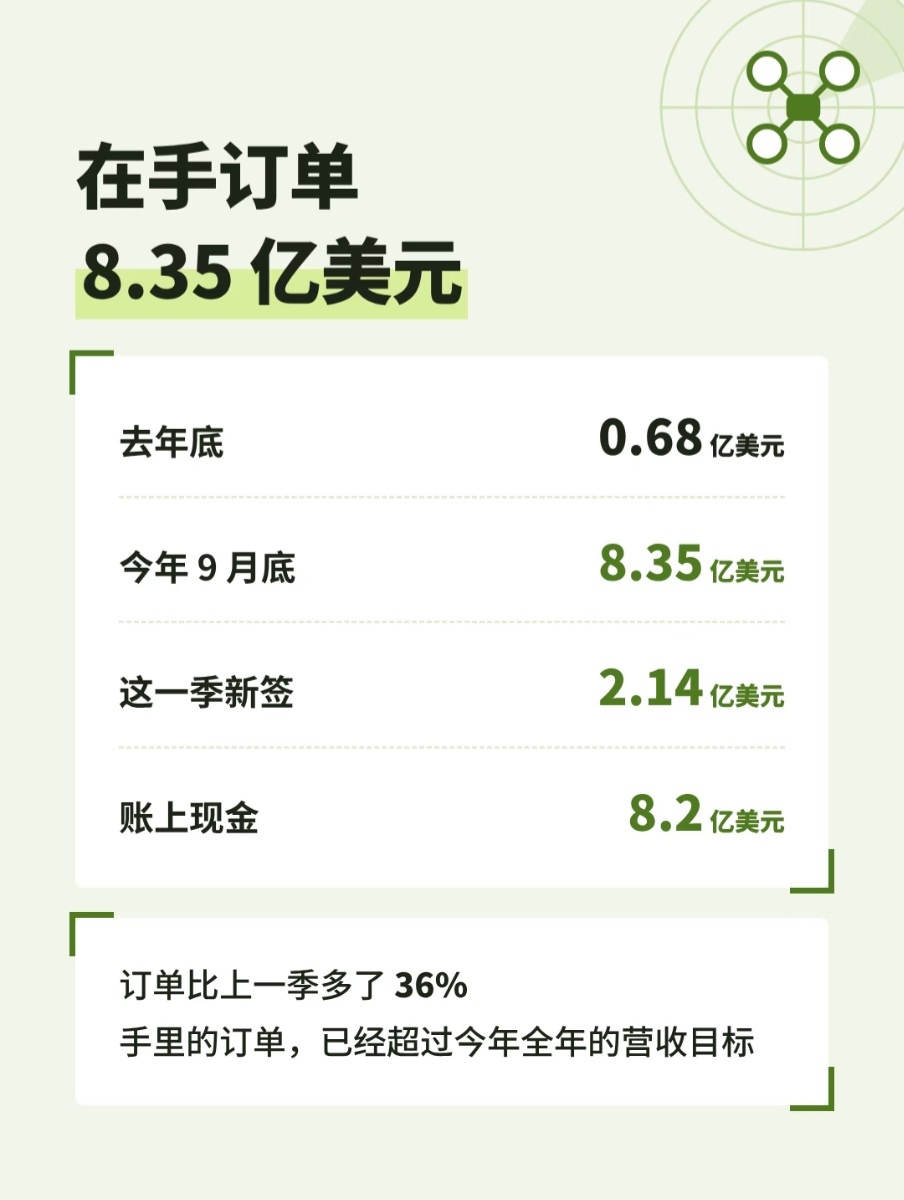
📦 Backlog of $835 million: it was only $68 million at the end of last year, and $214 million in new orders were signed this quarter. Orders on hand already exceed this year's full-year revenue target, and cash on the balance sheet stands at $820 million.
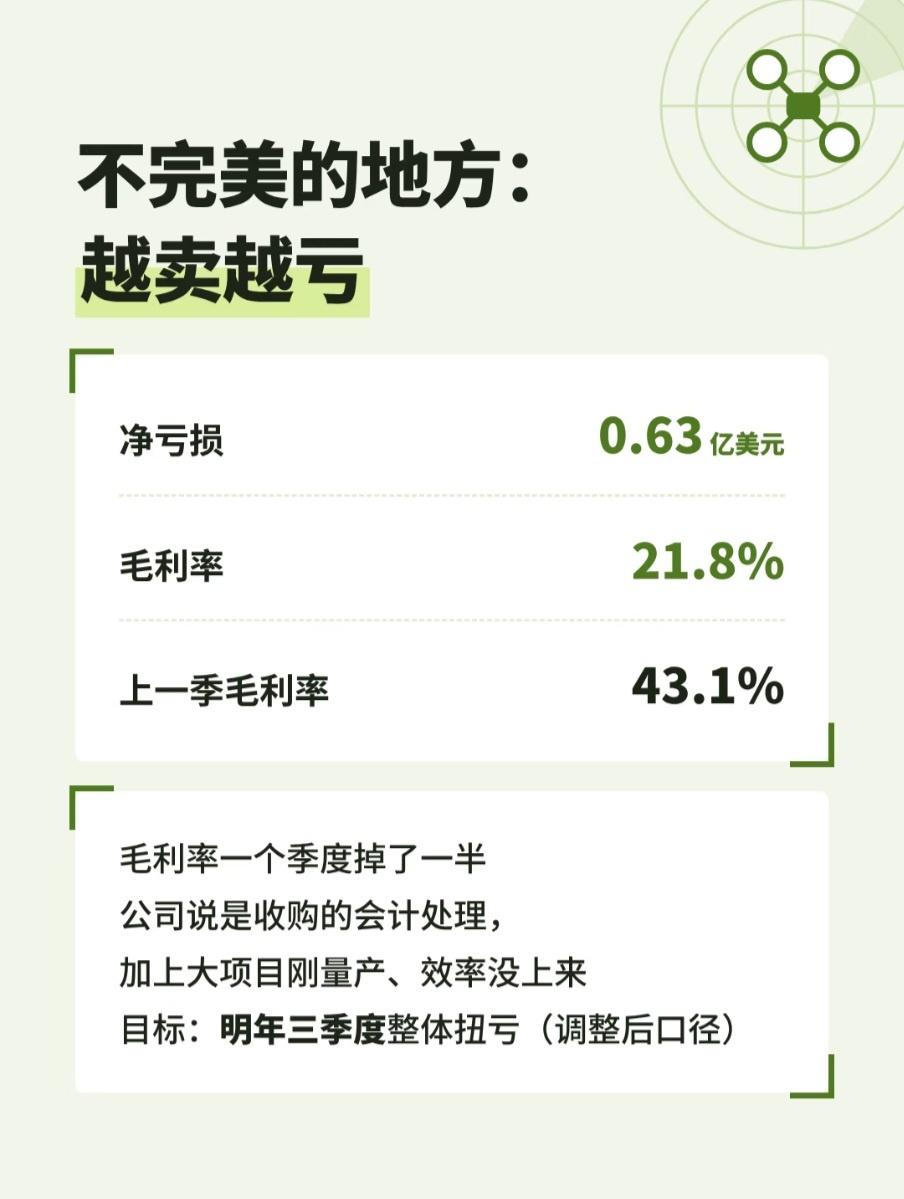
⚠️ The not-so-good part: net loss of $63 million. Gross margin fell from 43.1% last quarter to 21.8%. The company says this is due to the accounting treatment of acquisitions, along with large projects just entering mass production. The goal is to turn profitable overall by the third quarter of next year (on an adjusted basis).
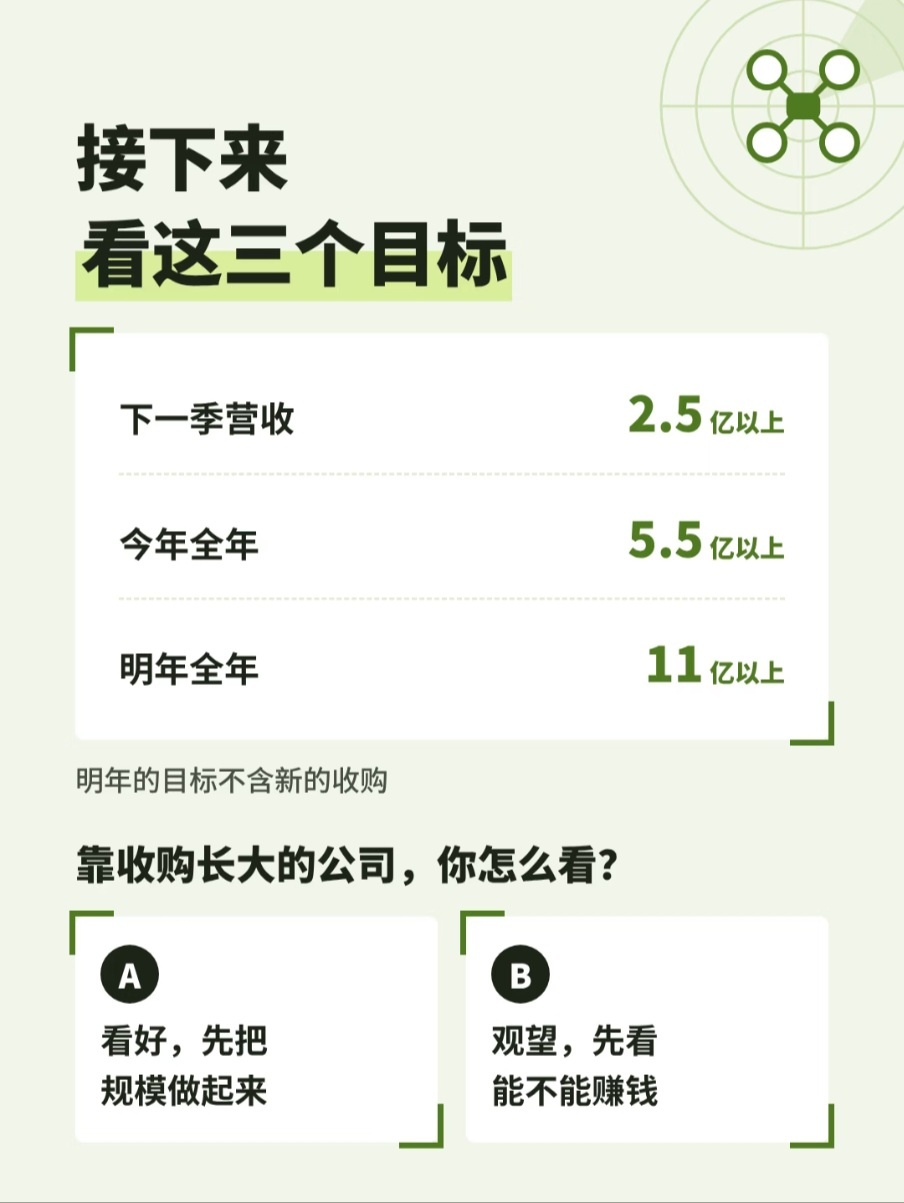
🎯 What's next: revenue of over $250 million next quarter, over $550 million for the full year, and over $1.1 billion next year (excluding new acquisitions).
What do you think of a company growing through acquisitions? A: Bullish—build scale first; B: Wait and see—first see if it can make a profit. Share your thoughts in the comments 👇 (Sharing financial results for informational purposes only; this is not investment advice.)
