
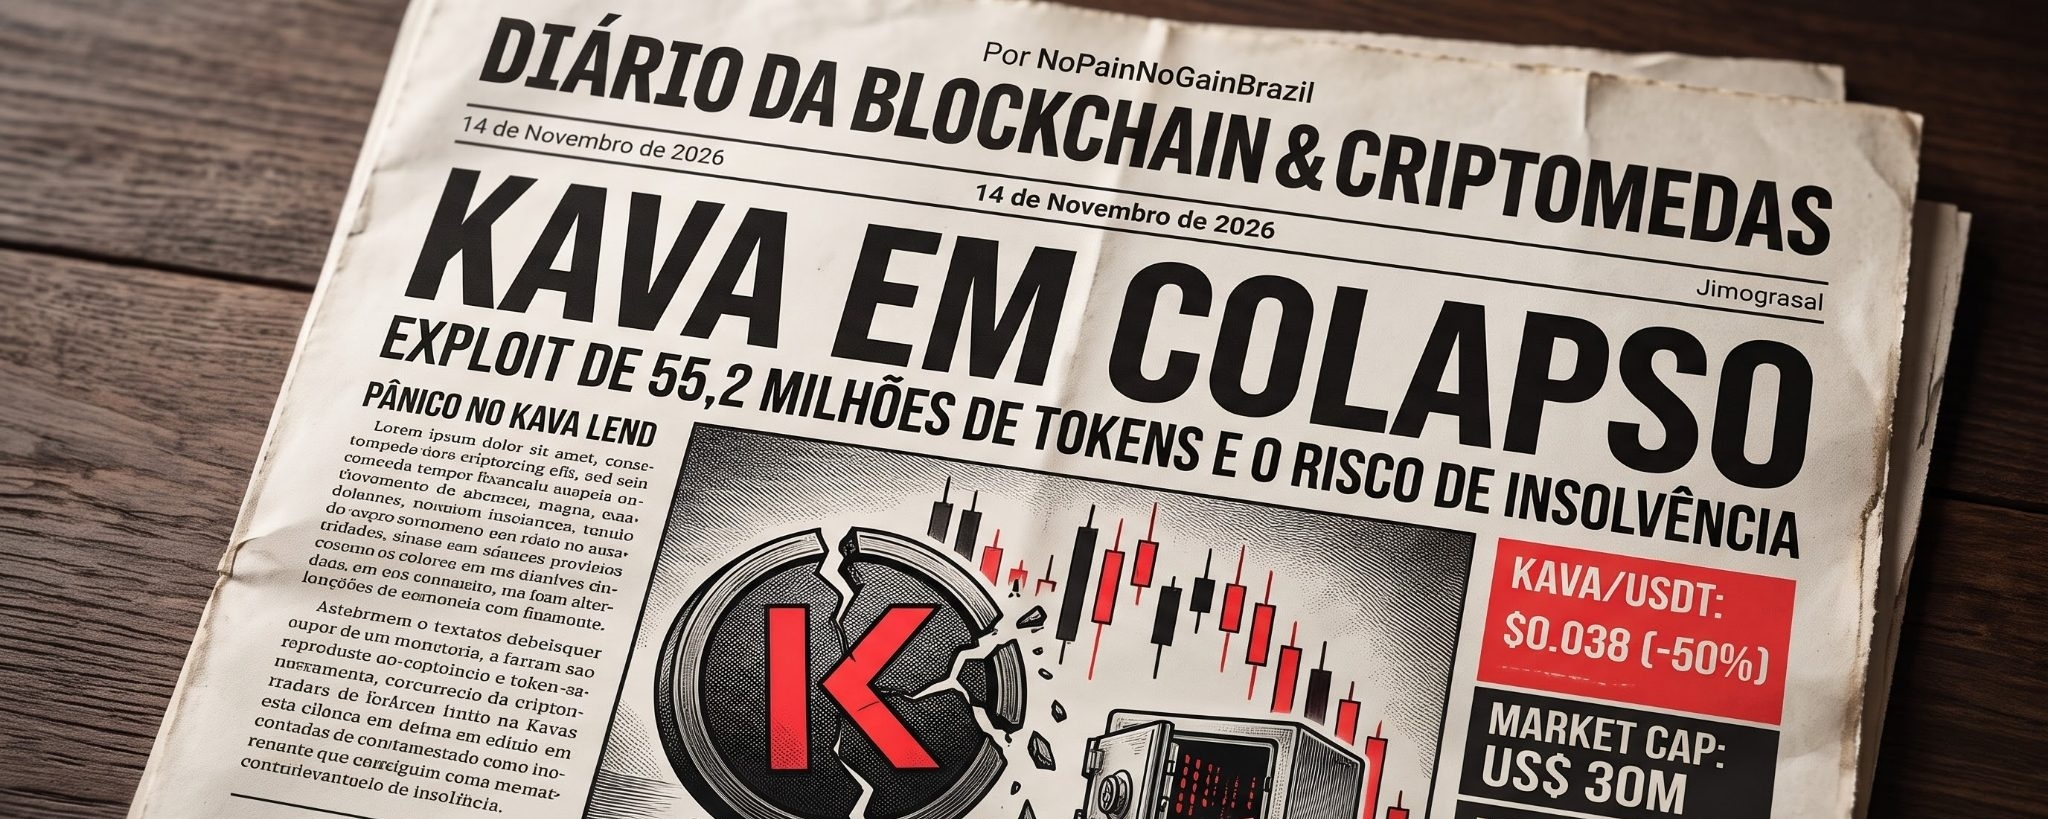
When a Layer-1 asset loses nearly half its value in less than an hour and sees its market capitalization squeezed into the US$30 million to US$42 million range, the question is no longer about an "entry point" but about structural survival.
A cold analysis of the on-chain data and the financial mathematics behind this Saturday's incident (November 14, 2026) reveals a critical scenario that every investor needs to face without romanticizing it.
1. The Mathematical Anatomy of the Supply Shock
Contrary to early rumors, Kava’s main blockchain did not experience infinite coin issuance (infinite mint). The collapse originated within the Kava Lend protocol, where attackers exploited a rounding/division flaw in an inactive BUSD pool:
* By reducing the pool’s liquid supply to a residual fraction, the interest algorithm multiplied the collateral index by 243,000 times in just three minutes.
* With artificially inflated collateral, two wallets drained 55.2 million KAVA through 127 successive loans, reducing the module’s balance from 55.33 million to just 0.19 KAVA.
* Around 48.4 million to 49.2 million KAVA — equivalent to approximately 4.5% to 5.1% of the network’s entire circulating supply — were sent via a bridge to BNB Smart Chain and dumped on DEXs with shallow order books, generating just US$2.09 million in sales and driving the price down from the US$0.068 range to US$0.036–US$0.041.
2. Will Kava Technically Go Bankrupt?
To answer with technical precision, it is necessary to separate infrastructure from economic solvency:
* In the code (Layer 1): A decentralized blockchain does not file for bankruptcy or "close its doors" as long as validators are running nodes. Technically, the network continues producing blocks.
* In the economy (the "Zombie Chain" effect): In financial terms, a project with a market capitalization in the US$30–40 million range faces an almost insurmountable equation:
* Proportionally massive shortfall: The bad debt left on Kava Lend (55.2 million KAVA) represents more than 5% of the network’s entire market value.
* Fixed-supply trap: Since Kava eliminated inflation under its Tokenomics 2.0 model, the foundation cannot simply issue new tokens to cover creditors’ losses. Reimbursing the pool requires burning the foundation’s own treasury reserves — which have just lost nearly half their purchasing power in dollars.
* Liquidity squeeze and delisting risk: South Korean exchanges (Upbit, Bithumb, and Coinone), which accounted for a vital share of KAVA’s actual trading volume, froze deposits and withdrawals. Upbit placed the token on a watchlist for delisting, and Binance added risk alerts.
Realistic Conclusion
Even with around US$612,000 frozen on the Relay bridge, the institutional damage is done. Without an immediate external capital injection from the foundation to fully cover the 55.2 million KAVA drained, and without a post-mortem report that convinces major exchanges not to delist the asset, KAVA faces a serious risk of spiraling into irrelevance — operating as a technically active network, but financially dead due to a lack of liquidity, trust, and capital flows.
\u003e Legal Disclaimer (DYOR): This content is strictly for informational and analytical purposes, based on on-chain and market data available at the time of publication. It does not constitute a recommendation to buy, sell, or hold digital assets. Low-market-cap cryptocurrencies involve an extreme risk of total capital loss. Do your own research (DYOR).
\u003ct-61/\u003e\u003ct-62/\u003e\u003ct-63/\u003e\u003ct-64/\u003e \u003ct-66/\u003e