
I spent the last 48 hours cross-referencing order books, macro prints, and ETF flow sheets—and I’m honestly starting to think we are looking at this whole selloff backwards. 📉
Right now, everyone on my timeline is screaming about crypto-specific drama or hunting for some magic protocol upgrade to save their bags.
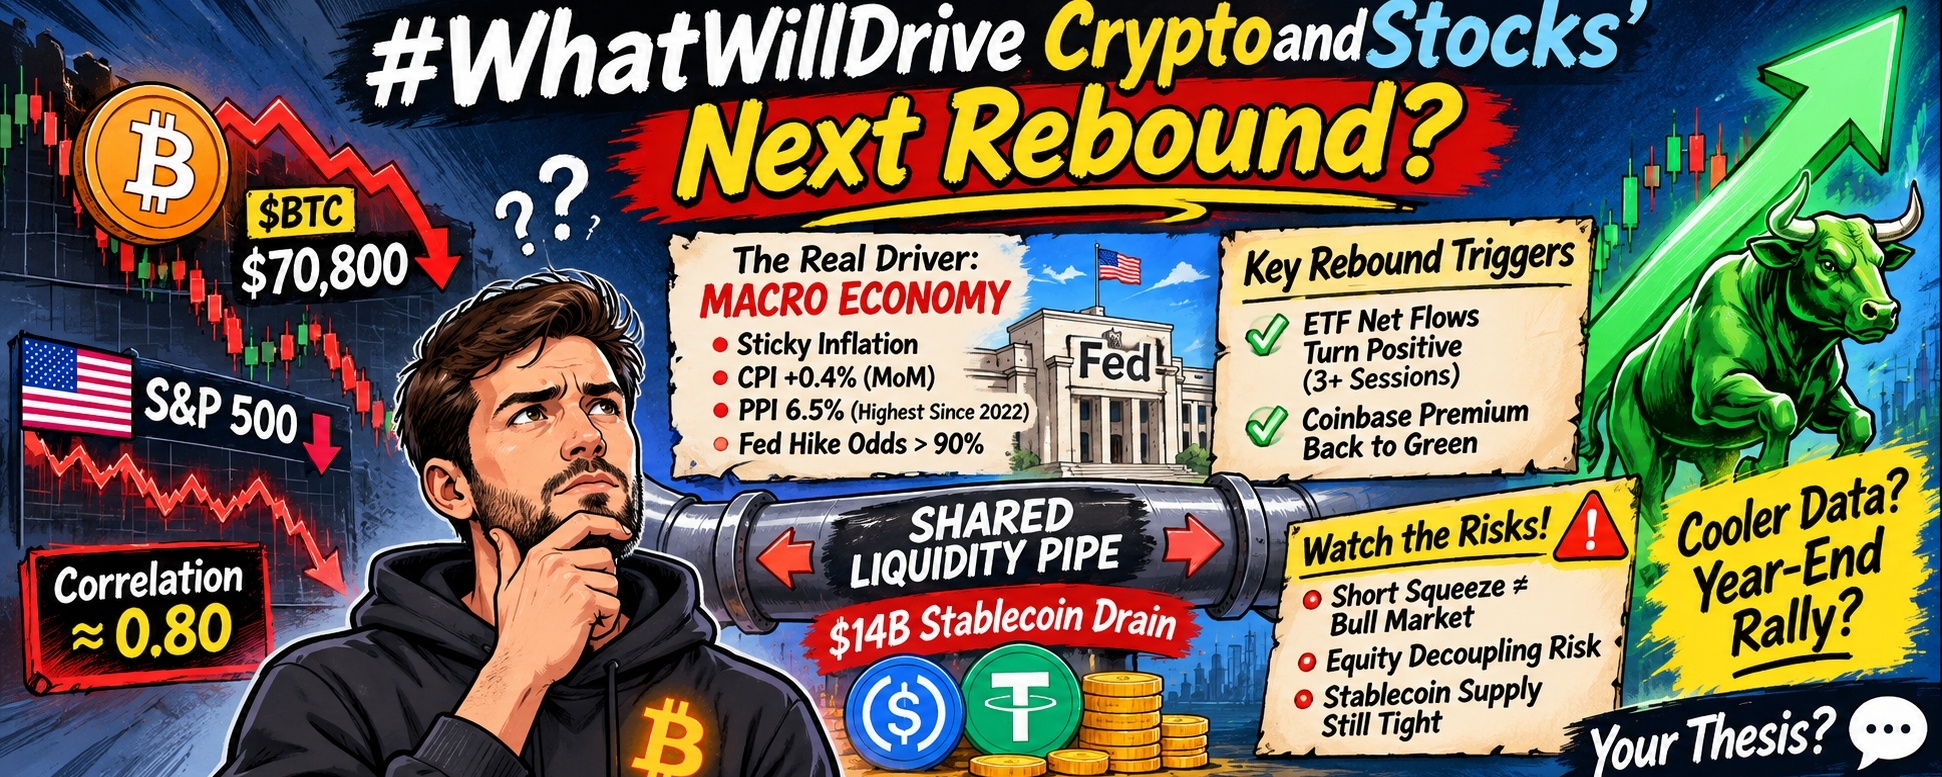
Meanwhile, $BTC just tested the $70,800 zone after slipping below key moving averages, and the S&P 500 has been bleeding right alongside it.
When two completely different asset classes move in near-lockstep—with the 30-day correlation between Bitcoin and the S&P 500 sitting around 0.80—you aren't looking at isolated crypto weakness.
You are looking at one shared liquidity pipe that just got pinched.
If we actually want to catch the next real rebound in both crypto and stocks, we have to stop staring at 15-minute candles and trace the plumbing. 🤔
First, look at what’s actually driving the bus: sticky inflation just ambushed consensus.
October U.S. CPI came in hotter than expected at +0.4% month-over-month, and yesterday’s PPI print showed annual producer inflation jumping to 6.5%—the highest we’ve seen since late 2022.
Almost overnight, futures markets repriced the odds of a December Fed rate hike above 90%, sending Treasury yields and the dollar straight up.
Neither $BTC nor tech stocks can stage a real rebound while the market is actively pricing in tighter money.
In my experience watching macro cycles, markets don't actually need rate cuts to bounce—they just need the fear of surprise hikes to peak.
The first real spark won't come from a crypto headline; it will happen the exact moment incoming labor or inflation data cools down enough to knock bond yields off their highs.
Until the cost of capital stops climbing, every green candle is just a relief bounce fighting gravity.
And honestly, something structural changed over the past two years that I think a lot of retail traders still haven't fully processed.
Because spot ETFs and institutional desks now make up such a huge chunk of daily volume, BTC andETH basically sit inside the exact same risk-parity portfolios as mega-cap tech stocks.
When a multi-asset fund manager sees the VIX spike and equities sell off, their risk engine doesn't care about decentralization or block times.
It just sees a high-beta risk asset and hits sell across the board.
You can see it right on the tape: U.S. spot Bitcoin ETFs bled roughly $1.5 billion over six straight sessions, while quant funds running BTC-equity spread algos mechanically dump whichever side lags, trapping both markets in a feedback loop.
For a rebound to actually stick, two gauges have to flip at the exact same time:
* Spot ETF net flows turning positive for at least three straight sessions, showing Wall Street is done de-risking.
* The Coinbase premium flipping back to green after weeks of relentless U.S. spot discounting.
Wait—let me push back on my own thesis for a second, because something didn't quite add up when I checked the altcoin pairs.
If institutional risk-parity selling explains everything, why haven't all majors bled at the exact same rate?
When I dug into on-chain liquidity, the real bottleneck jumped out: total stablecoin supply just contracted by over $14 billion.
In crypto, stablecoins are the literal fuel in the tank—when that supply shrinks, order books get paper-thin and routine sell orders cause nasty wicks.
Compare that to U.S. equities, where corporate buyback windows and AI infrastructure spending have been quietly propping up the S&P 500 through rough macro patches.
Even inside crypto, capital isn't fleeing blindly—$ETH and SOL have held up noticeably better on a relative basis during this flush, with ecosystems likeBNB and Solana leaning on real user throughput and upcoming catalysts like Breakpoint to absorb the selling.
So the hard constraint is pretty clear: crypto can't outrun a $14B stablecoin drain unless fresh on-chain dry powder returns alongside resilient corporate earnings in stocks.
But here’s what really worries me—and why I’m not rushing to catch every knife. ⚠️
First, a derivatives short squeeze is not a bull market reversal.
Over $1.6 billion in leveraged positions just got wiped out, funding rates have flipped negative, and open interest is compressed.
That setup almost guarantees a violent, face-ripping bounce soon—especially if $BTC defends the 200-week trendline around $68,000.
My worry is that traders will mistake a mechanical short squeeze on thin order books for genuine spot accumulation, FOMO back into high leverage, and get steamrolled on the next macro print.
Second, what if equities and crypto decouple in the exact wrong direction?
If input-cost inflation (like that 6.5% producer price reading) starts eating into corporate profit margins in Q4, stocks could face a real earnings slowdown.
And if the S&P 500 takes another leg down while $BTC is still glued to it at a 0.80 correlation, crypto won't act like digital gold—it will act like a leveraged stress test for equity pain.
Here is the paradox I can’t shake as I stare at these charts: the exact same institutional plumbing that gave $BTC the firepower to push past $70k is now acting like a liquidity straitjacket. 💡
If crypto needs Treasury yields to roll over and Wall Street ETF desks to hit buy before it can rally, did we accidentally trade away crypto’s core independence just to get institutional order flow?
I’m keeping my sizing tight and watching spot ETF flows and stablecoin minting way closer than perp funding right now—but I genuinely want to know where you stand.
Do you think cooler macro data sparks a synchronized year-end rebound for both stocks and crypto, or does $BTC have to break this equity correlation before the next real leg up can start? Drop your thesis below! 👇
#WhatWillDriveCryptoandStocks’NextRebound? #Write2Earn #Macro #CryptoMarket
Not financial advice. Always DYOR.