Why most “profitable” strategies die in a live account 🔍
I ran dozens of strategies through backtests. Many showed impressive gains and fell apart in live trading. Most often, there’s one reason: look-ahead bias — “peeking into the future.”
This is when a test silently uses data that wasn’t available at the time of entry:
• entering at the candle’s open while the signal is calculated at its close;
• the daily high, which is only known at the end of the day;
• an indicator that repaints historical values;
• a filter optimized on the entire history, including the future.
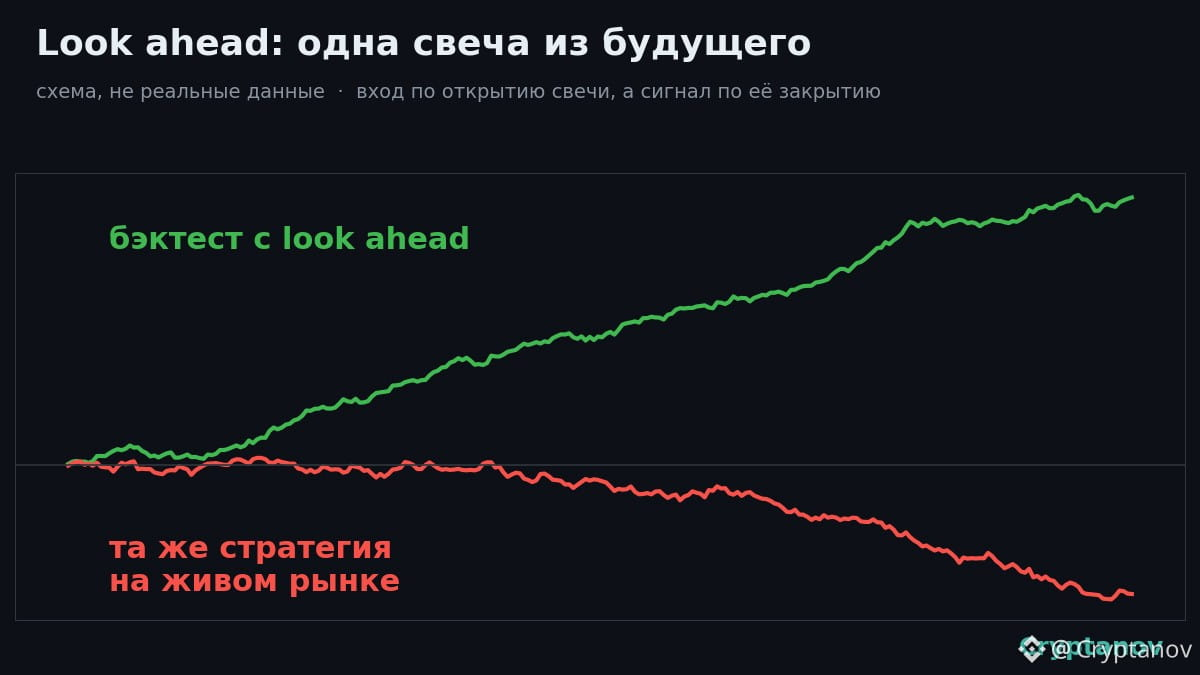
A one-candle error—and the backtest shows +300% a year. In the live market, that candle doesn’t exist, and the strategy becomes a random entry minus fees. The prettier the curve, the more carefully you need to look for it.
Here’s how I do it:
• clean forward testing: every signal is published before the outcome and never changed — already for 5 months;
• exchange verification: I compare signals with real trades on Binance;
• the backtester is calibrated to match forward testing, not the other way around.
A pretty backtest isn’t a strategy. A strategy is what survives in the live market.
All the stats are public — find the Cryptanov website.
#trading #cryptanov
I ran dozens of strategies through backtests. Many showed impressive gains and fell apart in live trading. Most often, there’s one reason: look-ahead bias — “peeking into the future.”
This is when a test silently uses data that wasn’t available at the time of entry:
• entering at the candle’s open while the signal is calculated at its close;
• the daily high, which is only known at the end of the day;
• an indicator that repaints historical values;
• a filter optimized on the entire history, including the future.
A one-candle error—and the backtest shows +300% a year. In the live market, that candle doesn’t exist, and the strategy becomes a random entry minus fees. The prettier the curve, the more carefully you need to look for it.
Here’s how I do it:
• clean forward testing: every signal is published before the outcome and never changed — already for 5 months;
• exchange verification: I compare signals with real trades on Binance;
• the backtester is calibrated to match forward testing, not the other way around.
A pretty backtest isn’t a strategy. A strategy is what survives in the live market.
All the stats are public — find the Cryptanov website.
#trading #cryptanov