
🌍 Uncle’s Weekly Brief|11.09–11.13
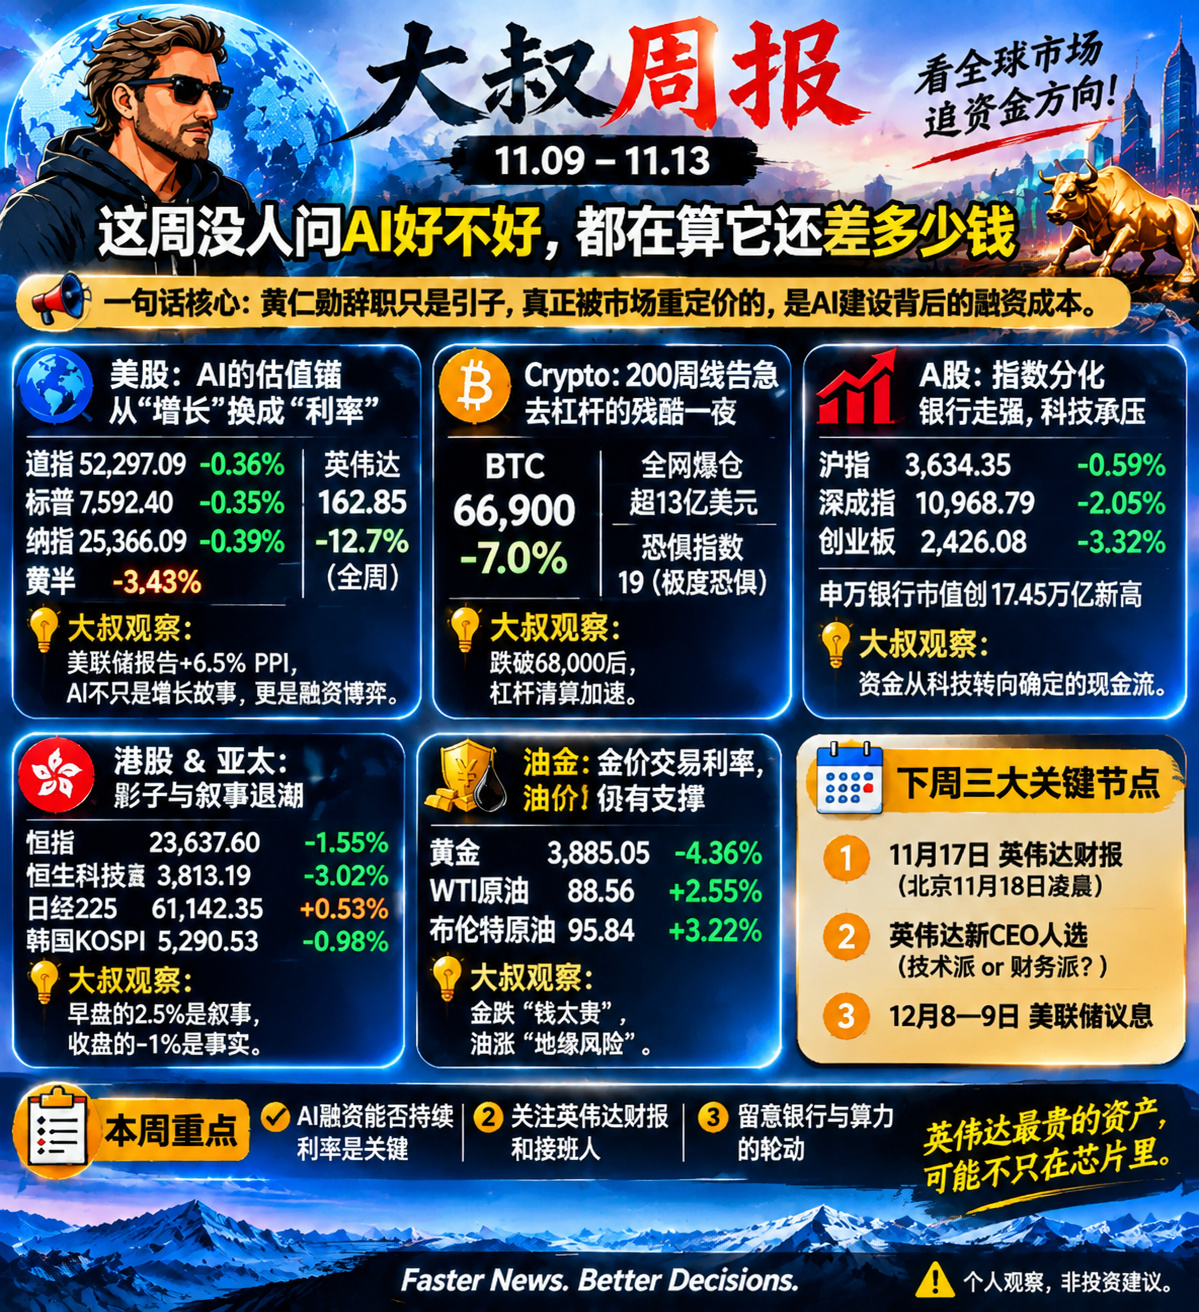
The takeaway in one sentence: Jensen Huang’s resignation was just the pretext. What the market is really repricing is the cost of financing AI development, the capital commitments involved, and who has the ability to keep organizing the money.
▍U.S. stocks: AI’s valuation anchor is shifting from growth to financing costs
U.S. stocks followed a strikingly contrasting path this week.
At the start of the week, money flowed from Nvidia into chipmakers such as AMD and Broadcom, and semiconductor stocks were briefly strong. By Friday, the Philadelphia Semiconductor Index had fallen 3.43% in a single day, AMD was down 8.75%, Broadcom had dropped 4.76%, and Nvidia closed at $162.85.
But note: the semiconductor index still rose about 8.1% for the week, while Nvidia fell about 12.7%. This is not the entire AI supply chain collapsing together. Funds first rotated out of Nvidia and into other chipmakers, then began reassessing the risks of the broader AI infrastructure trade.
What is truly worth watching is the Federal Reserve's semiannual Financial Stability Report.
The report showed that AI-related risks have become the biggest concern among financial market participants: 87% of respondents named them as a major risk, up from 50% in May. As of October, financing issuance related to data centers and advanced computing had reached $680 billion, about one-third of issuance of non-financial investment-grade corporate debt. The report also warned that related commitments, including debt, guarantees, and future leases, could exceed $3 trillion.
Meanwhile, US PPI rose 6.5% year over year in October, its biggest increase since November 2022. Boston Fed President Susan Collins also said that further monetary tightening may soon be needed.
Market takeaway:
Demand for AI has not suddenly disappeared, but the cost of financing AI buildout is becoming increasingly important.
In the past, the market asked only: How many chips can Nvidia sell?
Now it is also asking: How much can cloud providers invest in capex? Can data centers continue to secure financing? If interest rates keep rising, who will bear the growing cost of construction?
AI is not just a growth story; it is also a test of capital endurance.
▍Crypto: 200-week moving average under threat as leveraged positions are flushed out
BTC slid from about $75,000 at the start of the week, touching around $67,500 at one point on Friday and falling below its 200-week moving average near $68,000 intraday, hitting its lowest level since August.
Around Friday, liquidations across the market exceeded $1.3 billion over 24 hours, with longs accounting for the vast majority. The Fear & Greed Index fell into the extreme fear zone.
More notable still, the US Dollar Index rose above 103 and Treasury yields climbed, prompting markets to once again price in the possibility of a December rate hike. Meanwhile, US spot Bitcoin ETFs saw net outflows for several consecutive days.
Market takeaway:
This downturn is not just panic over sentiment; liquidity, rate expectations, and leveraged positions are all under pressure at the same time.
After BTC fell below $70,000, the breach of a technical level triggered a cascade of liquidations. Continued ETF outflows also weakened spot buying.
The crypto market's problem is not whether it has a long-term narrative, but how much capital is still willing to absorb selling after leveraged positions are flushed out.
The area around the 200-week moving average is the key level to watch next, but it is not a guaranteed floor.
▍A-shares: Indexes diverge, banks rally, tech comes under pressure
The Shanghai Composite fell 0.41% for the week, while the Shenzhen Component dropped about 1.85%. But the market's underlying structure is more telling than the headline declines.
On November 13, the ChiNext Index fell 3.32% in a single day and the STAR 50 Index dropped 2.74%. Main-fund net outflows from the electronics sector totaled about RMB 21.4 billion, while communications, electronic components, and semiconductors all came under pressure.
On the other hand, the total market capitalization of the Shenwan Banking Index rose to RMB 17.45 trillion on November 13, a record high.
Market takeaway:
This is not simply a case of “all tech money flowing into banks”; rather, risk appetite has clearly diverged.
On one side, the AI hardware supply chain needs continued capital investment, while earnings delivery and valuations face higher hurdles. On the other, bank stocks are attracting more attention thanks to their dividend yields and relatively stable cash flows.
Technology stocks need to prove their future growth, while bank stocks are delivering returns that are visible today.
The market is not unwilling to buy growth; it is starting to demand a clearer path to turning that growth into results.
▍Hong Kong & Asia-Pacific: Tech premium fades as the market starts to distinguish genuine strength from the rest
Hong Kong stocks:
The Hang Seng Index fell about 3.45% for the week, while the Hang Seng TECH Index dropped about 6.50%. On November 13, the Hang Seng Index closed at 23,637.60 points and the Hang Seng TECH Index at 3,813.19 points.
Southbound funds recorded net purchases of about HK$2.33 billion on Friday, but tech stocks still saw a notable correction.
Southbound buying shows that some funds are stepping in to absorb the selling; it does not mean all selling pressure has been offset.
Asia-Pacific:
Japan's Nikkei 225 rose about 6.46% for the week, gaining another 0.53% on Friday to close at 61,142.35 points.
South Korea's KOSPI fell 0.98% on Friday but still rose about 4.56% for the week. On Thursday, the Korean market saw a sharp intraday rally followed by a pullback, showing that the short-term narrative has not yet translated into sustained buying.
Market takeaway:
Even within the same AI supply chain, the market is starting to distinguish between companies with real orders, those with sustainable earnings, and those whose valuation premium depends only on market sentiment.
An entire industry chain does not lose all its value just because one CEO leaves. But the premium that was once priced in as a package is now being broken apart and reassessed.
▍Oil & gold: The dollar and interest rates reclaim pricing power
Gold: Down about 4.4% this week, with the weekly close back below $3,900. Stronger-than-expected US inflation data, a rising dollar, and higher Treasury yields put significant pressure on gold. Gold has not lost its safe-haven appeal, but in the short term its pricing is more heavily influenced by real interest rates and the dollar.
Crude oil: WTI closed at $88.56 on Friday, while Brent closed at $95.84. Oil prices remain relatively high, as the geopolitical risk premium and supply-demand expectations continue to pull in opposite directions.
Market takeaway:
The clearest shift this week was that the market put interest rates back at the center of pricing.
Interest rates affect tech stock valuations, the cost of holding gold, corporate financing, and the leverage available to risk assets.
When rate expectations tighten again, all assets that depend on future growth have to be reassessed.
▍Three key events to watch next week
① November 17 | Nvidia earnings
Results will be announced early on the morning of November 18 Beijing time.
This is the first earnings report since Jensen Huang's departure. Beyond revenue and profit, pay close attention to the order backlog, next-quarter guidance, customer capex, and management's explanations of supply-chain and financing arrangements.
Don't focus only on quarterly figures. Watch whether the funding behind AI buildout can continue to expand.
② Nvidia's new CEO candidate
The market has begun to focus on the successor's capabilities. Arm CEO Rene Haas has been reported as one potential candidate approached by the board, but no formal choice has been confirmed.
What really matters is not who takes over, but whether the new leadership can sustain customer relationships, industry collaboration, and the ability to organize the ecosystem.
③ December 8–9 | Federal Reserve rate meeting
October PPI rose 6.5% year over year, Treasury yields climbed, and market expectations for December policy shifted sharply.
If interest rates continue to rise, tech stock valuations, gold, and crypto assets will all be affected.
💎 Big Uncle's view
On the surface, this week's story was about one person leaving. Beneath that, three things are really changing:
1. The valuation anchor has shifted.
AI is no longer valued solely on the pace of growth. With $680 billion in related financing, plus even larger debt, guarantee, and lease commitments, the market is starting to focus on where the funding for AI buildout comes from and whether it can be repaid.
Borrowing to build is not the problem. The problem is when financing costs rise and future revenue takes too long to materialize.
2. The leadership premium is being reassessed.
Goldman Sachs cut its price target for Nvidia from $300 to $220, while maintaining a Buy rating. That $80 difference is not a formal valuation of Jensen Huang's personal worth; it reflects the market repricing uncertainty around leadership changes and valuation multiples.
Nvidia's competitive edge lies not only in its chips, but also in its customer relationships, software ecosystem, and ability to organize the industry supply chain.
3. Investors are becoming more selective about the quality of growth.
US stocks diverged across chipmakers, China's A-share banking sector hit a record market capitalization, Hong Kong tech stocks came under pressure, and BTC saw large-scale leveraged liquidations.
This does not mean global capital has uniformly shifted to cash flow. Rather, the market is starting to demand that high-valuation assets prove their growth can materialize, financing can be sustained, and cash flow can keep up.
Next week, don't just focus on how much Nvidia earns. Watch whether it can prove that, even without Jensen Huang, the AI supply chain can continue to bring together capital, customers, and orders.
The AI story is not over, but the market is no longer willing to buy the story alone.
Are the positions you hold this week being propped up by a story, or backed by cash flow?
Watch global markets. Follow the flow of capital. Faster News. Better Decisions.
Personal views, not investment advice.