
Over the past 24 hours, global capital markets have come under multiple pressures.
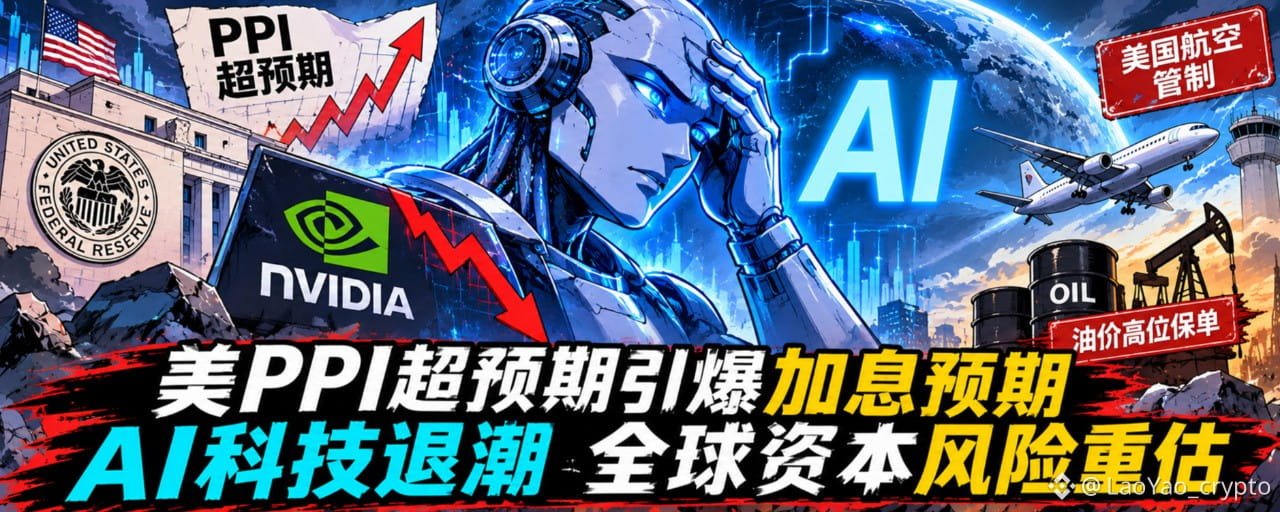
U.S. PPI for October came in above expectations, with inflationary pressures proving sticky once again. Two Federal Reserve officials successively sent hawkish signals, emphasizing that inflation remains at risk of resurging and that monetary policy should not be eased prematurely.
Market dynamics are shifting:
Inflation rebounds → rate hike expectations rise → U.S. Treasury yields climb → the dollar strengthens → tech stock valuations come under pressure → liquidity in crypto markets contracts
Meanwhile, news related to Nvidia (Nvidia, $NVDAB ) continues to roil the AI tech sector, and the market is beginning to reassess the valuation boundaries and capital returns of the AI industry.
📌 Two other technology infrastructure incidents are also worth noting:
- The U.S. issued a flight-grounding order, severely disrupting the nation's aviation system. The investigation is focused on an AI-assisted air traffic control system.
- Several Microsoft cloud and office applications experienced widespread outages, affecting numerous businesses and government agencies.
Beyond the AI investment boom, the reliability of technology infrastructure is also becoming a focus for capital markets.
🧱 Geopolitics: Risks in the Middle East are heating up again
The White House and G7 allies are coordinating on shipping security in the Red Sea and Strait of Hormuz, concerned that rising energy prices could further hit U.S. consumption and inflation.
Shipping insurance premiums have risen and tanker diversions are adding to transportation costs, but there has been no full-scale blockade so far.
Geopolitical risk remains one of the main factors influencing global energy pricing.
💹 Capital markets: Inflation and interest rates are back in the driver's seat
U.S. Treasury yields are rising, the dollar is strengthening, U.S. tech stocks are under pressure, crude oil remains elevated and range-bound, and precious metals are mixed.
U.S. October PPI came in above expectations, prompting the market to reassess the Fed's monetary policy path for December.
Japanese stocks, meanwhile, are supported by expectations that yen depreciation will improve export competitiveness.
📊 Bond market: U.S. Treasury yields remain elevated
U.S. 2-year Treasury: 4.848%
U.S. 10-year Treasury: 5.137%
U.S. 30-year Treasury: 5.468%
Japan 10-year government bond: 2.860%
PPI inflation proved stickier than expected, prompting the market to raise its expectations for future rate hikes.
Short-term yields reflect monetary policy expectations, while long-term yields are also influenced by fiscal deficits, Treasury supply, and the term premium.
U.S. Treasury yields remain elevated, meaning valuation discount pressures on global risk assets persist.
📈 U.S. stocks: A clear divergence between tech growth and traditional value
Nasdaq: -0.91%
S&P 500: -0.40%
Dow Jones: +0.10%
The three major indexes moved in different directions.
Traditional value and defensive sectors held up relatively well, while the Dow maintained a modest gain;
AI chips and tech growth stocks continued to face pressure.
The market is shifting from simply chasing AI growth expectations to reassessing whether tech companies can deliver earnings and whether their valuations are justified.
🛢️ Crude oil: Geopolitical risks keep prices elevated and range-bound
WTI: $88.56/barrel, -0.20%
Brent: $96.34/barrel, +0.54%
Geopolitical risks in the Middle East are supporting Brent crude's premium.
However, a rebound in U.S. inflation and rising rate-hike expectations have heightened concerns about a global economic slowdown, limiting further gains in oil prices.
The market remains focused on shipping security in the Strait of Hormuz and the potential impact on energy supplies.
🥇 Precious metals: Rising yields weigh on gold
Gold: $3,887.60/ounce, +0.06%
Silver: $48.65/ounce, -2.83%
Rising U.S. real yields and a stronger dollar are weighing on gold.
Geopolitical risks are providing some safe-haven support.
The divergence between gold and silver reflects the market's effort to rebalance monetary policy risks against demand for geopolitical hedges.
💸 FX: The dollar strengthens as the yen remains under pressure
U.S. Dollar Index: 103.412, +0.23%
USD/JPY: 159.78
EUR/USD: 1.1023
Offshore yuan: 6.6741
U.S. inflation data reinforced expectations that interest rates will remain elevated, supporting the dollar.
The yen remains weak, and the market is closely watching for possible intervention by Japanese authorities in the foreign exchange market.
💸 Web3: Monetary tightening and deleveraging are amplifying each other
The crypto market remained weak over the past 24 hours.
Expectations of macroeconomic rate hikes, a pullback in AI tech stocks, ETF outflows, and leveraged liquidations have combined to create multiple headwinds.
The crypto market's total capitalization fell significantly, with major assets hitting three-month lows and market sentiment dropping into extreme fear territory.
📌 Key market data
Total crypto market cap: approximately $2.33–$2.36 trillion, down around 6%–8% over 24 hours.
$BTC : $68,000, with an intraday low of $67,555, its lowest level since August; market cap around $1.38 trillion.
$ETH : approximately $1,930, declining alongside BTC; DeFi and L2 ecosystems are also under pressure, while Ethereum ETFs continue to face redemption pressure.
BTC's share of the market edged up, reflecting a shift of funds toward leading assets rather than active new buying across the market.
🧘 Crypto reflections: Capital is redefining risk and value
Over the past 24 hours, global capital markets have undergone a multidimensional reassessment of risk:
AI narrative: Controversy involving Jensen Huang continues to unfold, weighing on AI tech stock valuations as the market begins scrutinizing the industry's return on investment.
Political cycle: Following the U.S. midterm elections, policy expectations are gradually filtering through to the tech industry, financial markets, and crypto regulation.
Geopolitics: Risks in the Middle East are heating up again, supporting energy prices and reviving inflation expectations.
Monetary policy: Fed officials have sent hawkish signals, bringing rate-hike expectations back into focus.
Global capital: U.S. Treasury yields remain elevated and the dollar is strengthening, putting global risk assets under valuation discount pressure.
The key to this correction is not just falling asset prices; capital's pricing logic is changing.
In the past, the market was willing to pay a hefty premium for AI growth expectations;
now, capital is starting to ask about returns on investment.
In the past, the crypto market relied more on liquidity expansion;
now, interest rates, the dollar, and institutional fund flows are reshaping market valuations.
From geopolitics to monetary policy, and from traditional finance to digital assets, global capital is undergoing a cross-market repricing of risk.
For investors, what truly matters is not predicting every short-term move, but recognizing shifts in capital cycles and understanding where risks originate and where they may spread.
View capital through the lens of mind philosophy; discern trends through cycles. Follow the trend rather than defy it.
⚠️ The above represents personal views and is intended solely for market observation and discussion.
Geopolitical conditions can change rapidly. Please be mindful of position sizing and leverage risks. This is not investment advice.
📌 LaoYao (@LaoYao_crypto )
View capital through the lens of mind philosophy; discern trends through cycles. Seek certainty amid uncertainty and anchor value amid volatility.