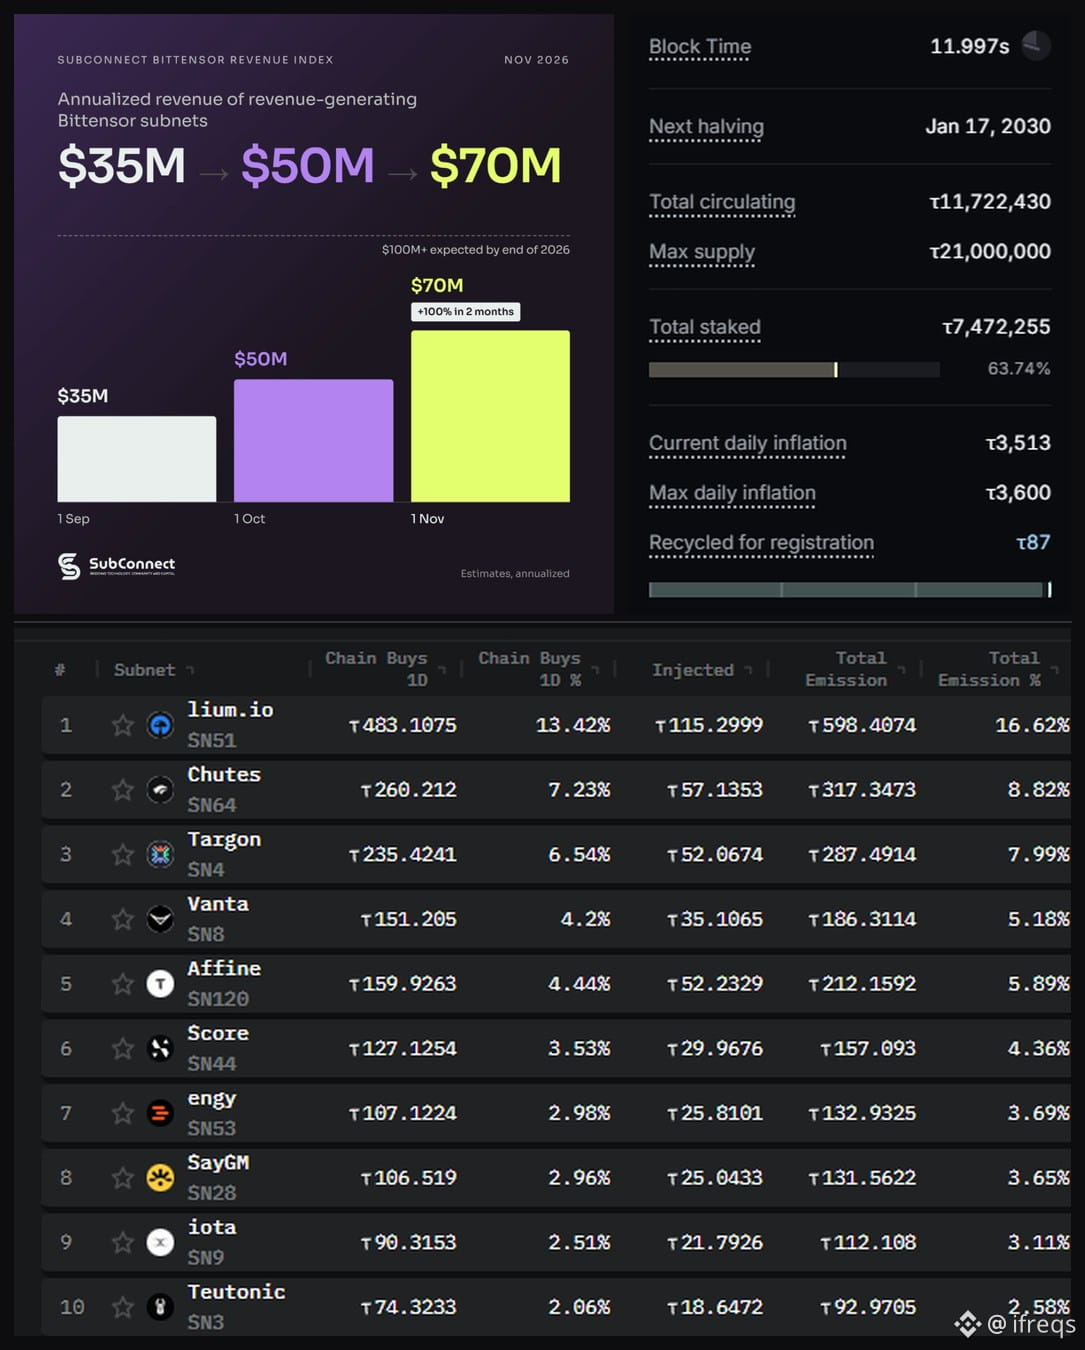

Bittensor subnet revenue doubled in two months, per SubConnect's revenue index: from $35M to $70M a year. Here's the other side of the ledger.
Bittensor mints 3,600 TAO a day for its subnets. At ~$210, that's about $277M a year.
So outside revenue now covers about a quarter of it:
~Sep 1: $35M vs ~$298M a year in emissions, 12%
~Oct 1: $50M vs ~$402M, 12%
~Nov 1: $70M vs ~$310M, 23%
That's a pretty interesting jump. TAO was ~$227 on Sep 1 and ~$236 on Nov 1, so the move came from revenue, not from a cheaper subsidy.
In April, a widely shared bear case put it at $328M printed vs $15M earned.
It's concentrated though. Lium, Chutes and Targon take a third of daily emissions per taostats, and the same three made up nearly half of revenue in the first index.
My read is $TAO finally has a revenue line worth tracking, but issuance still pays for roughly three quarters of the network.
But I wouldn't treat these as audited numbers. They're annualized estimates, and plenty are self-reported.
At what coverage would you call Bittensor self-sustaining?
Bittensor mints 3,600 TAO a day for its subnets. At ~$210, that's about $277M a year.
So outside revenue now covers about a quarter of it:
~Sep 1: $35M vs ~$298M a year in emissions, 12%
~Oct 1: $50M vs ~$402M, 12%
~Nov 1: $70M vs ~$310M, 23%
That's a pretty interesting jump. TAO was ~$227 on Sep 1 and ~$236 on Nov 1, so the move came from revenue, not from a cheaper subsidy.
In April, a widely shared bear case put it at $328M printed vs $15M earned.
It's concentrated though. Lium, Chutes and Targon take a third of daily emissions per taostats, and the same three made up nearly half of revenue in the first index.
My read is $TAO finally has a revenue line worth tracking, but issuance still pays for roughly three quarters of the network.
But I wouldn't treat these as audited numbers. They're annualized estimates, and plenty are self-reported.
At what coverage would you call Bittensor self-sustaining?