
Watching the markets on the afternoon of November 13, Beijing time, it was easy to get the wrong impression. The Nasdaq fell just 0.39% last night, so why did Bitcoin’s loss suddenly come close to 7%, with $1.4 billion in liquidations alongside it?
Both markets did fall, but in very different ways. Looking at data from U.S. stocks, Treasury bonds, and the crypto market itself, two things happened at once this time around. In traditional markets, Treasury yields rose and stocks pulled back. In crypto, falling prices triggered the liquidation of a large number of long positions. The former sets the market backdrop; the latter explains why the crypto market moved so sharply.
First, let’s look at the liquidation tally: how much of it came from longs?
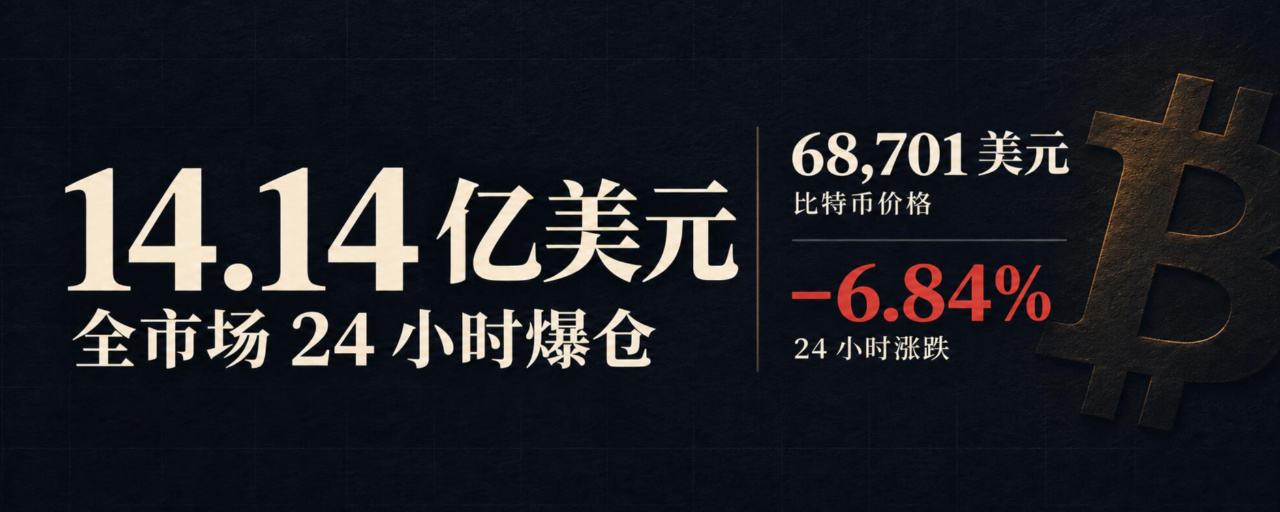
At around 14:00 Beijing time on November 13, the CoinGlass dashboard showed approximately $1.414 billion in liquidations across the market over the past 24 hours. Bitcoin was trading at around $68,701, down approximately 6.84% over 24 hours. “Across the market” here refers to liquidation data aggregated from the trading platforms covered by CoinGlass. The 24-hour window is rolling, so figures captured in the morning and afternoon will differ.
To see which side was getting liquidated, look at an earlier snapshot published at 09:54 Beijing time. At that point, liquidations across the market over 24 hours totaled about $681 million, of which approximately $599 million were long positions, or 88%. In the same snapshot, Bitcoin liquidations totaled around $325 million—nearly half the market-wide total—and approximately 95.3% of BTC’s liquidations were long positions. These percentages apply only to that morning snapshot; the $1.414 billion figure from the afternoon reflects a different rolling window.
Here’s an example. Two people are both bullish on Bitcoin. One buys spot with their own money; the other opens a leveraged long position. When the price suddenly drops, the first person opens their app and sees an unrealized loss. The second person’s margin falls below the maintenance requirement, and the position may be forcibly closed by the system. Long liquidations generate additional sell orders as positions are closed. If buying interest is already thin, one batch of liquidations can push the price lower, triggering the liquidation thresholds of another batch of positions. While someone is still wondering, “Should I wait a little longer?”, the system has already made the decision for them.
So liquidation data is most useful for showing which side’s leveraged positions were cleared out in a concentrated wave during the decline. The $1.414 billion figure is the notional value of positions that were forcibly liquidated. This tally alone cannot tell us which initial sell order or news item triggered the drop.
U.S. stocks fell less; Treasuries are more worth watching alongside them
At the close on November 12, U.S. local time, the S&P 500 was down about 0.35% and the Nasdaq Composite about 0.39%. The U.S. Dollar Index was near 103.17, up from the previous day. The 10-year U.S. Treasury yield reported by the Treasury Department was 5.10%, compared with 4.98% on the previous trading day for which a reading was available—a difference of 12 basis points. The U.S. stock figures are closing changes, while Bitcoin’s figure is a rolling 24-hour change. They are useful for viewing the market backdrop side by side, but shouldn’t be used to calculate directly how many times more one fell than the other.
The inflation data released a couple of days earlier also belongs in this context. On November 10, the U.S. Bureau of Labor Statistics reported that the CPI rose 0.4% month over month in October, while core CPI rose 0.3%. The 10-year Treasury yield rising to 5.10% means investors faced a higher low-risk return benchmark when holding volatile assets. U.S. stocks closing lower, a stronger dollar, and rising Treasury yields together reflect the environment of pressure on risk assets during this period. To understand why Bitcoin suddenly dropped further in a particular hour, we need to look at trading and liquidation data within crypto markets.
There’s another set of figures in crypto: spot ETF funds are also flowing out
According to Farside’s data, U.S. spot Bitcoin ETFs saw net outflows of approximately $201 million, $95 million, and $300 million on November 9, 10, and 11, respectively, totaling about $596 million over the three trading days. At the time of checking, some funds’ figures for November 12 had not yet been filled in, so this comparison uses only the first three trading days.
ETF outflows and contract liquidations both look like big numbers, but they measure two different things. ETF flows reflect net subscriptions and redemptions of fund shares; liquidation amounts reflect the scale of derivatives positions forcibly closed. Adding $596 million and $1.414 billion together and writing “$2 billion in funds fled Bitcoin” would make for a scary headline, but the figures don’t add up that way.
Each set of figures in this review serves a different purpose. Treasury yields and the U.S. stock market close describe the risk environment at the time; ETF data adds the funding backdrop from the few trading days before the decline; and liquidation data tells us which side’s leverage was mainly forced out when the sell-off was sharpest. The same red candle on a screen looks like a price drop to spot holders, but for holders of long contracts, it may mean their position is already gone. That’s the most immediate difference between this Bitcoin move and the overnight pullback in U.S. stocks.
\u003ct-46/\u003e
