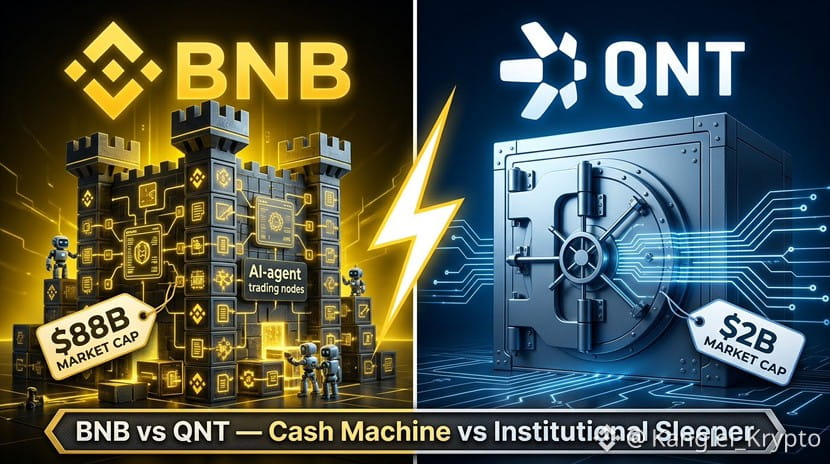
$BNB vs. $QNT : The $88B Cash Machine vs. the $2B Institutional Sleeper💥🚀
One prints fees. The other prints bank rails. Your capital can only ride one horse—choose wisely.
BNB trades at $655.85, holding an $88.5 billion market cap with $11.2 billion in 24-hour volume. QNT sits at $161.78, a $2.01 billion cap on just $80 million volume—a 44x size gap that screams asymmetric risk.
BNB is the fortress. BSC TVL commands $5 billion, and the 2026 roadmap is a direct missile at AI-agent trading: a 100,000 TPS Layer-1 with sub-50ms pre-confirmation, testnet late 2026, mainnet early 2027. Add the quarterly auto-burn grinding supply toward 100 million, and BNB is a cash-flow-backed infrastructure monopoly. It survives on revenue, not narrative.
QNT is the wildcard. The September 2026 Clearing House mandate—building the interoperability layer for tokenized US bank deposits—sent QNT up nearly 300% in a week. But here is the kill shot: QNT’s role in that bank network remains “unclear,” and institutions can pay Quant in fiat, not QNT. Commercial success does not automatically equal token demand. QNT is a high-conviction bet on enterprise adoption and token capture—two separate hurdles.
The verdict: BNB is the institutional-grade compounder trading below its 200-day EMA ($658.86), offering a defined risk-reward for the patient. QNT is the $2 billion lottery ticket on the $300 trillion tokenized deposit market—but only if the token actually captures value.
What is Your move: Yield and certainty, or narrative and multiple?
“Or”
THE BIG QUESTION: If you had $1,000 today, would you allocate it to BNB or QNT? And WHY?
👇 Defend your choice. Let’s discuss fundamentals, not just hype.
Follow me for such interesting updates !
$BNB #QNT #QNT/USDT #BNBUSDT #bnb
One prints fees. The other prints bank rails. Your capital can only ride one horse—choose wisely.
BNB trades at $655.85, holding an $88.5 billion market cap with $11.2 billion in 24-hour volume. QNT sits at $161.78, a $2.01 billion cap on just $80 million volume—a 44x size gap that screams asymmetric risk.
BNB is the fortress. BSC TVL commands $5 billion, and the 2026 roadmap is a direct missile at AI-agent trading: a 100,000 TPS Layer-1 with sub-50ms pre-confirmation, testnet late 2026, mainnet early 2027. Add the quarterly auto-burn grinding supply toward 100 million, and BNB is a cash-flow-backed infrastructure monopoly. It survives on revenue, not narrative.
QNT is the wildcard. The September 2026 Clearing House mandate—building the interoperability layer for tokenized US bank deposits—sent QNT up nearly 300% in a week. But here is the kill shot: QNT’s role in that bank network remains “unclear,” and institutions can pay Quant in fiat, not QNT. Commercial success does not automatically equal token demand. QNT is a high-conviction bet on enterprise adoption and token capture—two separate hurdles.
The verdict: BNB is the institutional-grade compounder trading below its 200-day EMA ($658.86), offering a defined risk-reward for the patient. QNT is the $2 billion lottery ticket on the $300 trillion tokenized deposit market—but only if the token actually captures value.
What is Your move: Yield and certainty, or narrative and multiple?
“Or”
THE BIG QUESTION: If you had $1,000 today, would you allocate it to BNB or QNT? And WHY?
👇 Defend your choice. Let’s discuss fundamentals, not just hype.
Follow me for such interesting updates !
$BNB #QNT #QNT/USDT #BNBUSDT #bnb