NVIDIA Earnings Preview: Revenue Expected to Reach $109 Billion as AI Demand Remains Strong
NVIDIA (NASDAQ: NVDA) is scheduled to release its third-quarter fiscal 2027 earnings on November 17, 2026, after market close. Investors will focus on whether strong demand for AI infrastructure can sustain the company’s rapid growth amid rising expectations and increasing market uncertainty.
Revenue and Earnings Expectations
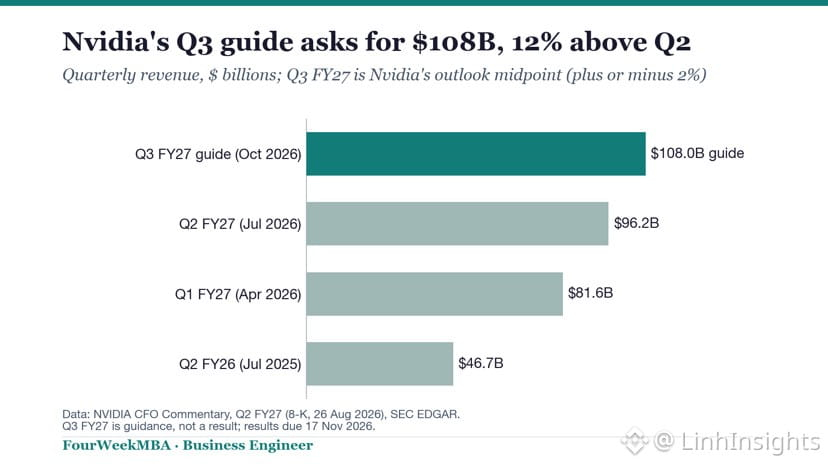
Analysts expect NVIDIA to generate approximately $109.2 billion in revenue, representing a 91.5% increase year over year. Adjusted earnings per share (EPS) are forecast at $2.48, up approximately 90.5% from the same period last year.
AI Demand and Growth Drivers
Data Center remains NVIDIA’s primary growth engine, supported by continued investment in AI infrastructure from major cloud providers. Strong demand for Blackwell Ultra and the gradual rollout of the next-generation Vera Rubin platform are expected to support future revenue growth.
Key Risks and Market Concerns
Despite strong demand, investors are monitoring several challenges, including rising component costs, potential gross margin pressure, supply constraints, and ongoing U.S. export restrictions affecting China. Recent governance-related concerns have also added uncertainty to market sentiment.
What Investors Should Watch
The upcoming earnings report will provide important signals about AI infrastructure spending, Blackwell and Vera Rubin shipments, profit margins, and NVIDIA’s forward guidance. With expectations already elevated, even strong results may not be enough unless management delivers a convincing outlook for continued growth.
#CanNvidiaEarningsEaseMarketConcerns?
$NVDA $LINK $SUI
NVIDIA (NASDAQ: NVDA) is scheduled to release its third-quarter fiscal 2027 earnings on November 17, 2026, after market close. Investors will focus on whether strong demand for AI infrastructure can sustain the company’s rapid growth amid rising expectations and increasing market uncertainty.
Revenue and Earnings Expectations
Analysts expect NVIDIA to generate approximately $109.2 billion in revenue, representing a 91.5% increase year over year. Adjusted earnings per share (EPS) are forecast at $2.48, up approximately 90.5% from the same period last year.
AI Demand and Growth Drivers
Data Center remains NVIDIA’s primary growth engine, supported by continued investment in AI infrastructure from major cloud providers. Strong demand for Blackwell Ultra and the gradual rollout of the next-generation Vera Rubin platform are expected to support future revenue growth.
Key Risks and Market Concerns
Despite strong demand, investors are monitoring several challenges, including rising component costs, potential gross margin pressure, supply constraints, and ongoing U.S. export restrictions affecting China. Recent governance-related concerns have also added uncertainty to market sentiment.
What Investors Should Watch
The upcoming earnings report will provide important signals about AI infrastructure spending, Blackwell and Vera Rubin shipments, profit margins, and NVIDIA’s forward guidance. With expectations already elevated, even strong results may not be enough unless management delivers a convincing outlook for continued growth.
#CanNvidiaEarningsEaseMarketConcerns?
$NVDA $LINK $SUI