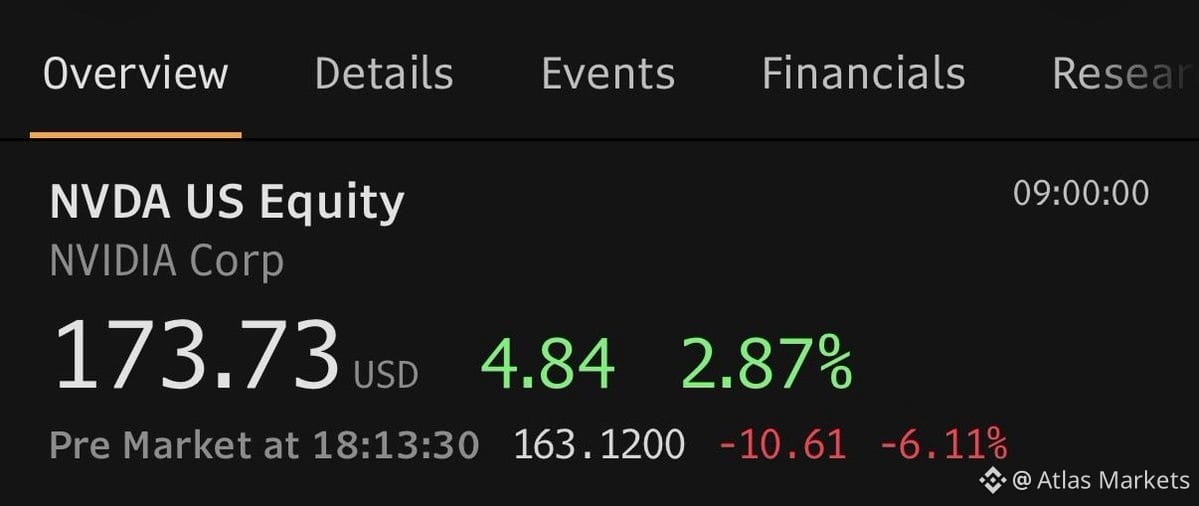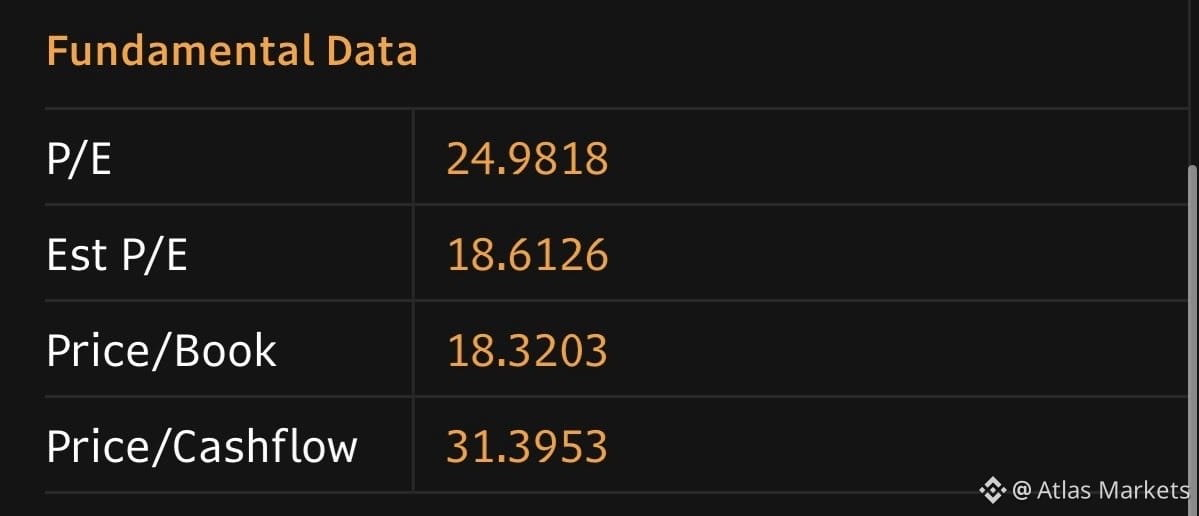
$NVDA at $160 trades 18x forward earnings if it hits the ~90% profit growth expected this fiscal year.
If next year's growth completely evaporates—zero profit growth—the forward multiple reverts to ~17x. That's still below the stock's historical average.
If the pre-crisis consensus (+60-70% growth) holds instead, you're looking at ~10x forward.
So the setup: even in a bad scenario where growth flatlines, you're paying 17x for a business that historically commanded higher multiples. The question is whether 17x is cheap enough given execution risk, macro uncertainty, and the AI infrastructure cycle potentially slowing.
This is a valuation floor argument. If you believe growth doesn't go to zero and the AI buildout continues—even at a slower pace—$NVDA at these levels starts to look asymmetric. If you think demand craters or competition accelerates faster than expected, 17x isn't a safety net.
Watch the data center revenue trajectory and customer capex guidance. That's where the real signal is.
If next year's growth completely evaporates—zero profit growth—the forward multiple reverts to ~17x. That's still below the stock's historical average.
If the pre-crisis consensus (+60-70% growth) holds instead, you're looking at ~10x forward.
So the setup: even in a bad scenario where growth flatlines, you're paying 17x for a business that historically commanded higher multiples. The question is whether 17x is cheap enough given execution risk, macro uncertainty, and the AI infrastructure cycle potentially slowing.
This is a valuation floor argument. If you believe growth doesn't go to zero and the AI buildout continues—even at a slower pace—$NVDA at these levels starts to look asymmetric. If you think demand craters or competition accelerates faster than expected, 17x isn't a safety net.
Watch the data center revenue trajectory and customer capex guidance. That's where the real signal is.