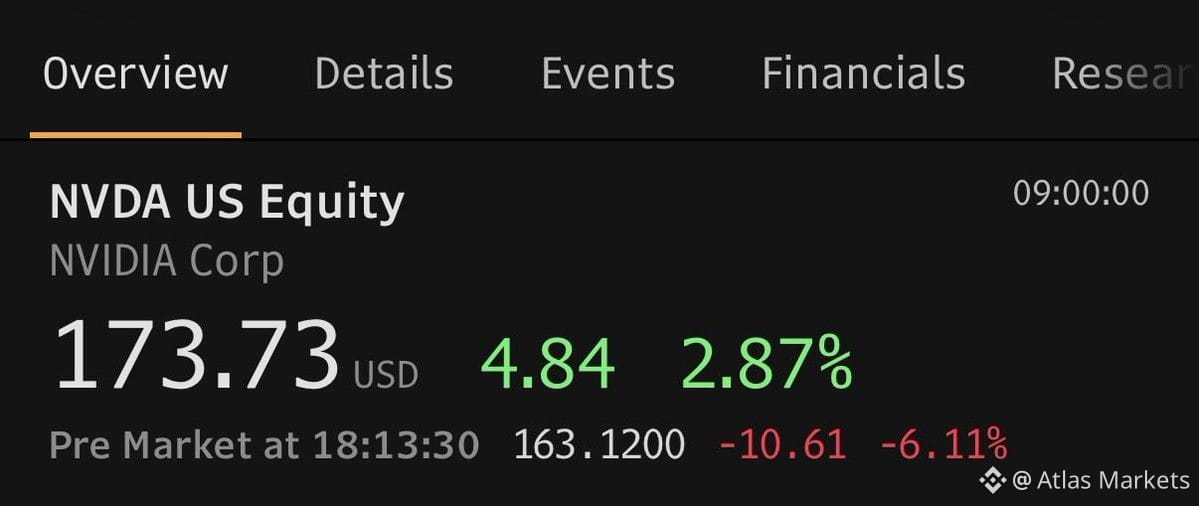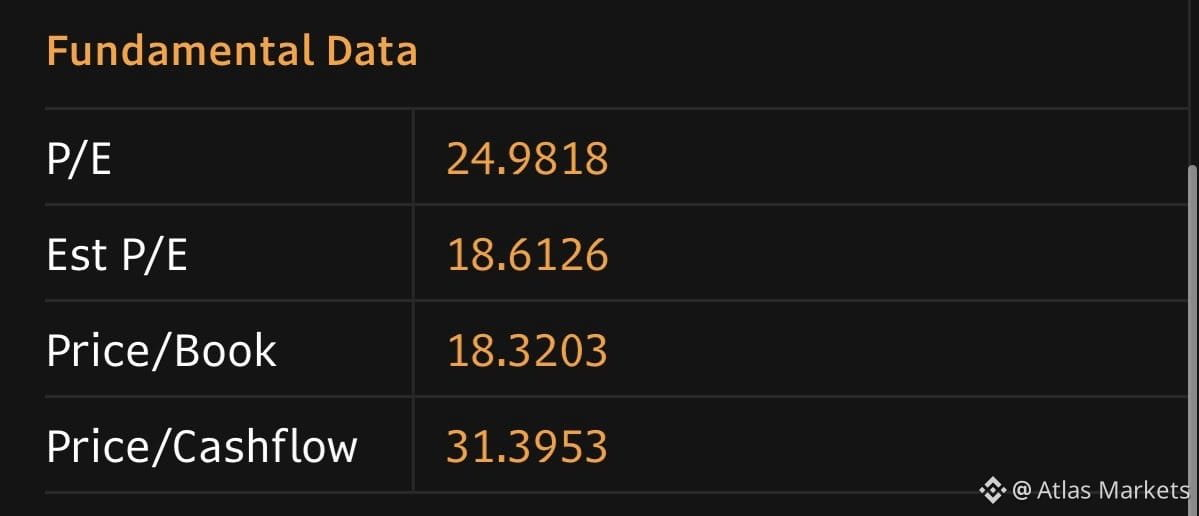
$NVDA at $160 trades at 18x forward P/E, assuming it delivers the ~90% profit growth expected this fiscal year.
If next year's growth completely evaporates—zero profit growth—the forward P/E only reverts to around 17-18x. That's still below its historical average.
For context: if the pre-crisis consensus (+60-70% growth) held, you'd be looking at a 10x forward multiple. But with growth wiped out, you're back near 17x.
The real question: is 17x cheap enough given all the macro and AI infrastructure uncertainty right now? Historically reasonable, but depends on whether you believe the growth story stabilizes or deteriorates further.
Rough math, but useful framing for where the valuation floor might sit in a bad scenario.
If next year's growth completely evaporates—zero profit growth—the forward P/E only reverts to around 17-18x. That's still below its historical average.
For context: if the pre-crisis consensus (+60-70% growth) held, you'd be looking at a 10x forward multiple. But with growth wiped out, you're back near 17x.
The real question: is 17x cheap enough given all the macro and AI infrastructure uncertainty right now? Historically reasonable, but depends on whether you believe the growth story stabilizes or deteriorates further.
Rough math, but useful framing for where the valuation floor might sit in a bad scenario.