Gold continues to attract capital. Why hasn’t Bitcoin risen in tandem?
A curious phenomenon has recently emerged in financial markets: some investors view both gold and Bitcoin as alternative assets outside the traditional financial system, yet capital flows into the two have diverged significantly.
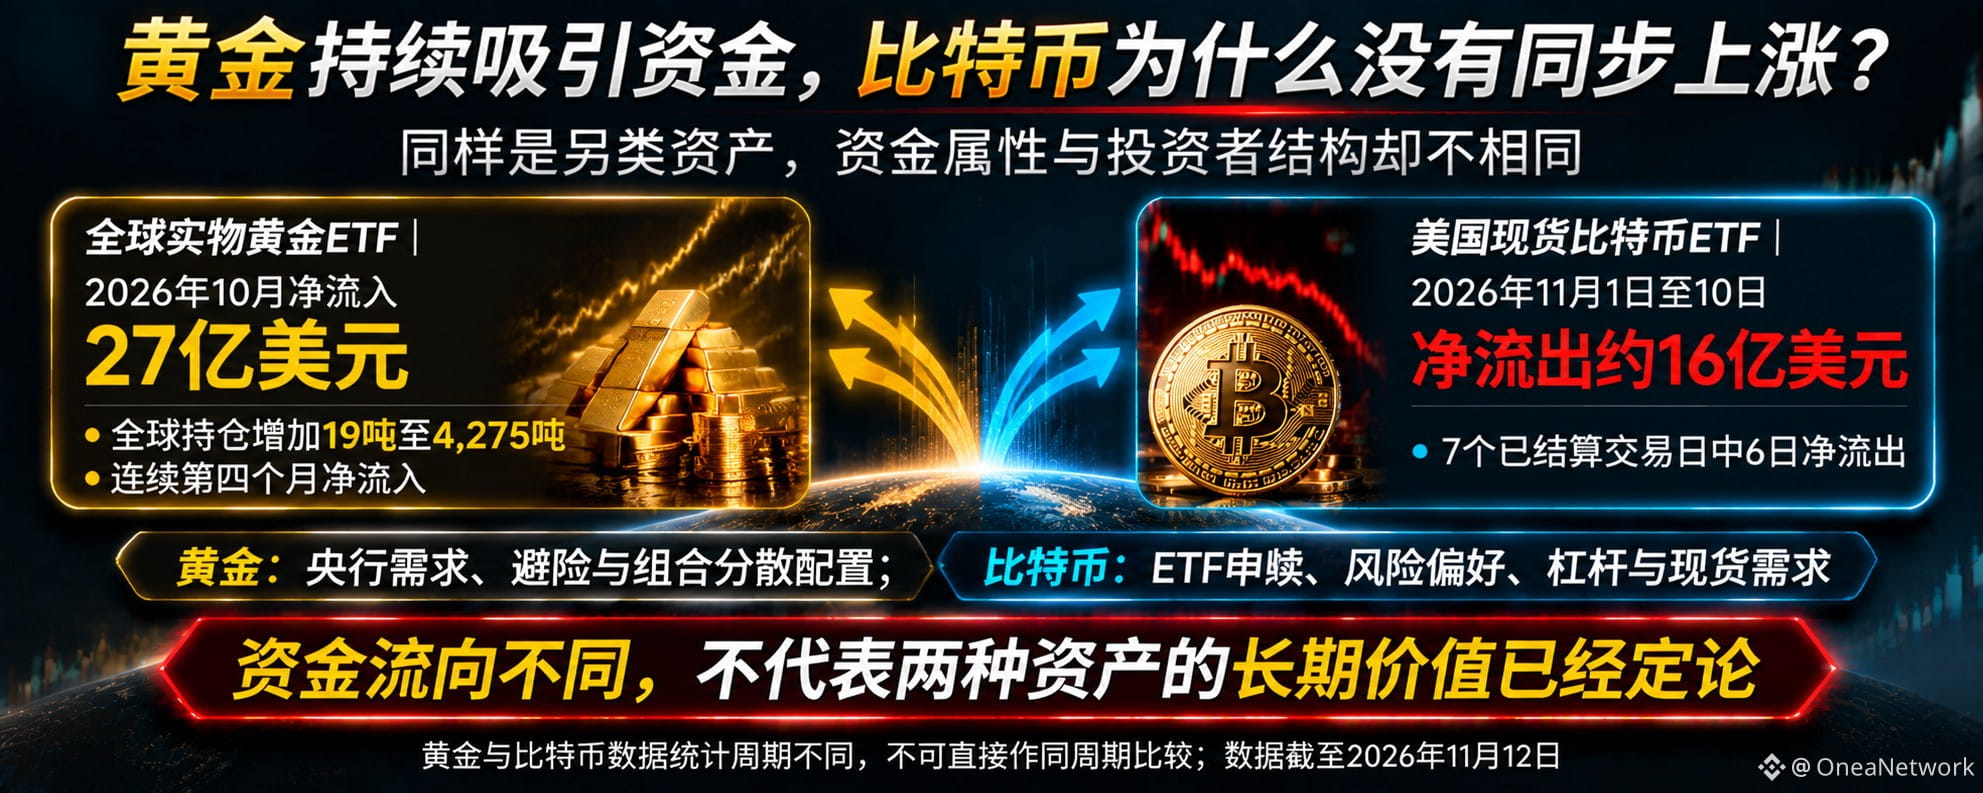
According to data released by the World Gold Council on November 5, global physically backed gold ETFs recorded net inflows of approximately $2.7 billion in October 2026, marking their fourth consecutive month of net inflows. Global gold ETF holdings increased by 19 tonnes to 4,275 tonnes, setting a new month-end record. In the first ten months of this year, gold ETFs recorded cumulative net inflows of approximately $41 billion.
By contrast, U.S. spot Bitcoin ETFs saw cumulative net outflows of approximately $1.6 billion from November 1 to 10, with net outflows on six of the seven settled trading days.
Why has this difference emerged?
First, gold has a more established role as a safe-haven and reserve asset. Central banks, long-term asset managers, and investors seeking to diversify risk may all include gold as part of their long-term allocations.
Second, Bitcoin’s investor base is more diverse. In addition to long-term holders, there is a large amount of trading capital focused on price volatility, ETF creations and redemptions, and market liquidity. As a result, short-term capital flows can fluctuate more sharply.
Third, the two assets are driven by different market dynamics. Gold is influenced by central bank demand, real interest rates, and geopolitics, while Bitcoin is also affected by ETF flows, leverage, spot demand, and liquidity within the crypto market.
It is worth noting that sustained inflows into gold ETFs do not mean that gold prices rise every day. Gold prices also underwent a significant correction in October. This is precisely why capital allocation and short-term price performance do not always move in sync.
Therefore, we should not simply assume that gold is replacing Bitcoin, or that short-term outflows from Bitcoin mean its long-term value has disappeared.
What is truly worth examining is why different investors choose different assets, and whether those choices are beginning to form a long-term trend.
Which do you think is more likely to attract long-term institutional allocations over the next three years: gold or Bitcoin?
A curious phenomenon has recently emerged in financial markets: some investors view both gold and Bitcoin as alternative assets outside the traditional financial system, yet capital flows into the two have diverged significantly.
According to data released by the World Gold Council on November 5, global physically backed gold ETFs recorded net inflows of approximately $2.7 billion in October 2026, marking their fourth consecutive month of net inflows. Global gold ETF holdings increased by 19 tonnes to 4,275 tonnes, setting a new month-end record. In the first ten months of this year, gold ETFs recorded cumulative net inflows of approximately $41 billion.
By contrast, U.S. spot Bitcoin ETFs saw cumulative net outflows of approximately $1.6 billion from November 1 to 10, with net outflows on six of the seven settled trading days.
Why has this difference emerged?
First, gold has a more established role as a safe-haven and reserve asset. Central banks, long-term asset managers, and investors seeking to diversify risk may all include gold as part of their long-term allocations.
Second, Bitcoin’s investor base is more diverse. In addition to long-term holders, there is a large amount of trading capital focused on price volatility, ETF creations and redemptions, and market liquidity. As a result, short-term capital flows can fluctuate more sharply.
Third, the two assets are driven by different market dynamics. Gold is influenced by central bank demand, real interest rates, and geopolitics, while Bitcoin is also affected by ETF flows, leverage, spot demand, and liquidity within the crypto market.
It is worth noting that sustained inflows into gold ETFs do not mean that gold prices rise every day. Gold prices also underwent a significant correction in October. This is precisely why capital allocation and short-term price performance do not always move in sync.
Therefore, we should not simply assume that gold is replacing Bitcoin, or that short-term outflows from Bitcoin mean its long-term value has disappeared.
What is truly worth examining is why different investors choose different assets, and whether those choices are beginning to form a long-term trend.
Which do you think is more likely to attract long-term institutional allocations over the next three years: gold or Bitcoin?