


Author: Bitget
Top News Picks
AI Investing | CoreWeave Eases Return Concerns, Tech Stocks Lead Gains
CoreWeave rose 24.71%, driving a rebound in AI cloud and semiconductor stocks. Its previously announced third-quarter revenue of $3.661 billion, raised full-year revenue guidance, and target of achieving adjusted profitability in the first half of 2028 have eased market concerns about returns on expansion.
At the heart of this rally is investors' reassessment of whether investment in infrastructure can translate into revenue and profits. Revenue delivery offers evidence, but the profitability target remains forward-looking. Going forward, execution, financing, and cash flow will all need to remain on track.
Energy | Iran takes a hard line on nuclear material; oil prices rebound from lows
Brent January 2027 futures rose 1.39% to settle at $92.76 a barrel; WTI December futures gained 0.57% to $86.53 a barrel. Iran said it would not allow enriched nuclear material to leave the country, dampening expectations for a swift easing of the conflict.
Crude oil is once again pricing in some supply risk premium. Even if diplomatic rhetoric improves, the resumption of shipping still depends on security, insurance, and shipowners’ willingness. Negotiation expectations therefore should not be equated directly with a normalization of supply.
Crypto Treasuries | MSCI to exclude Strategy, putting its financing model to a new test
MSCI will remove Strategy and other companies from the relevant global indexes on December 1, citing characteristics that more closely resemble an investment fund or non-operating company. Strategy fell about 2.5% after hours, as markets focused on passive fund rebalancing and future financing terms.
The immediate impact is on the stock: index-tracking funds may sell the company’s shares. Only if this further affects its equity premium and financing capacity could it weaken the company’s ability to increase its BTC holdings in the future; this does not mean the company has already sold any coins.
Market Review
Commodities and Foreign Exchange Performance
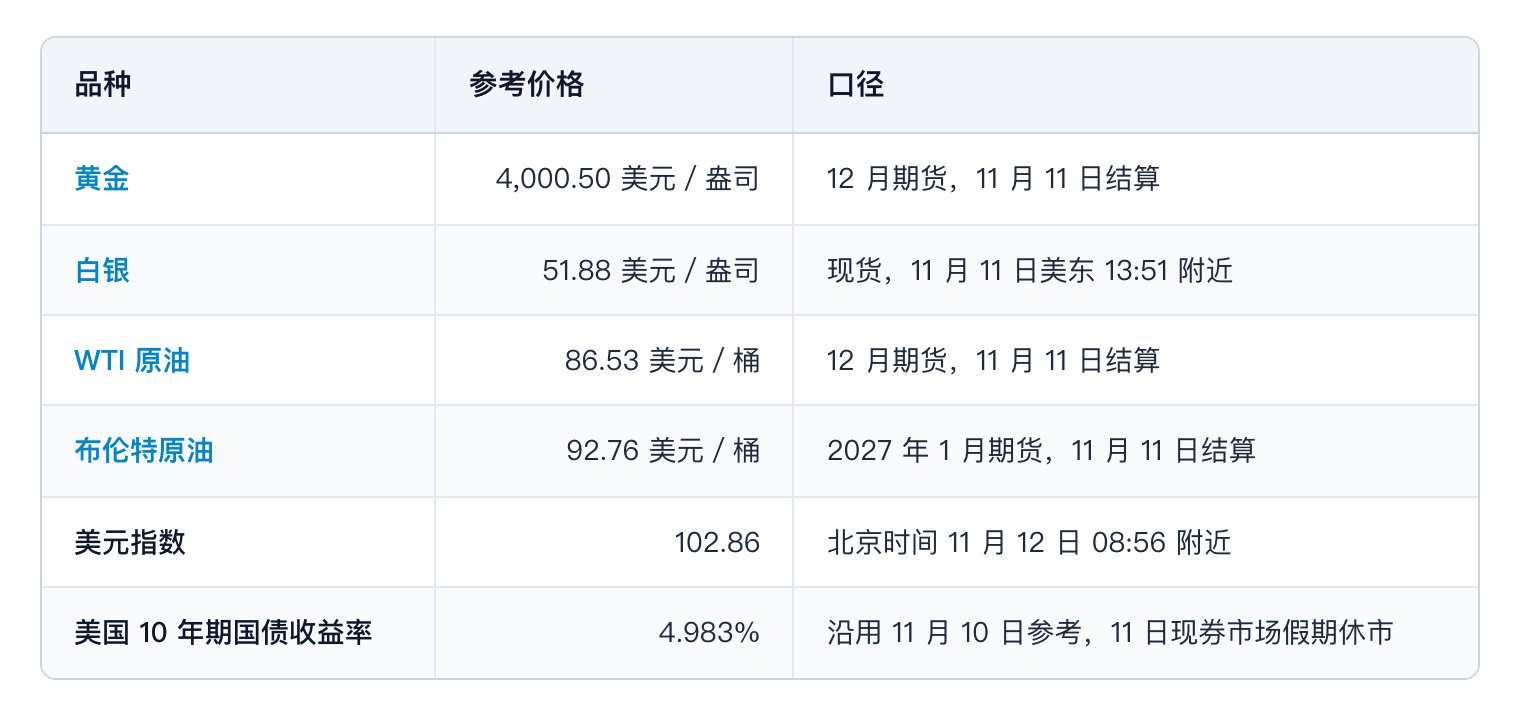
December gold futures fell about 0.7%, while spot gold briefly dropped below $4,000. A strong dollar and expectations of higher interest rates continued to weigh on precious metals. The U.S. stock rebound was driven mainly by improving corporate and sector expectations; it does not mean interest-rate pressures have disappeared.
Cryptocurrency Performance
BTC was at 73,881.53 USDT, up 0.58% over 24 hours; ETH was at 2,056.20 USDT, up 0.50%. The total crypto market capitalization was about $2.47 trillion, down 2.25% over 24 hours, with 24-hour trading volume of about $64.139 billion. Aggregate data was last updated separately at 09:04 Beijing time.
BTC/ETH liquidation zone watch: No verifiable up-to-date liquidation zones were available this time, so ranges, distances, and nearby liquidation assessments are not provided.
Institutional Cost Basis | BTC: In its latest disclosure on November 9, Strategy said it held 850,364 BTC as of November 8, at an overall average cost of $75,456, including fees. BTC is about 2.18% below this cost basis, indicating an unrealized loss by this measure. This is the cost basis of the overall holdings, not the average price of the most recent purchase.
Market in a sentence: BTC is still hovering around $74,000 and has yet to match the recovery in AI stocks. Watch whether it can reclaim $75,000 and approach institutional cost bases, while also monitoring financing conditions for treasury companies. Share selling prompted by index exclusions should not be directly equated with spot BTC selling pressure.
Major U.S. Stock Index Performance
Market Moves Explained
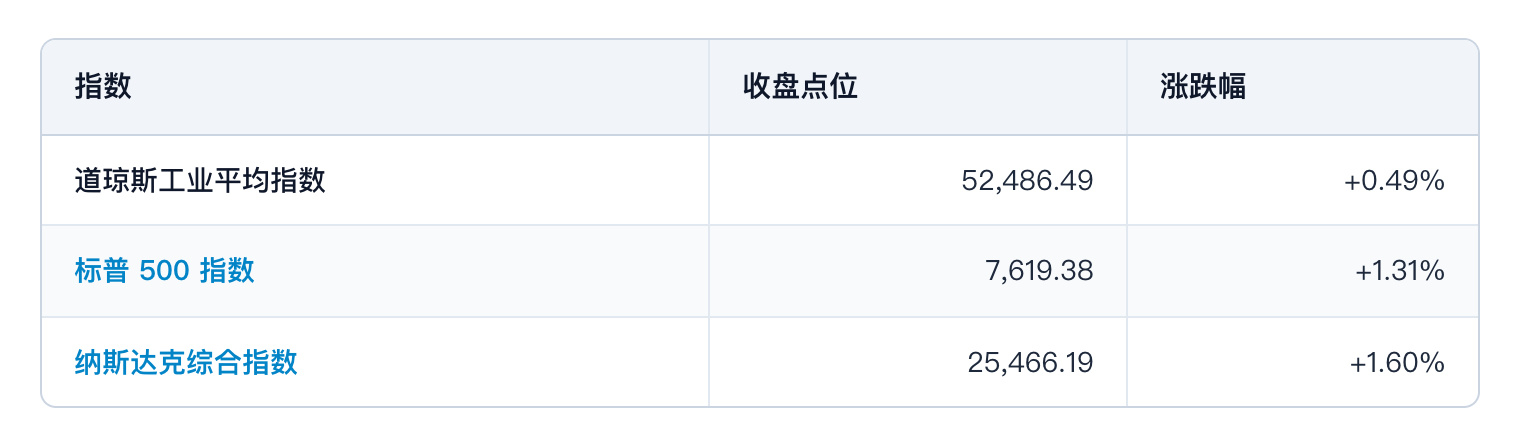
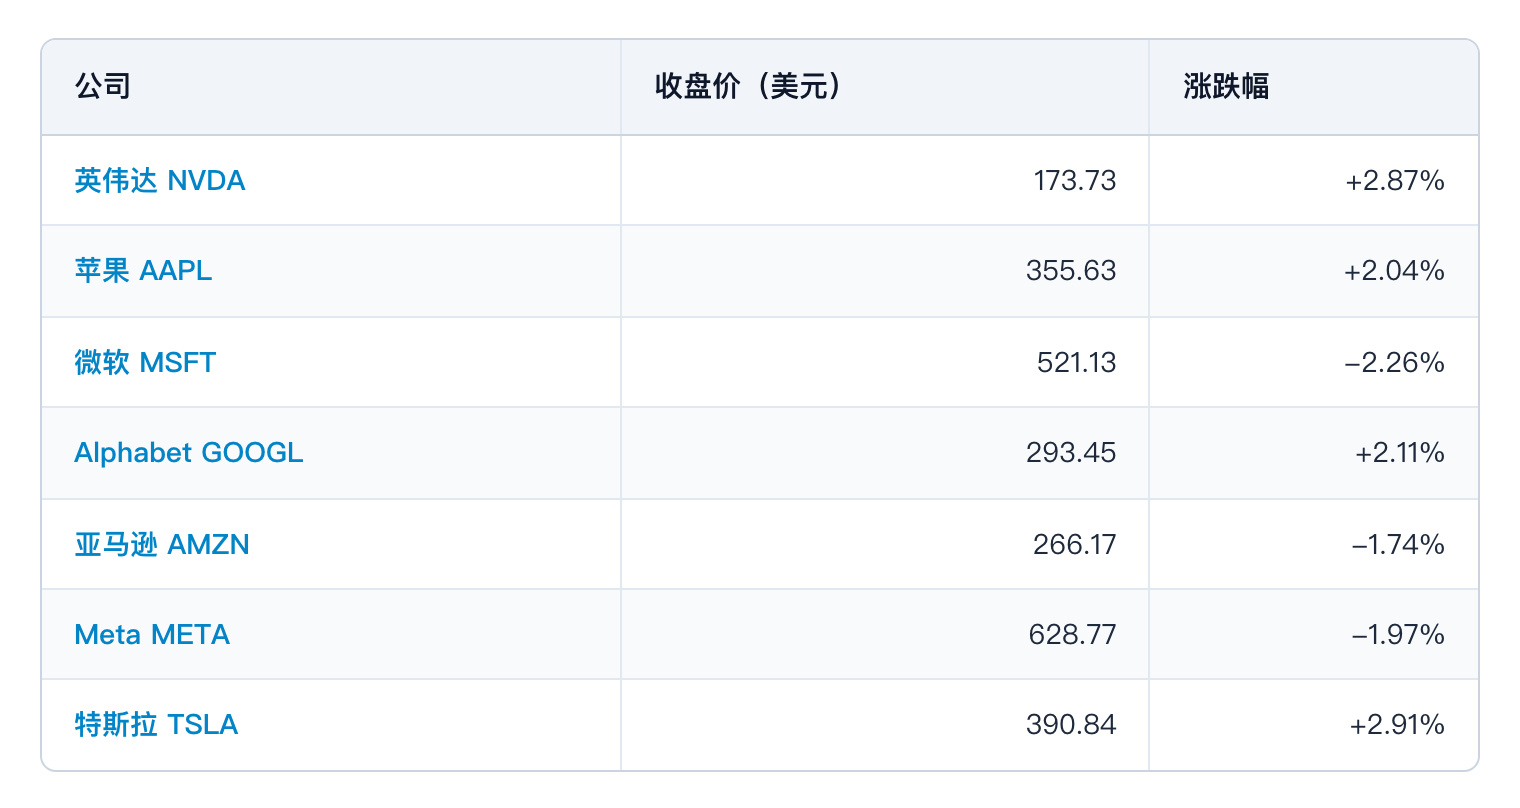
Market performance: The Nasdaq led gains, with CoreWeave jumping 24.71%, Broadcom rising 3.99%, and NVIDIA gaining 2.87% in regular trading. Four of the Magnificent Seven rose and three fell; Microsoft, Amazon, and Meta declined, so the rebound did not extend to all major-weight stocks.
Driver 1: A clearer path to profitability is lifting AI valuations. CoreWeave’s revenue delivery and profitability target have prompted the market to reassess the previously pessimistic pricing of returns on AI buildout, helping related cloud and chip stocks rebound.
Driver 2: Sector tailwinds have temporarily outweighed interest-rate constraints. This rally was driven by company news, not weaker inflation data or falling rates. Bond markets were closed for the holiday, so watch whether yields continue to weigh on valuations when trading resumes.
Driver 3: Corporate governance risks can still interrupt the rebound. NVIDIA fell again after hours following media reports that its board was considering a management change. The regular-session gain and after-hours pressure occurred in different trading periods, and any management change remains subject to formal confirmation.
Magnificent Seven Performance
Sector Moves to Watch
AI Cloud and Chips: CoreWeave and Broadcom led gains as the market reassessed when investment in computing capacity will translate into revenue. Next, watch whether Nebius’s results provide evidence in the same direction, rather than judging the entire sector on one company’s earnings alone.
Crypto Treasuries: Strategy faces a change in index eligibility, shifting attention beyond Bitcoin prices to capital markets financing. The company’s stock and BTC are linked through risk transmission, but they should not be conflated as the same flow of funds.
Key U.S. Stocks: Analysis
CoreWeave CRWV | Earnings expectations recover, but financing remains a hurdle
Event overview: Shares rose 24.71% to $60.77. The company reported third-quarter revenue of $3.661 billion, full-year revenue guidance of $13.0 billion to $13.3 billion, and a target of achieving adjusted profitability in the first half of 2028.
Market interpretation: Demand and revenue delivery have eased concerns about capital-intensive expansion, but quarterly net interest expense of $846 million remained above operating profit of $207 million. The share-price recovery reflects improved expectations, not the resolution of financial pressures.
Investment takeaway: Track whether customer prepayments, project delivery, and financing costs remain aligned, and whether the profitability target translates into actual profits and cash returns quarter by quarter.
NVIDIA NVDA | Intraday recovery and after-hours risks coexist
Event overview: Shares rose 2.87% in regular trading to $173.73, then came under pressure after hours following media reports that the board was considering replacing the CEO. This potential management change should not be treated as confirmed by the company.
Market interpretation: Improving expectations for AI demand support sector valuations, while uncertainty around the board and management affects the company’s execution and customer confidence. Both factors are in play.
Investment takeaway: Watch for formal board announcements, management arrangements, and progress in customer partnerships. On November 8, the board expressed support for Jensen Huang and his team and launched an independent investigation. Update the assessment based on any subsequent formal disclosures.
Strategy MSTR | Index eligibility changes; focus first on shares and financing
Event overview: MSCI announced that the relevant exclusions will take effect on December 1, and Strategy fell about 2.5% after hours. Attention is on the company’s sources of passive capital and future equity financing terms.
Market interpretation: If the stock’s valuation premium narrows, issuing shares to buy BTC may become less efficient. Index rebalancing changes the supply and demand for shares; it does not mean the company has sold BTC.
Investment takeaway: Track the actual scale of index rebalancing, decisions by other index providers, and financing announcements. Distinguish among passive fund share sales, company financing, and company BTC purchases.
Market and Project Updates
Treasury company classifications are becoming stricter. Metaplanet is also on MSCI’s latest exclusion list, indicating that index eligibility risk is not limited to a single company holding BTC.
Nebius reports earnings next. The company is scheduled to release third-quarter results before the U.S. market opens on November 12, with a conference call at 21:00 Beijing time. Key areas to watch are order-to-revenue conversion, computing capacity delivery, and financing.
Network and equipment supply chains face a test. Cisco and Applied Materials will report earnings after the U.S. market closes on November 12. Both conference calls are scheduled for 05:30 Beijing time on November 13, offering additional clues on network demand and equipment investment, respectively.
Today’s Market Calendar
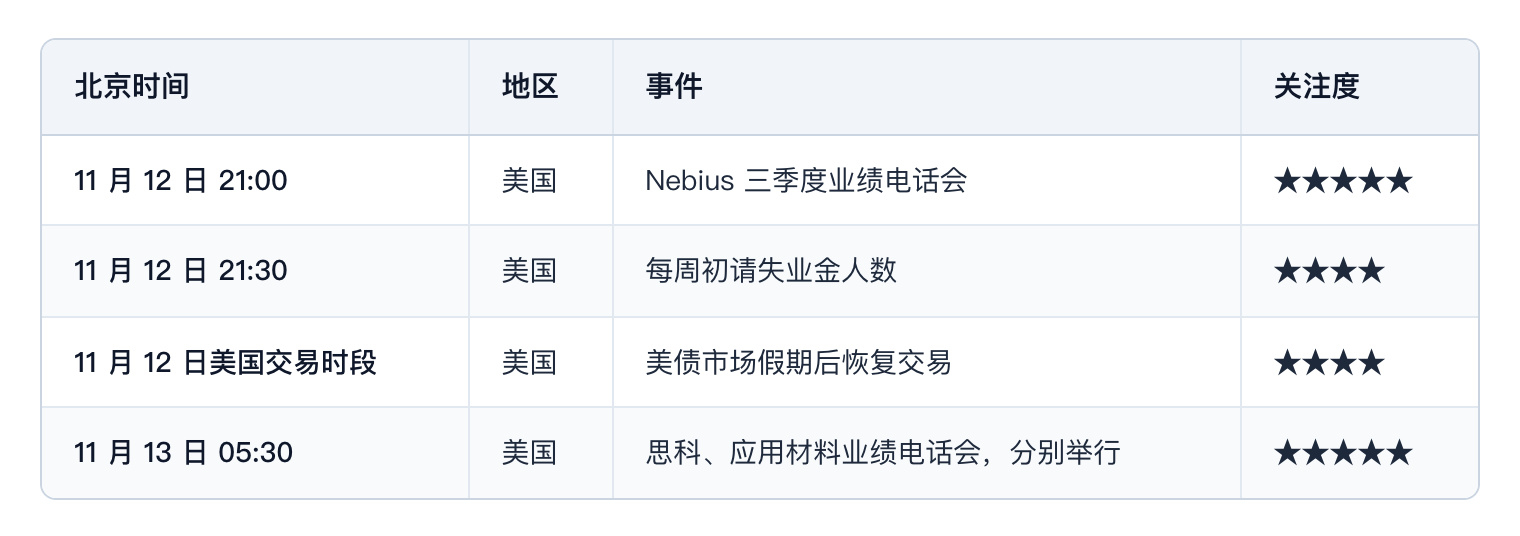
Key events to watch: Today, monitor two fronts: whether Nebius extends evidence of AI revenue realization, and whether repricing in employment and bond markets raises financing costs. NVIDIA’s after-hours news is also an important factor ahead of the market open.
Institutional view: UBS analyst Giovanni Staunovo noted on November 11 that fading expectations for a swift easing of the conflict are supporting oil prices. For asset pricing, a rebound in the energy risk premium could limit improvements in inflation expectations.
This article is for market information only and does not constitute investment advice.
Disclaimer: All content in this article represents the author’s views only and is not affiliated with this platform. Users should not rely on this article as a basis for investment decisions.