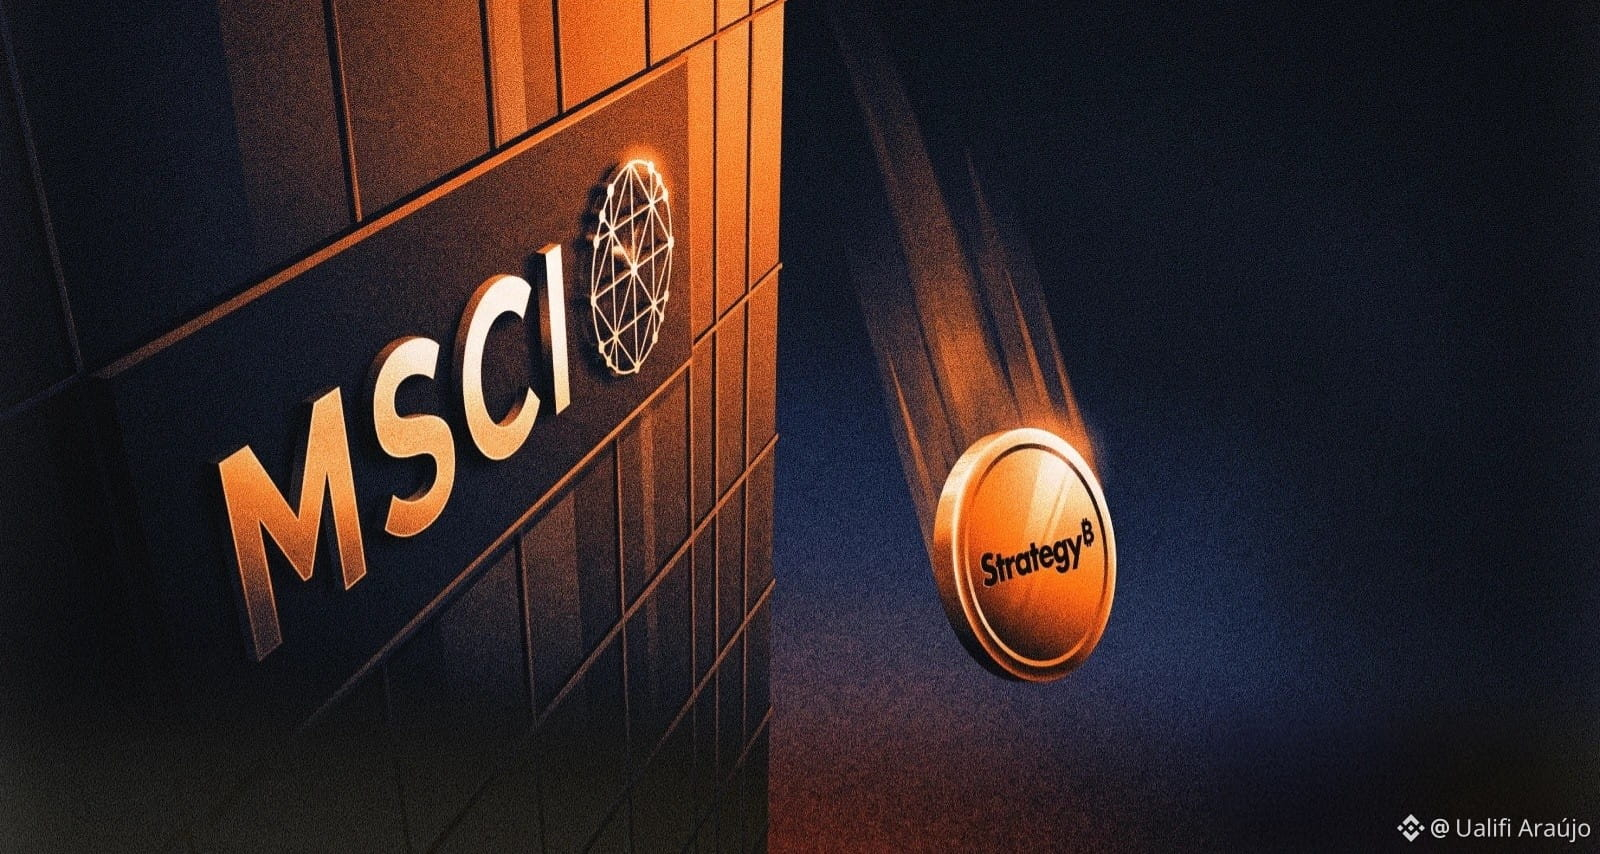

Strategy’s removal from the MSCI indexes has been confirmed. This is a flow event, not an event related to Bitcoin fundamentals.
The rules were set on October 15. Since then, the market has had time to adjust expectations. The publication of the final list and its implementation at the end of the month are the bureaucratic conclusion of something that was already on the radar. That’s why much of the price impact on MSTR and its correlation with #BTC has probably already been absorbed.
The figure being discussed—around $2.8 billion in forced selling by funds that track MSCI—is real in the short term for the stock. Passive funds don’t get to choose: if a company is removed from the index, they sell its shares. This creates selling pressure on MSTR. It does not, by itself, require Strategy to sell ANY BTC.
The distinction matters, but I haven’t seen any analyst address it. Over the past few months, Strategy has shown that it can adjust its approach to diluting common shareholders to raise capital at scale without having to liquidate BTC to cover obligations. As long as the market continues to treat MSTR as leveraged exposure to BTC (and there is demand for that), the company retains the ability to issue securities. This significantly reduces the risk of Strategy itself being forced to sell BTC in the current scenario.
From Bitcoin’s perspective, the effect is even more limited. Strategy is the largest corporate holder, but the asset’s price is determined by a much broader set of factors: spot ETFs, institutional flows, holdings by other companies and governments, mining, and self-custody demand. Removing a single company from an index, however relevant it may be in the treasury universe, does not change the total supply or the asset’s long-term thesis.
In short: index and stock-flow noise. This is not the end of Strategy’s model, nor a structural blow to BTC. Those who believe in Bitcoin continue to have direct ownership of the asset as the cleanest exposure. The rest is the market price reacting to index classification rules.
Ignore the noise!
The rules were set on October 15. Since then, the market has had time to adjust expectations. The publication of the final list and its implementation at the end of the month are the bureaucratic conclusion of something that was already on the radar. That’s why much of the price impact on MSTR and its correlation with #BTC has probably already been absorbed.
The figure being discussed—around $2.8 billion in forced selling by funds that track MSCI—is real in the short term for the stock. Passive funds don’t get to choose: if a company is removed from the index, they sell its shares. This creates selling pressure on MSTR. It does not, by itself, require Strategy to sell ANY BTC.
The distinction matters, but I haven’t seen any analyst address it. Over the past few months, Strategy has shown that it can adjust its approach to diluting common shareholders to raise capital at scale without having to liquidate BTC to cover obligations. As long as the market continues to treat MSTR as leveraged exposure to BTC (and there is demand for that), the company retains the ability to issue securities. This significantly reduces the risk of Strategy itself being forced to sell BTC in the current scenario.
From Bitcoin’s perspective, the effect is even more limited. Strategy is the largest corporate holder, but the asset’s price is determined by a much broader set of factors: spot ETFs, institutional flows, holdings by other companies and governments, mining, and self-custody demand. Removing a single company from an index, however relevant it may be in the treasury universe, does not change the total supply or the asset’s long-term thesis.
In short: index and stock-flow noise. This is not the end of Strategy’s model, nor a structural blow to BTC. Those who believe in Bitcoin continue to have direct ownership of the asset as the cleanest exposure. The rest is the market price reacting to index classification rules.
Ignore the noise!