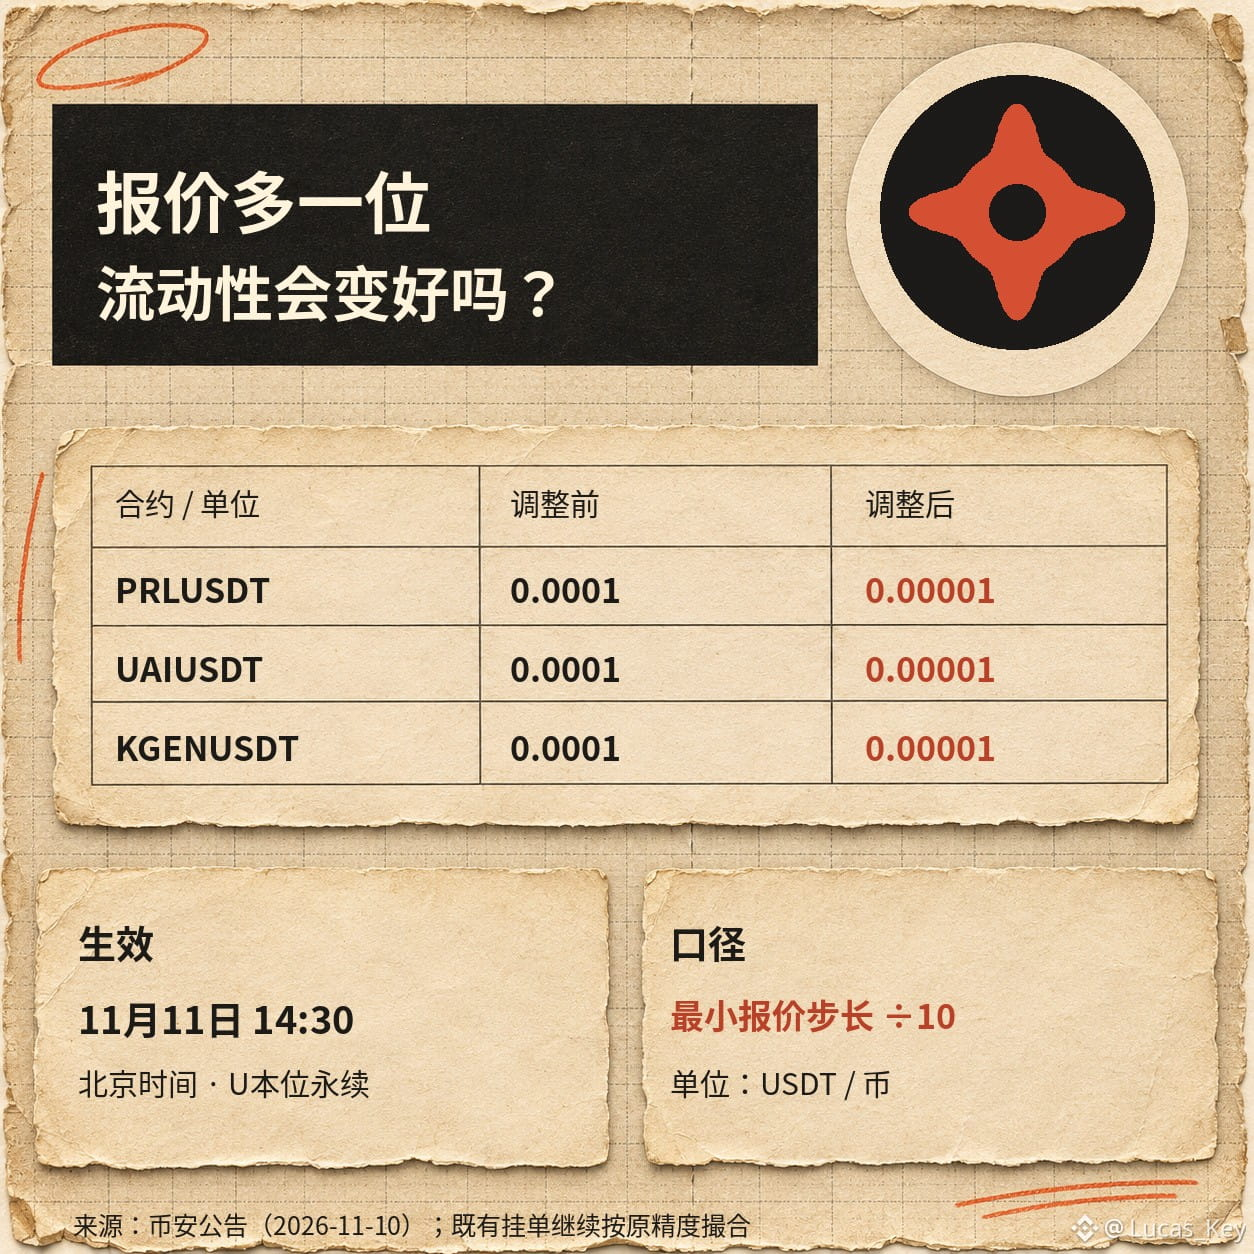
The perpetual contract quote for $PRL gained an extra decimal place today. According to a Binance announcement, starting at 14:30 Beijing time on November 11, the minimum price increments for PRLUSDT, UAIUSDT ($UAI ), and KGENUSDT ($KGEN ) will all be reduced from 0.0001 to 0.00001 USDT, making the tick size ten times smaller. Existing limit orders will continue to be matched at their original price precision; this change affects the price tick, not the contract face value or spot price.
There is a clear rationale for the adjustment: when buyers and sellers are willing to quote closer to each other, finer increments let them adjust their prices in smaller steps. Previously, adjacent price levels had to be at least 0.0001 USDT apart; now they can be just 0.00001 USDT apart. For lower-priced contracts, the theoretical minimum spread is indeed narrower.
But don’t equate “quoting more precisely” with “increased liquidity.” Market-making orders may be split across more price levels than before, making the order book look denser around the best price while leaving less available to trade. If trading activity and capital don’t increase, slippage may not improve. I’m more interested in comparing bid-ask spreads, depth across the first few levels, and actual execution slippage over the same periods and at the same notional amount before and after the change, rather than simply looking at the extra decimal places in the order book.
These three contracts are part of the same rule adjustment, but comparisons should also account for differences in token prices and trading activity. A rule change is not a directional signal; futures trading carries liquidation risk, and this article does not constitute trading advice.
There is a clear rationale for the adjustment: when buyers and sellers are willing to quote closer to each other, finer increments let them adjust their prices in smaller steps. Previously, adjacent price levels had to be at least 0.0001 USDT apart; now they can be just 0.00001 USDT apart. For lower-priced contracts, the theoretical minimum spread is indeed narrower.
But don’t equate “quoting more precisely” with “increased liquidity.” Market-making orders may be split across more price levels than before, making the order book look denser around the best price while leaving less available to trade. If trading activity and capital don’t increase, slippage may not improve. I’m more interested in comparing bid-ask spreads, depth across the first few levels, and actual execution slippage over the same periods and at the same notional amount before and after the change, rather than simply looking at the extra decimal places in the order book.
These three contracts are part of the same rule adjustment, but comparisons should also account for differences in token prices and trading activity. A rule change is not a directional signal; futures trading carries liquidation risk, and this article does not constitute trading advice.