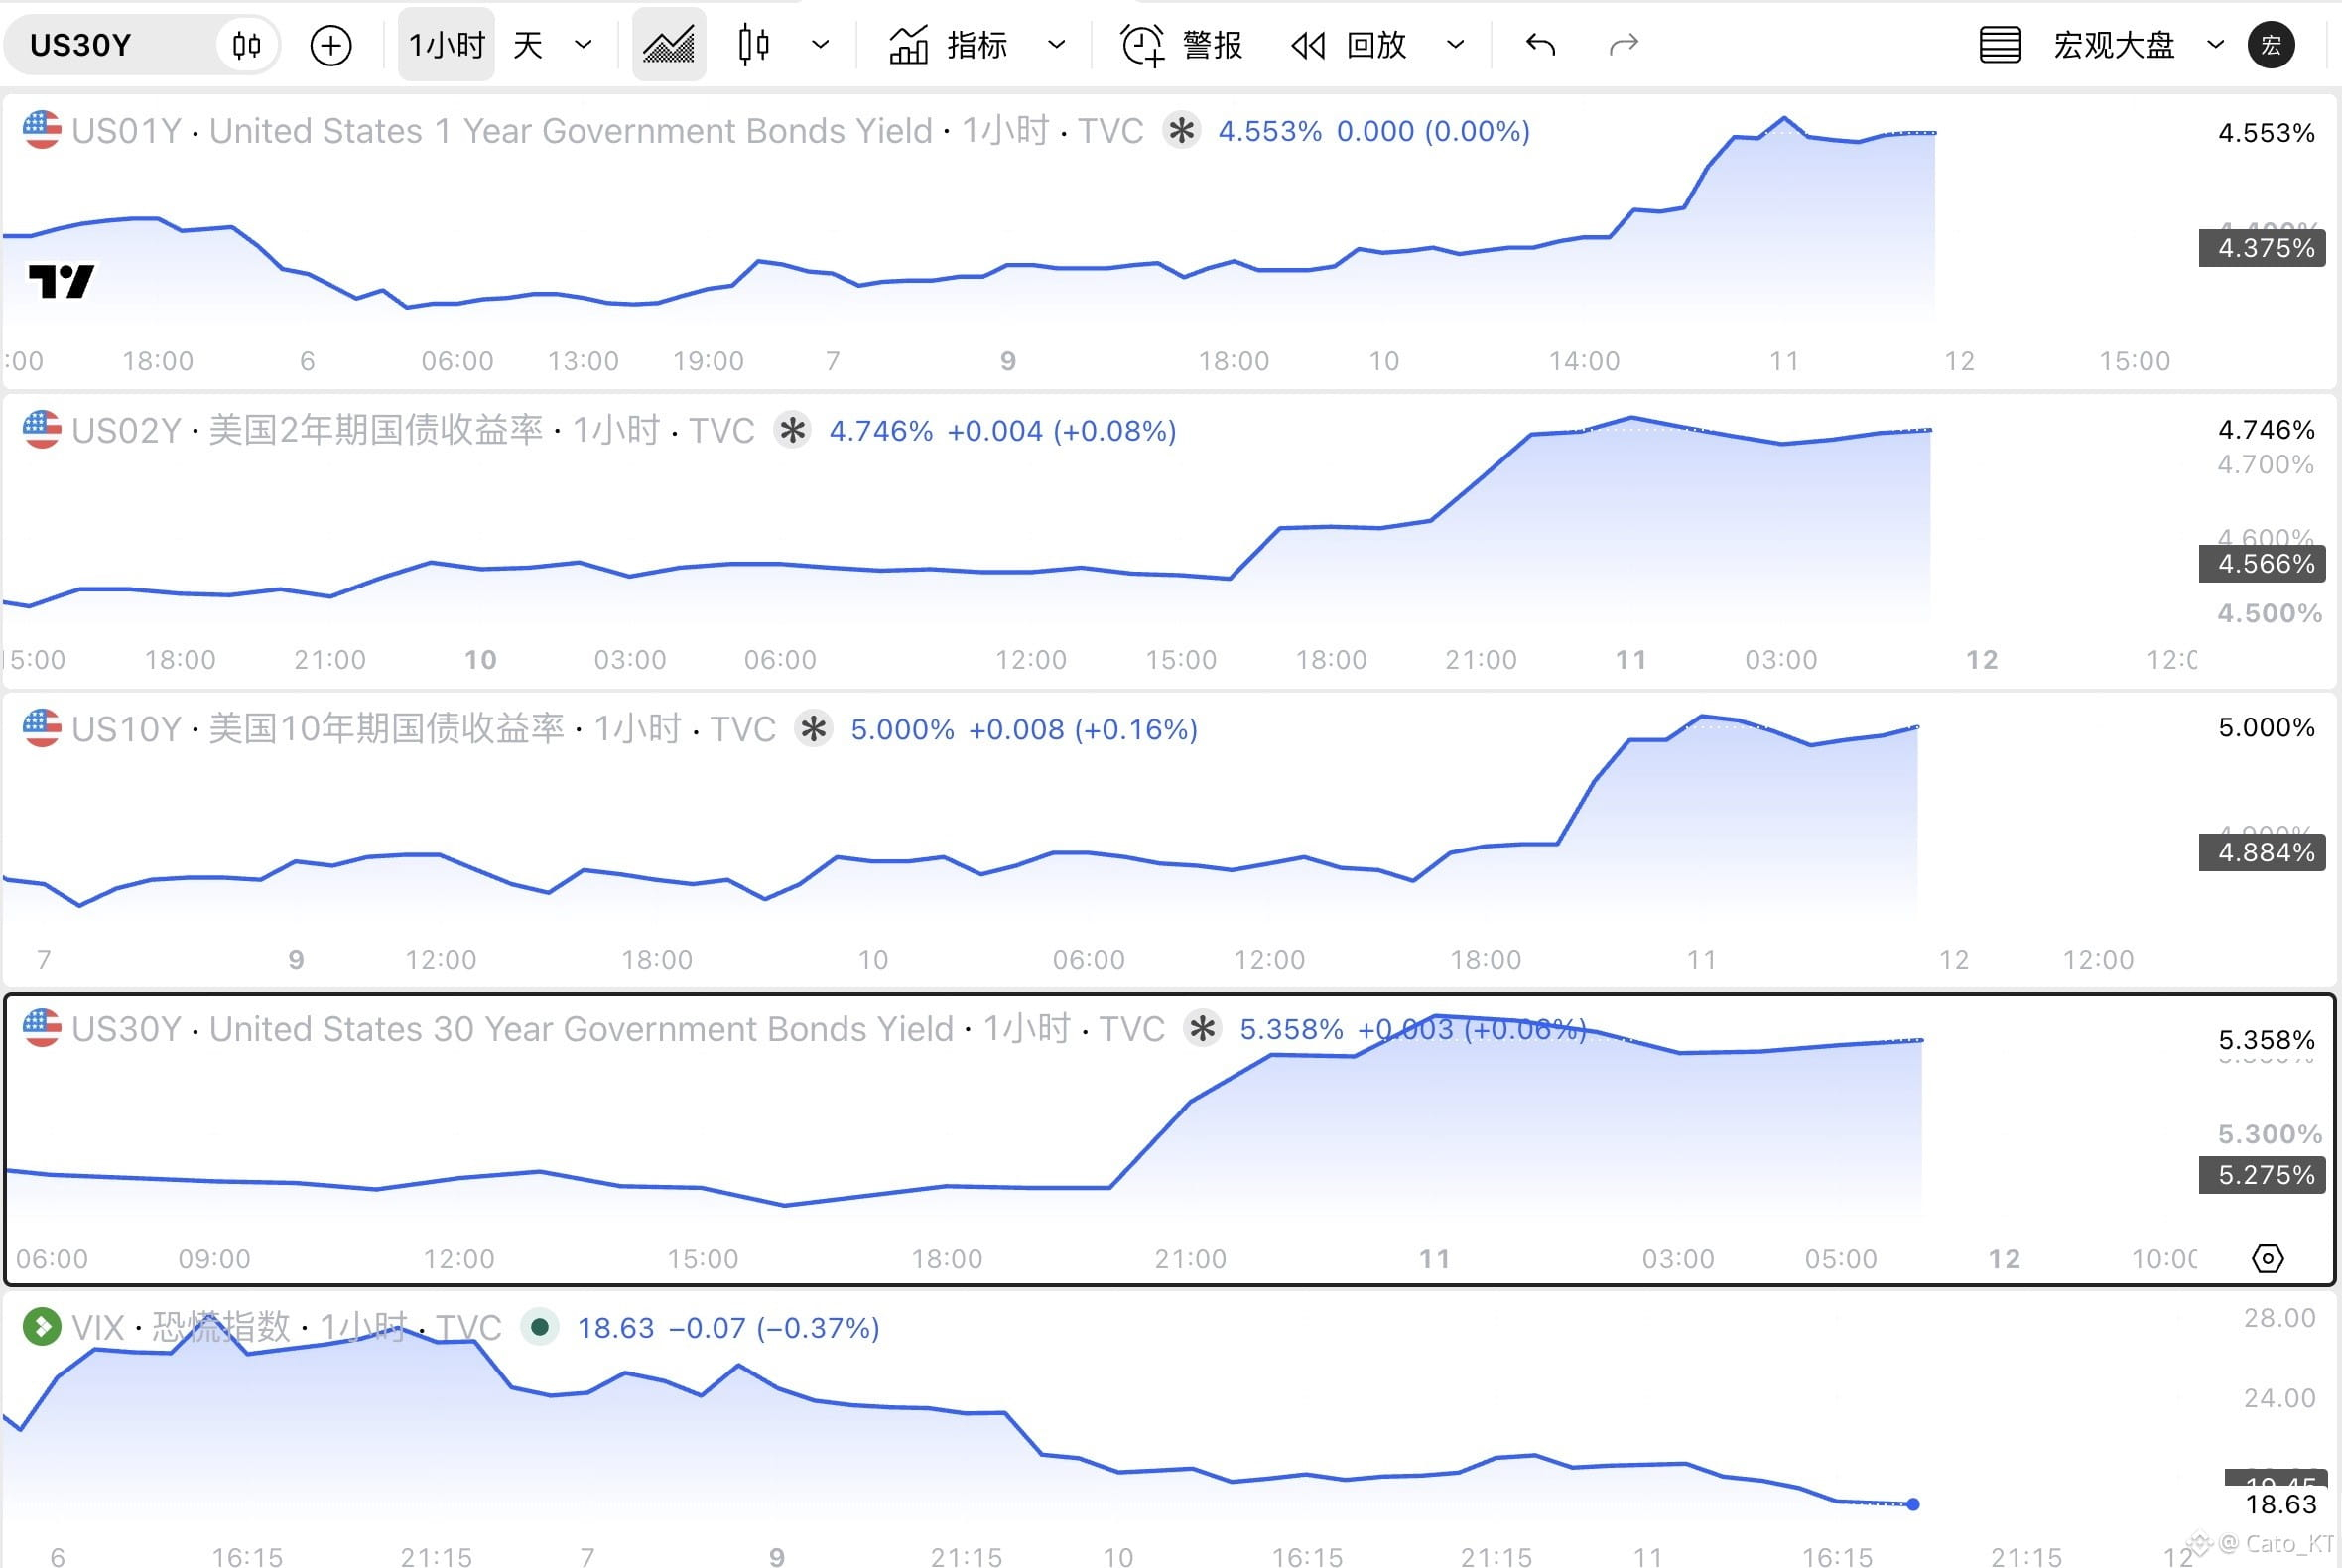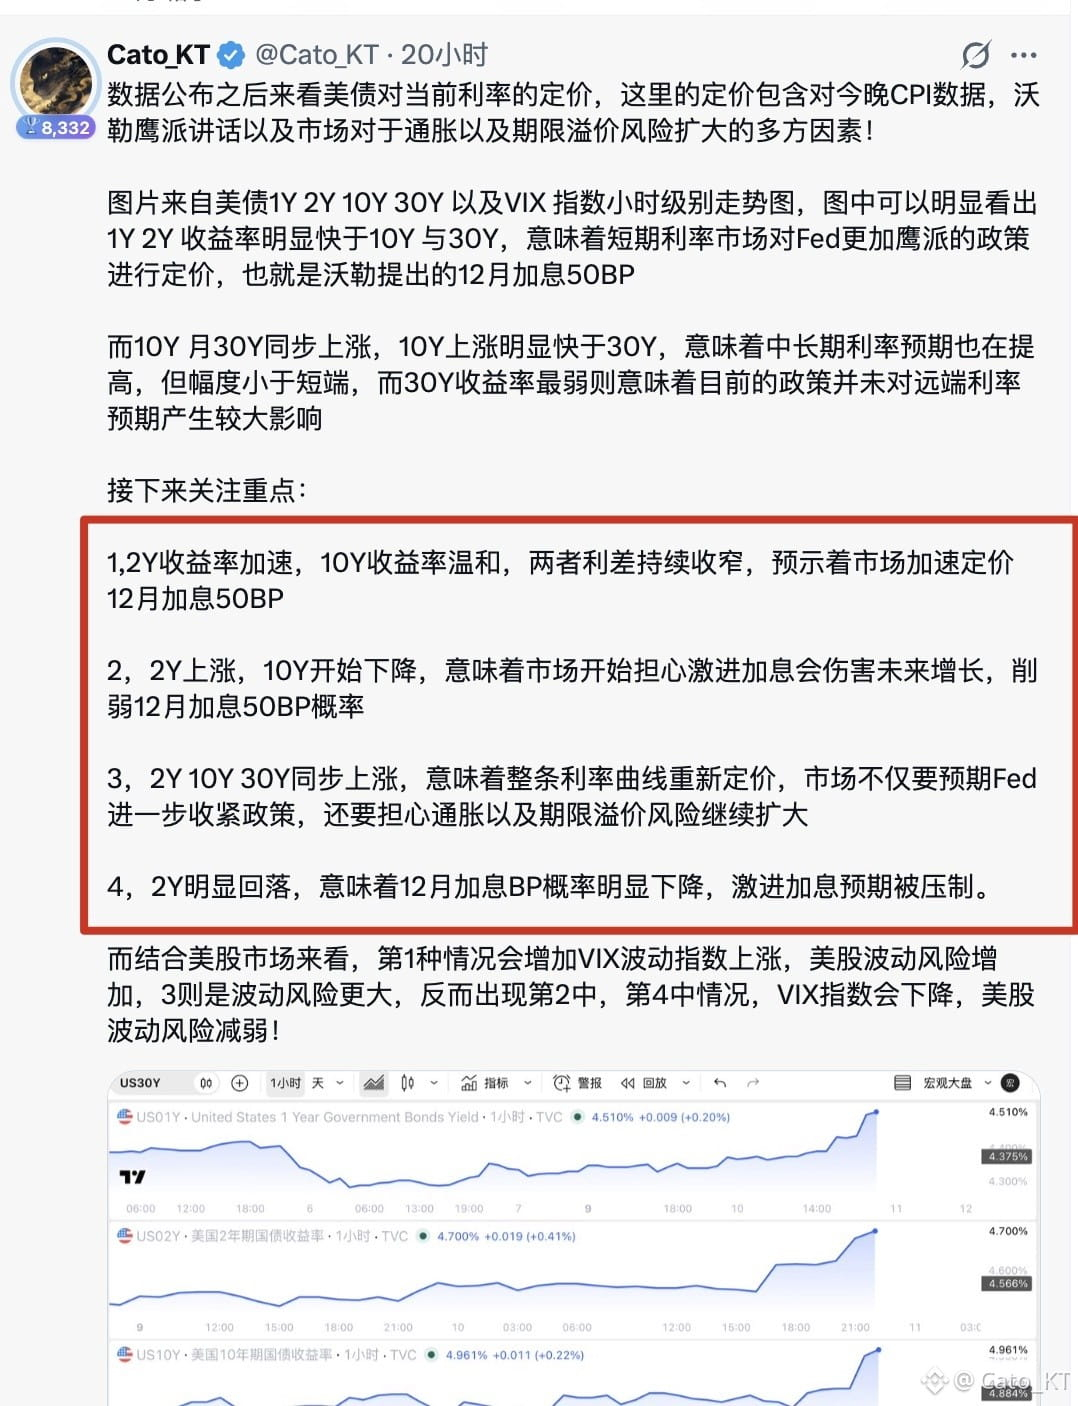
To assess how financial markets are pricing in future interest rate expectations, we still need to look at the trend in Treasury yields. Using the 1-hour timeframe as a reference, 2Y and 10Y yields have tended to flatten since the U.S. market opened.
This means that short-term pricing expectations for a 50 bp rate hike in December or consecutive rate hikes in January 2027 have initially run their course. U.S. stock indices have also risen in premarket trading,
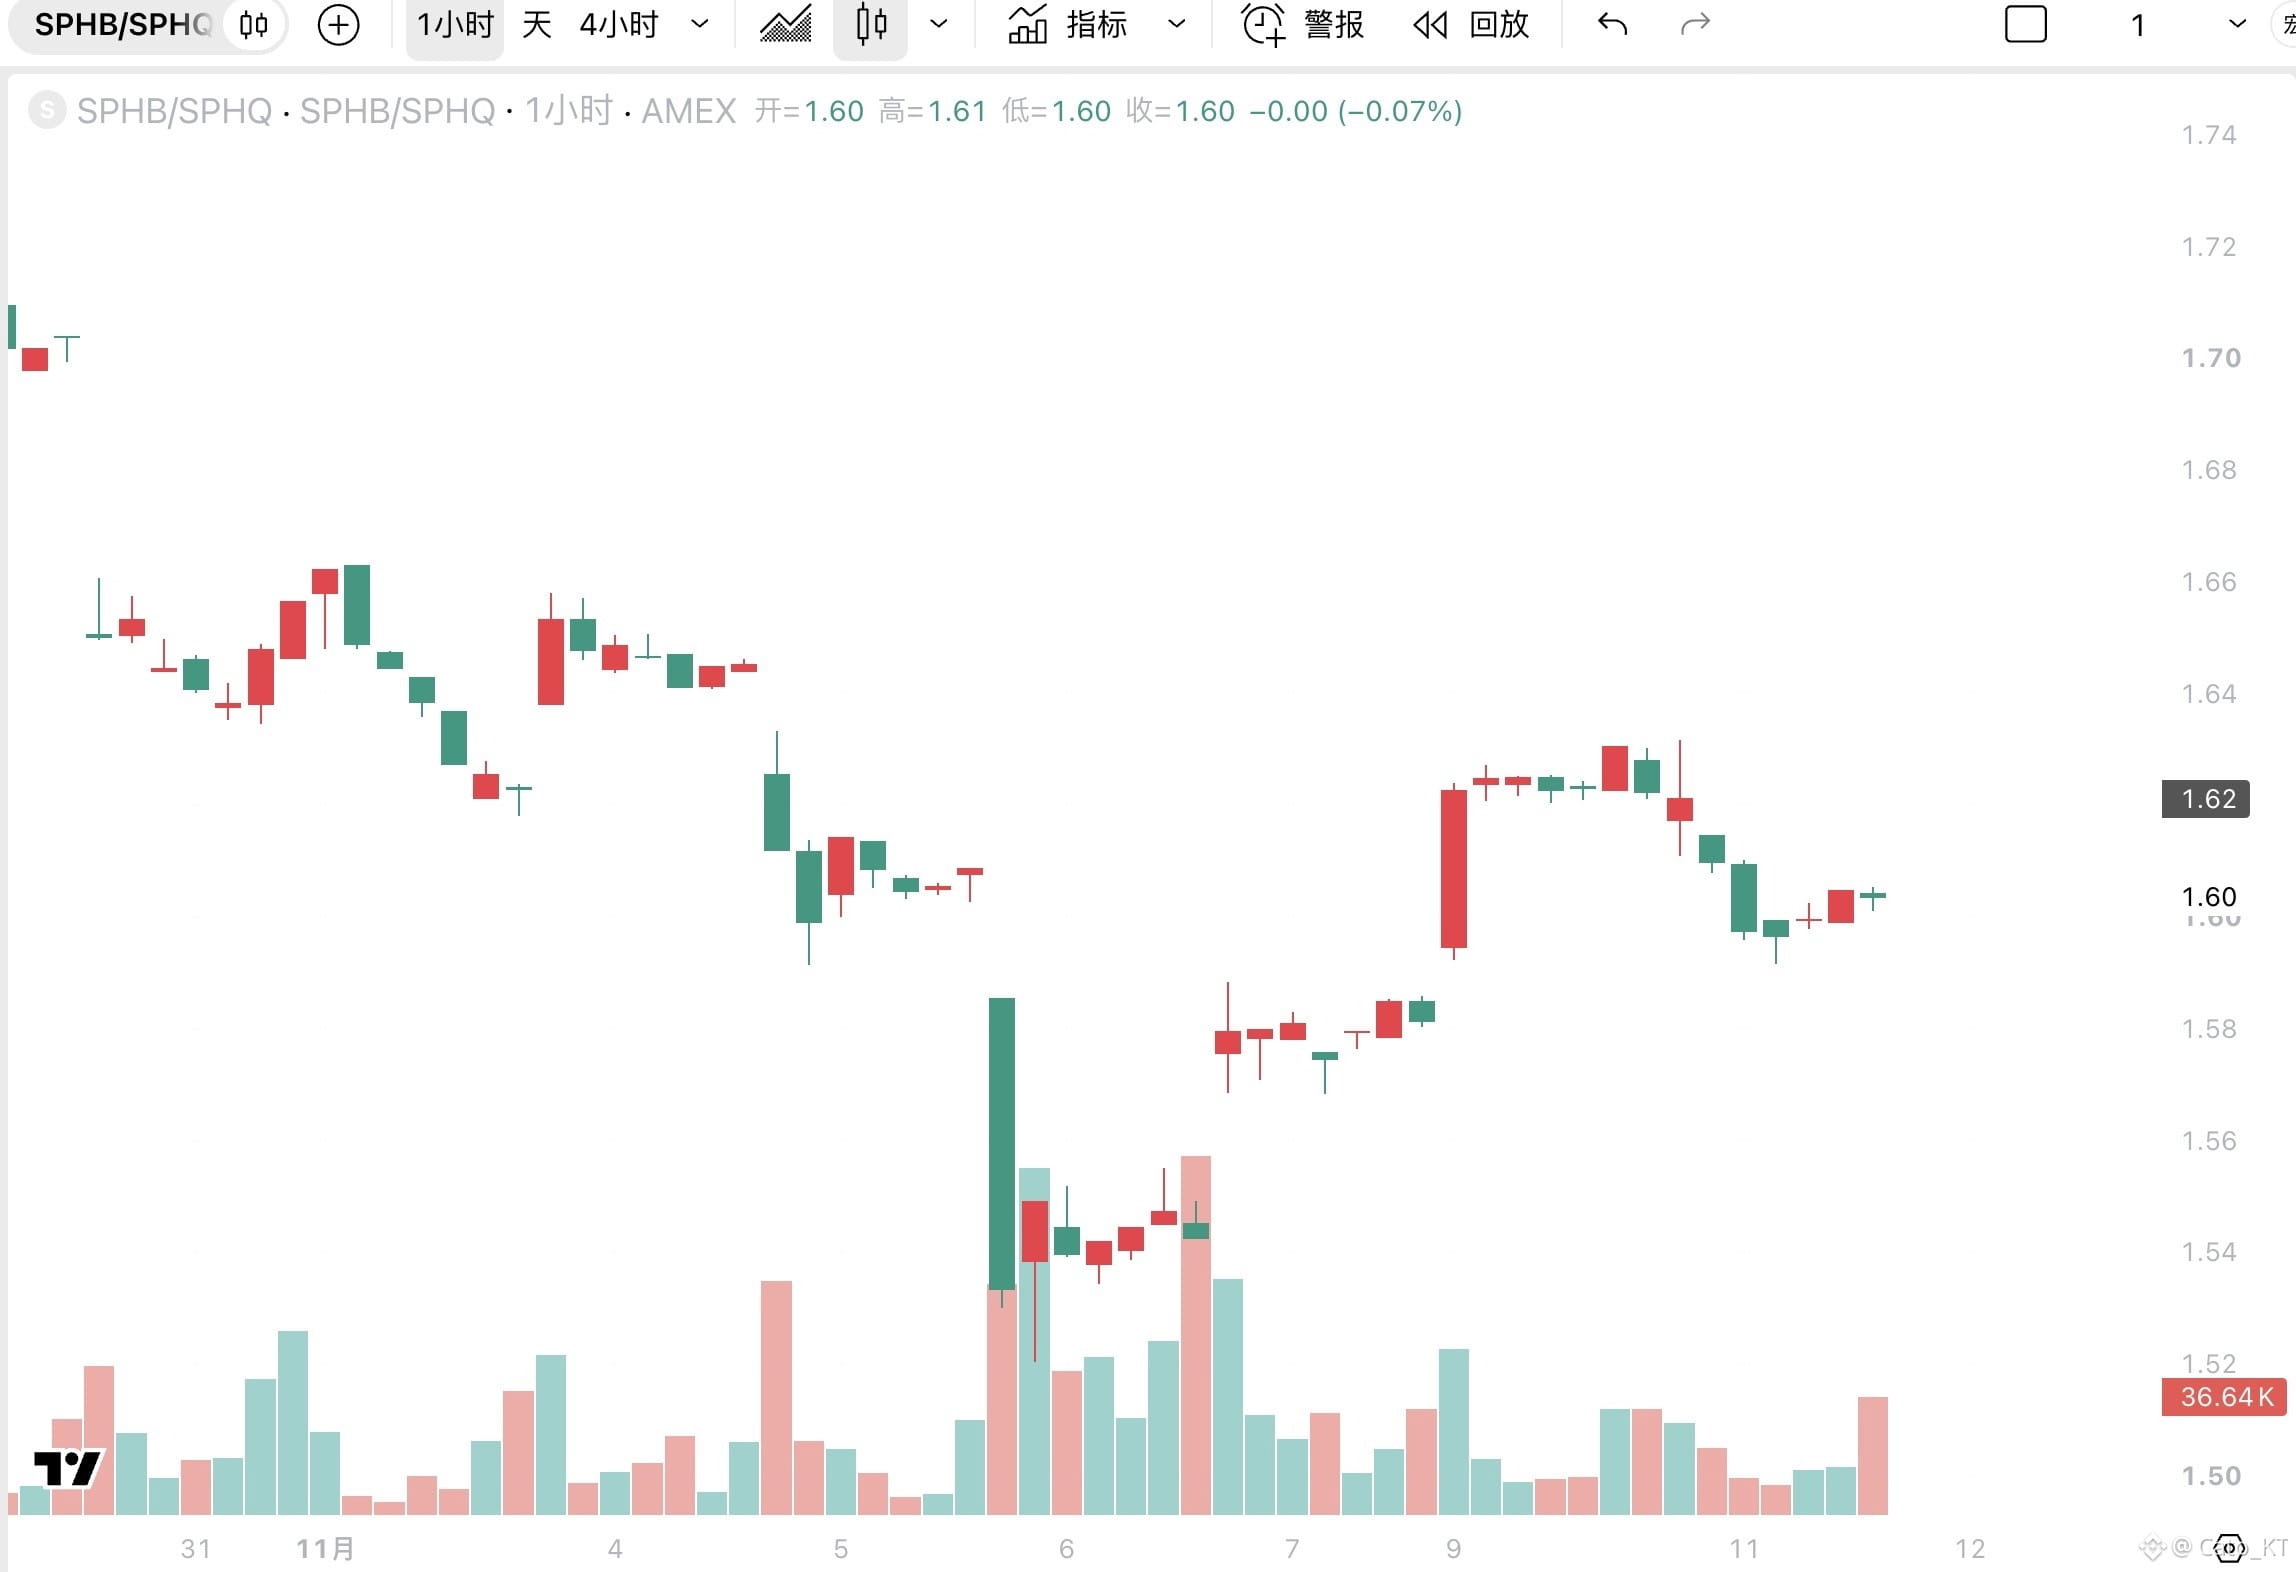
accompanied by a decline in the VIX, indicating lower volatility risk. SPHB/SPHQ indices have rebounded in premarket trading, and risk appetite has increased.
From here, unless macroeconomic data supports the need for further hikes, Fed governors take a more hawkish stance, or Brent rises back above $95, the market's negative pricing of tighter rates in December is basically over for now! As for bond yields, during tonight's U.S. session, watch to see whether 2Y and 10Y yields continue to rise!
Be cautious about this Friday's PPI data. If inflation at the producer level also rises sharply, we can basically expect October PCE to rise as well. These factors will all increase the likelihood of a 50 bp rate hike in December or consecutive hikes in January! #CPI高于预期,美股与BTC再度承压
This means that short-term pricing expectations for a 50 bp rate hike in December or consecutive rate hikes in January 2027 have initially run their course. U.S. stock indices have also risen in premarket trading,
accompanied by a decline in the VIX, indicating lower volatility risk. SPHB/SPHQ indices have rebounded in premarket trading, and risk appetite has increased.
From here, unless macroeconomic data supports the need for further hikes, Fed governors take a more hawkish stance, or Brent rises back above $95, the market's negative pricing of tighter rates in December is basically over for now! As for bond yields, during tonight's U.S. session, watch to see whether 2Y and 10Y yields continue to rise!
Be cautious about this Friday's PPI data. If inflation at the producer level also rises sharply, we can basically expect October PCE to rise as well. These factors will all increase the likelihood of a 50 bp rate hike in December or consecutive hikes in January! #CPI高于预期,美股与BTC再度承压