CPI came in hotter than expected, bringing the crypto market straight back to reality.
U.S. October headline CPI rose 0.4% month over month, while core CPI rose 0.3%—both above expectations. Sticky inflation is rearing its head again, and the market quickly pushed the probability of a December rate hike close to a certainty. A 25-basis-point hike is almost a foregone conclusion, and talk of a 50-basis-point hike is also heating up. Yields are rising, and risk appetite has cooled instantly.
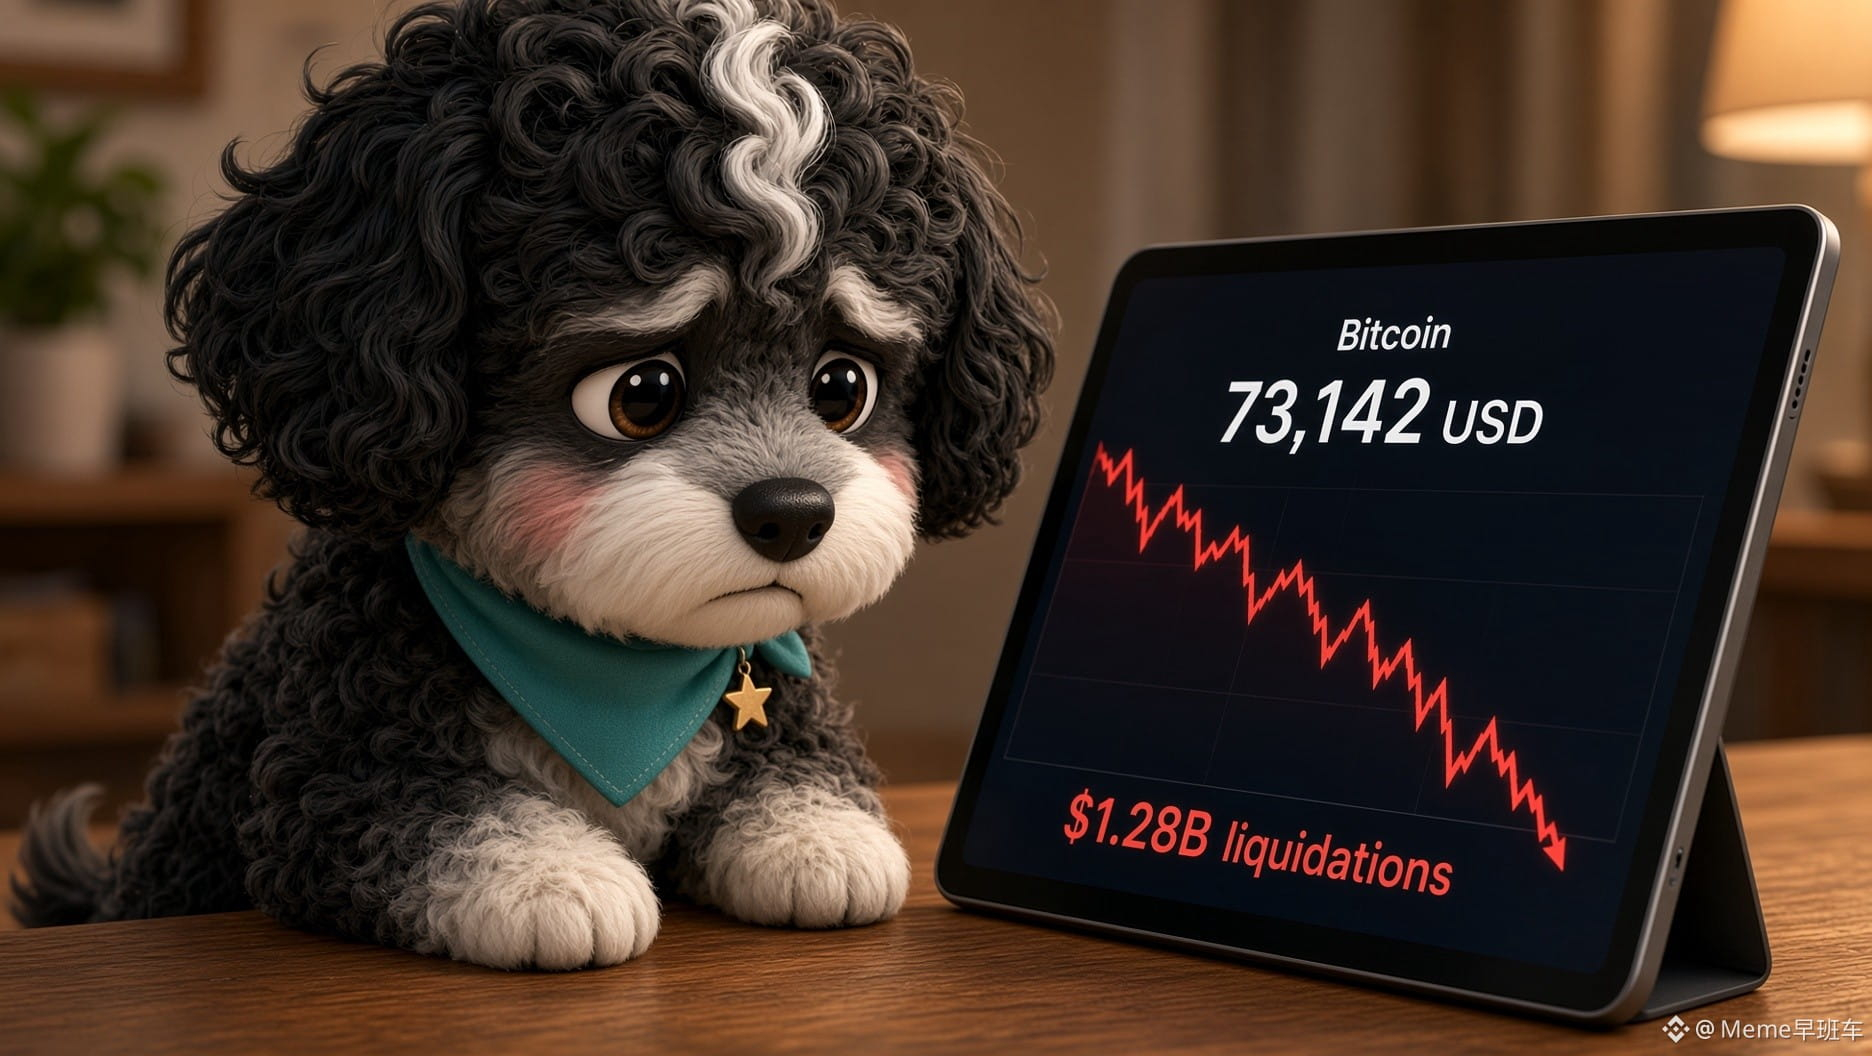
$BTC has given way, hitting a low near $73,500 and now struggling just above $73,000. $ETH fell even harder, already dropping below $2,100. Liquidations across the market topped $1.2 billion over 24 hours, with longs accounting for about $1.04 billion. The concentrated unwinding of leveraged positions has put further pressure on the market.
The flow picture is just as bleak. Spot BTC ETFs continue to see net outflows, with sizeable cumulative outflows over the past few trading days. BlackRock's IBIT remains the main source of redemptions; ETH ETFs are also bleeding funds. Institutions have shown no clear signs of buying the dip and are instead continuing to reduce their positions. MARA's earlier sale of more than 10,000 BTC to repay debt has also heightened the market's sensitivity to selling pressure.
The current picture is clear: macro expectations are driving the market. Rising rate-hike odds are weighing on liquidity expectations, and crypto, as a high-risk asset class, is among the first to correct. The Fear and Greed Index has fallen into fear territory, and sentiment is weak.
In the short term, around $73,000 is a key level. If yields continue to rise, prices could fall further. But after the consecutive pullbacks, a large amount of leverage has already been flushed out, so further declines would require a stronger macro catalyst. Before the December meeting, the market will continue to follow the data. For now, it may be better to wait and see rather than rush to buy the dip or go short. $ZEC
U.S. October headline CPI rose 0.4% month over month, while core CPI rose 0.3%—both above expectations. Sticky inflation is rearing its head again, and the market quickly pushed the probability of a December rate hike close to a certainty. A 25-basis-point hike is almost a foregone conclusion, and talk of a 50-basis-point hike is also heating up. Yields are rising, and risk appetite has cooled instantly.
$BTC has given way, hitting a low near $73,500 and now struggling just above $73,000. $ETH fell even harder, already dropping below $2,100. Liquidations across the market topped $1.2 billion over 24 hours, with longs accounting for about $1.04 billion. The concentrated unwinding of leveraged positions has put further pressure on the market.
The flow picture is just as bleak. Spot BTC ETFs continue to see net outflows, with sizeable cumulative outflows over the past few trading days. BlackRock's IBIT remains the main source of redemptions; ETH ETFs are also bleeding funds. Institutions have shown no clear signs of buying the dip and are instead continuing to reduce their positions. MARA's earlier sale of more than 10,000 BTC to repay debt has also heightened the market's sensitivity to selling pressure.
The current picture is clear: macro expectations are driving the market. Rising rate-hike odds are weighing on liquidity expectations, and crypto, as a high-risk asset class, is among the first to correct. The Fear and Greed Index has fallen into fear territory, and sentiment is weak.
In the short term, around $73,000 is a key level. If yields continue to rise, prices could fall further. But after the consecutive pullbacks, a large amount of leverage has already been flushed out, so further declines would require a stronger macro catalyst. Before the December meeting, the market will continue to follow the data. For now, it may be better to wait and see rather than rush to buy the dip or go short. $ZEC