We’d only just finished celebrating yesterday’s +5%, and today the CPI poured cold water on the rally. All three memory stocks turned lower premarket, so this rebound may not be on solid footing yet.
At 8:30 this morning, U.S. October CPI came in: headline inflation was +0.4%, and core inflation was +0.3%—both 0.1 percentage points above expectations. Core CPI has now risen +0.3% for three consecutive months, and Fed Governor Waller had just said that if core inflation hits +0.3%, the Fed should consider a 50-basis-point hike. A December hike is now all but certain; the question is whether they’ll need to hike even more aggressively.
Yesterday’s huge rally was impressive, but premarket today gave back gains just as quickly. At the November 9 close: $SMH 487.41 (+5.05%), $MU 733.15 (+6.25%), $SNDK 886.51 (+6.16%), and Western Digital at 289.78 (+9.86%). South Korea was even hotter today: the KOSPI rose 4.39%, Samsung gained 4.74%, and SK Hynix gained 6.69%. But once CPI came out, everything changed premarket (8:55 a.m. ET): SMH around 475.52 (-2.44%), Micron around 711.03 (-3.02%), SanDisk around 852.61 (-3.82%), and Western Digital around 284.64 (-1.78%). Nearly half of yesterday’s gains were wiped out.
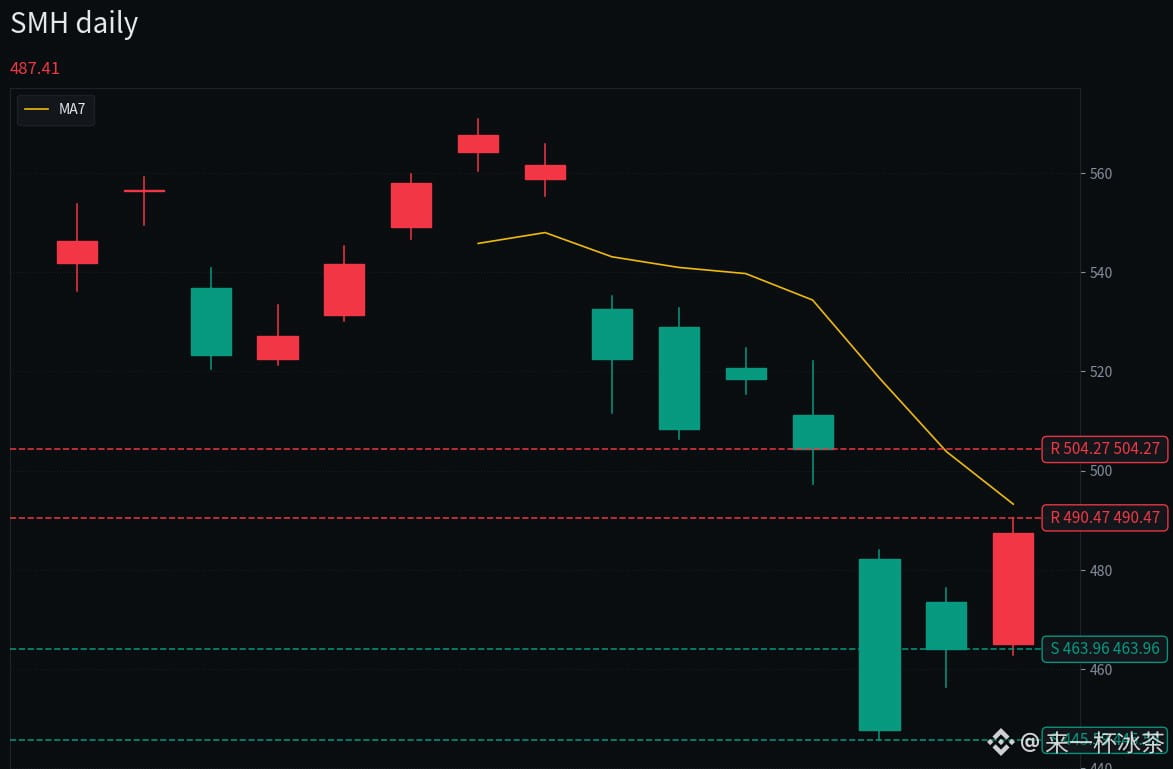
The chart makes it clear: SMH is down 19.21% in a month from its October 28 high of 567.67. Yesterday’s big green candle couldn’t even hold above 490.47 before CPI knocked it back down.
So, are valuations actually expensive? Based on the November 9 close, Micron’s P/E was 9.19x, SanDisk’s 6.12x, and Western Digital’s 10.83x (Finnhub)—they look absurdly cheap. But that’s the old story with cyclical stocks: P/E always looks cheapest when profits are at their peak. P/B relative to ROE, EV/EBITDA, and free cash flow are all being measured against peak earnings right now. Whether they’re expensive depends on whether price increases can continue. TrendForce’s Q4 contract price guidance still calls for DRAM up 10–15% and NAND up 15–20%. That anchor hasn’t moved, so the cycle hasn’t been invalidated yet.
My view: The cycle hasn’t peaked, but I’m not chasing tonight. CPI is hot and rate-hike expectations are rising; rushing in now is basically betting against the Fed.
Support: 463.96 / 445.59
Resistance: 490.47 / 504.27
Hold 463.96 → The rebound is still alive; if the CPI setback is recovered within two days, there’s still a chance.
Break below 445.59 and fail to reclaim it within two days → The rebound is invalidated; step aside for now.
Break above 490.47 → Sentiment turns around, and the shortage narrative takes over again.
I’m cautiously bullish but staying on the sidelines—not chasing. I’ll wait for a pullback or for the December rate-hike shoe to drop. I’ll admit I’m wrong if SMH closes below 445.59 and can’t reclaim it within two days, or if DRAM contract prices turn lower.
Which side are you choosing tonight: buy in batches on the premarket pullback, or wait until the rate-hike shoe drops before making a move?
⚠️Just my personal rambling; this is not investment advice.
#美国CPI #存储 #Semiconductors
At 8:30 this morning, U.S. October CPI came in: headline inflation was +0.4%, and core inflation was +0.3%—both 0.1 percentage points above expectations. Core CPI has now risen +0.3% for three consecutive months, and Fed Governor Waller had just said that if core inflation hits +0.3%, the Fed should consider a 50-basis-point hike. A December hike is now all but certain; the question is whether they’ll need to hike even more aggressively.
Yesterday’s huge rally was impressive, but premarket today gave back gains just as quickly. At the November 9 close: $SMH 487.41 (+5.05%), $MU 733.15 (+6.25%), $SNDK 886.51 (+6.16%), and Western Digital at 289.78 (+9.86%). South Korea was even hotter today: the KOSPI rose 4.39%, Samsung gained 4.74%, and SK Hynix gained 6.69%. But once CPI came out, everything changed premarket (8:55 a.m. ET): SMH around 475.52 (-2.44%), Micron around 711.03 (-3.02%), SanDisk around 852.61 (-3.82%), and Western Digital around 284.64 (-1.78%). Nearly half of yesterday’s gains were wiped out.
The chart makes it clear: SMH is down 19.21% in a month from its October 28 high of 567.67. Yesterday’s big green candle couldn’t even hold above 490.47 before CPI knocked it back down.
So, are valuations actually expensive? Based on the November 9 close, Micron’s P/E was 9.19x, SanDisk’s 6.12x, and Western Digital’s 10.83x (Finnhub)—they look absurdly cheap. But that’s the old story with cyclical stocks: P/E always looks cheapest when profits are at their peak. P/B relative to ROE, EV/EBITDA, and free cash flow are all being measured against peak earnings right now. Whether they’re expensive depends on whether price increases can continue. TrendForce’s Q4 contract price guidance still calls for DRAM up 10–15% and NAND up 15–20%. That anchor hasn’t moved, so the cycle hasn’t been invalidated yet.
My view: The cycle hasn’t peaked, but I’m not chasing tonight. CPI is hot and rate-hike expectations are rising; rushing in now is basically betting against the Fed.
Support: 463.96 / 445.59
Resistance: 490.47 / 504.27
Hold 463.96 → The rebound is still alive; if the CPI setback is recovered within two days, there’s still a chance.
Break below 445.59 and fail to reclaim it within two days → The rebound is invalidated; step aside for now.
Break above 490.47 → Sentiment turns around, and the shortage narrative takes over again.
I’m cautiously bullish but staying on the sidelines—not chasing. I’ll wait for a pullback or for the December rate-hike shoe to drop. I’ll admit I’m wrong if SMH closes below 445.59 and can’t reclaim it within two days, or if DRAM contract prices turn lower.
Which side are you choosing tonight: buy in batches on the premarket pullback, or wait until the rate-hike shoe drops before making a move?
⚠️Just my personal rambling; this is not investment advice.
#美国CPI #存储 #Semiconductors