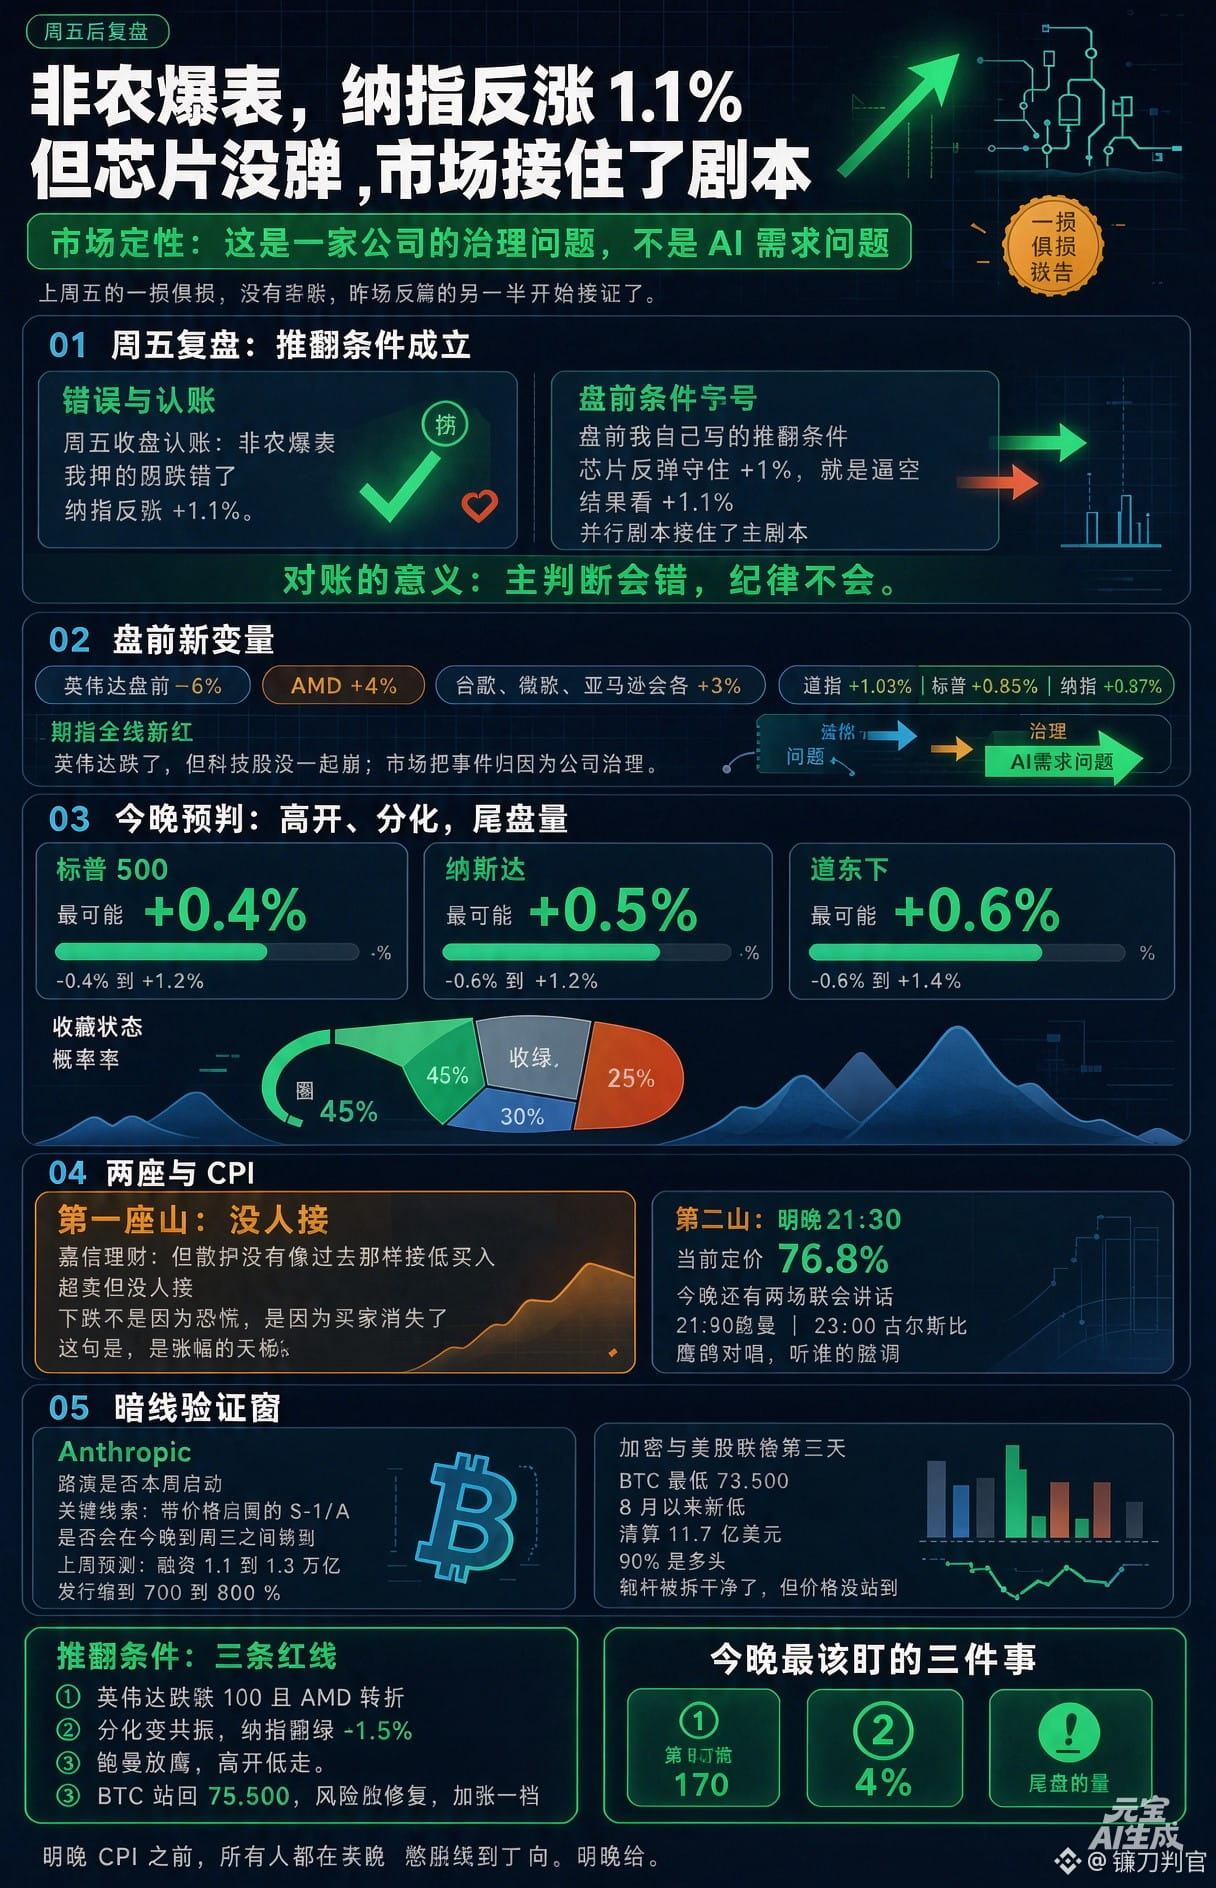

Friday’s close—I’ll own it: nonfarm payrolls blew past expectations, my bet on a slow grind lower was wrong, and the Nasdaq rose 1.1%.
But one thing saved the day—
Before the open, I wrote down my own invalidation condition: if the chip rebound held above +1%, that would be a short squeeze, and the Nasdaq could reach +1.5%.
It ended up at +1.1%. The parallel scenario caught the main one.
That’s the point of keeping score. The main call can be wrong; the discipline doesn’t have to be.
Tonight, it’s the same story with a different lead character.
Nvidia is down 6% premarket, with its affair now under a board investigation.
But AMD is up 4%, and Google, Microsoft, and Amazon are each up 3%.
Index futures are all in the green: Dow +1.03%, S&P 500 +0.85%, Nasdaq +0.87%.
The market has made its call on this:
This is a corporate governance problem at one company, not a problem with AI demand.
The across-the-board selloff we saw last Friday hasn’t happened again.
The other half of the cloud thesis started to be tested last night.
Restrictions on new builds hurt incremental hardware demand, not existing infrastructure or the giants.
Tonight’s call: gap higher, digest through mixed trading, lighter volume late in the session, and a modestly bullish close.
S&P 500: -0.4% to +1.2%, with +0.4% most likely
Nasdaq: -0.6% to +1.2%, with +0.5% most likely
Dow: -0.3% to +1.4%, with +0.6% most likely
45% chance of a higher close, 30% chance of a flat session, 25% chance of turning negative.
Two mountains are capping the gains.
Charles Schwab’s exact words: “Oversold, but retail investors aren’t buying the dip like they used to.”
Oversold, but no one’s stepping in—the selloff isn’t driven by panic; it’s because the buyers have disappeared.
That’s the ceiling on the gains.
The second mountain: CPI tomorrow night at 21:30.
The last inflation report before the December rate decision. Current pricing: 76.8%.
There are also two Fed speakers tonight: Bowman at 21:40 and Goolsbee at 23:00. Hawks and doves singing together—listen for the tone.
One more undercurrent: Anthropic.
The key clue as to whether the roadshow kicks off this week is whether an S-1/A with a price range lands sometime between tonight and Wednesday.
My forecast last week: a valuation range of 1.1 to 1.3 trillion, with the offering cut to 70 to 80 billion.
This week is the test window.
Three invalidation conditions:
Nvidia breaks below 170 and AMD turns lower: divergence becomes a synchronized move, and the Nasdaq turns red, falling 1.5%.
Bowman turns hawkish: gap higher, then fade.
BTC gets back above 75,000: risk appetite recovers, and I’ll raise the bullish call by one notch.
Watch three things: Nvidia at 170; AMD at 4%; and volume late in the session.
Before tomorrow night’s CPI, everyone is holding their breath.
The direction that emerges will come tomorrow night.
$AMD
$NVDA
But one thing saved the day—
Before the open, I wrote down my own invalidation condition: if the chip rebound held above +1%, that would be a short squeeze, and the Nasdaq could reach +1.5%.
It ended up at +1.1%. The parallel scenario caught the main one.
That’s the point of keeping score. The main call can be wrong; the discipline doesn’t have to be.
Tonight, it’s the same story with a different lead character.
Nvidia is down 6% premarket, with its affair now under a board investigation.
But AMD is up 4%, and Google, Microsoft, and Amazon are each up 3%.
Index futures are all in the green: Dow +1.03%, S&P 500 +0.85%, Nasdaq +0.87%.
The market has made its call on this:
This is a corporate governance problem at one company, not a problem with AI demand.
The across-the-board selloff we saw last Friday hasn’t happened again.
The other half of the cloud thesis started to be tested last night.
Restrictions on new builds hurt incremental hardware demand, not existing infrastructure or the giants.
Tonight’s call: gap higher, digest through mixed trading, lighter volume late in the session, and a modestly bullish close.
S&P 500: -0.4% to +1.2%, with +0.4% most likely
Nasdaq: -0.6% to +1.2%, with +0.5% most likely
Dow: -0.3% to +1.4%, with +0.6% most likely
45% chance of a higher close, 30% chance of a flat session, 25% chance of turning negative.
Two mountains are capping the gains.
Charles Schwab’s exact words: “Oversold, but retail investors aren’t buying the dip like they used to.”
Oversold, but no one’s stepping in—the selloff isn’t driven by panic; it’s because the buyers have disappeared.
That’s the ceiling on the gains.
The second mountain: CPI tomorrow night at 21:30.
The last inflation report before the December rate decision. Current pricing: 76.8%.
There are also two Fed speakers tonight: Bowman at 21:40 and Goolsbee at 23:00. Hawks and doves singing together—listen for the tone.
One more undercurrent: Anthropic.
The key clue as to whether the roadshow kicks off this week is whether an S-1/A with a price range lands sometime between tonight and Wednesday.
My forecast last week: a valuation range of 1.1 to 1.3 trillion, with the offering cut to 70 to 80 billion.
This week is the test window.
Three invalidation conditions:
Nvidia breaks below 170 and AMD turns lower: divergence becomes a synchronized move, and the Nasdaq turns red, falling 1.5%.
Bowman turns hawkish: gap higher, then fade.
BTC gets back above 75,000: risk appetite recovers, and I’ll raise the bullish call by one notch.
Watch three things: Nvidia at 170; AMD at 4%; and volume late in the session.
Before tomorrow night’s CPI, everyone is holding their breath.
The direction that emerges will come tomorrow night.
$AMD
$NVDA