NVDA at $176—would you buy the dip?
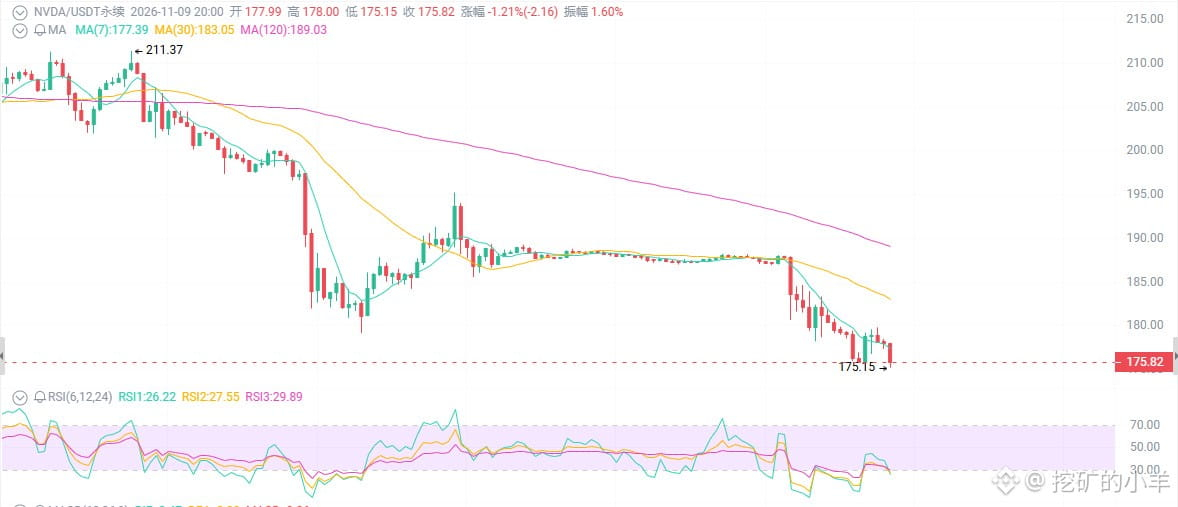
Down 9% in a single day, $400 billion wiped off its market cap, rumors swirling about the CEO, and regulators breathing down its neck—everyone’s shouting, “The AI bubble has burst.” Just now, the price plunged to around $175, with the RSI hitting the oversold zone at 25, and earnings on November 17 just days away. So is this the end of the bull market, or a golden buying opportunity?
First, the surface picture: a barrage of bad news is hammering the stock, and the bulls can barely get back up.
From its October high of $243, it’s fallen all the way to $176—a drop of over 20% in a month. It’s broken below the 50-day and 200-day moving averages, the weekly ascending wedge has broken down, and the MACD is in a bearish alignment. Regulatory concerns have intensified after the midterm elections, export controls could tighten again, and rumors about the CEO’s personal affairs and a board investigation weighed on the stock before the market opened. On November 5, it plunged 9% in a single day, wiping more than $400 billion off its market cap.
First thing to remember: it’s the stock price that’s falling, not computing demand.
The latest earnings report: Q2 revenue was $96.2 billion, up 106% year over year; data center revenue was $89 billion, up 117%; and gross margin was 75%. Q3 guidance is $108 billion. The preliminary FY2028 outlook calls for revenue growth of around 70%—note that this assumes “supply constraints”; actual demand is higher.
The Vera Rubin platform has already started shipping and is expected to account for about 20% of data center revenue next quarter. Major customers like AWS are still increasing their orders.
AI demand hasn’t collapsed. Orders haven’t collapsed. Margins haven’t collapsed. What’s collapsed is the value of your leverage and your nerves.
Second thing: at $176, a lot of bearish expectations are already priced in.
The forward P/E has come down significantly, with some analysts pointing to a range in the teens. Most Wall Street price targets are still around $250–$300+.
The market isn’t pricing in “NVDA is finished.” It’s pricing in “NVDA can’t keep skyrocketing like it used to.” Those are two very different things.
Customers developing their own chips, memory costs squeezing gross margins down to 71–73%, and Chinese revenue essentially falling to zero—these headwinds are already reflected in the price. What you’re afraid of now is what you should have been afraid of three months ago.
Third thing: the technicals are oversold, and earnings could be a turning point.
The daily RSI has hit 25–30, which is oversold territory. $175–$170 is strong support, while $164–$165 is near the 52-week low. Higher trading volume confirms the selling, but after an oversold drop, a technical rebound could come at any time.
Key date: Q3 earnings on November 17.
If guidance beats expectations and FY2028 growth is confirmed, a V-shaped rebound isn’t out of the question.
If results disappoint or regulators tighten the screws further, the stock could test $165 or even lower.
Down 9% in a single day, $400 billion wiped off its market cap, rumors swirling about the CEO, and regulators breathing down its neck—everyone’s shouting, “The AI bubble has burst.” Just now, the price plunged to around $175, with the RSI hitting the oversold zone at 25, and earnings on November 17 just days away. So is this the end of the bull market, or a golden buying opportunity?
First, the surface picture: a barrage of bad news is hammering the stock, and the bulls can barely get back up.
From its October high of $243, it’s fallen all the way to $176—a drop of over 20% in a month. It’s broken below the 50-day and 200-day moving averages, the weekly ascending wedge has broken down, and the MACD is in a bearish alignment. Regulatory concerns have intensified after the midterm elections, export controls could tighten again, and rumors about the CEO’s personal affairs and a board investigation weighed on the stock before the market opened. On November 5, it plunged 9% in a single day, wiping more than $400 billion off its market cap.
First thing to remember: it’s the stock price that’s falling, not computing demand.
The latest earnings report: Q2 revenue was $96.2 billion, up 106% year over year; data center revenue was $89 billion, up 117%; and gross margin was 75%. Q3 guidance is $108 billion. The preliminary FY2028 outlook calls for revenue growth of around 70%—note that this assumes “supply constraints”; actual demand is higher.
The Vera Rubin platform has already started shipping and is expected to account for about 20% of data center revenue next quarter. Major customers like AWS are still increasing their orders.
AI demand hasn’t collapsed. Orders haven’t collapsed. Margins haven’t collapsed. What’s collapsed is the value of your leverage and your nerves.
Second thing: at $176, a lot of bearish expectations are already priced in.
The forward P/E has come down significantly, with some analysts pointing to a range in the teens. Most Wall Street price targets are still around $250–$300+.
The market isn’t pricing in “NVDA is finished.” It’s pricing in “NVDA can’t keep skyrocketing like it used to.” Those are two very different things.
Customers developing their own chips, memory costs squeezing gross margins down to 71–73%, and Chinese revenue essentially falling to zero—these headwinds are already reflected in the price. What you’re afraid of now is what you should have been afraid of three months ago.
Third thing: the technicals are oversold, and earnings could be a turning point.
The daily RSI has hit 25–30, which is oversold territory. $175–$170 is strong support, while $164–$165 is near the 52-week low. Higher trading volume confirms the selling, but after an oversold drop, a technical rebound could come at any time.
Key date: Q3 earnings on November 17.
If guidance beats expectations and FY2028 growth is confirmed, a V-shaped rebound isn’t out of the question.
If results disappoint or regulators tighten the screws further, the stock could test $165 or even lower.