Regulations are easing, but don’t rush to call it a bull market.
FinCEN and the Federal Reserve have withdrawn a proposed expansion of recordkeeping requirements and the “Travel Rule.” The proposal would have brought more crypto transactions under mandatory recordkeeping and information-sharing requirements. The Travel Rule requires exchanges to transmit customer identity information when processing transfers. The controversy over the proposed expansion centered on whether non-custodial wallets and transfers between platforms should also be subject to stricter oversight.
The withdrawal means regulators have opted to pause, for now, their efforts to balance compliance burdens with room for innovation. In the short term, it eases compliance costs for exchanges and wallet providers and reduces the tail risk of a sweeping, across-the-board crackdown on the industry. For crypto holders and trading platforms, this is positive for sentiment: compliance pressure is no longer ratcheting up, and the U.S. market appears more welcoming toward crypto businesses.
However, the regulatory direction has not fundamentally reversed. Keep an eye out for any replacement guidance or state-level rules that may fill the gap. In practical terms, this is a medium-term positive, not a reason to chase prices higher in a single day. The key is to watch whether compliance costs for U.S. exchanges and access to liquidity channels improve as a result.
Source: NewsBTC
Which matters more to you: lower compliance costs or improved access to liquidity channels?
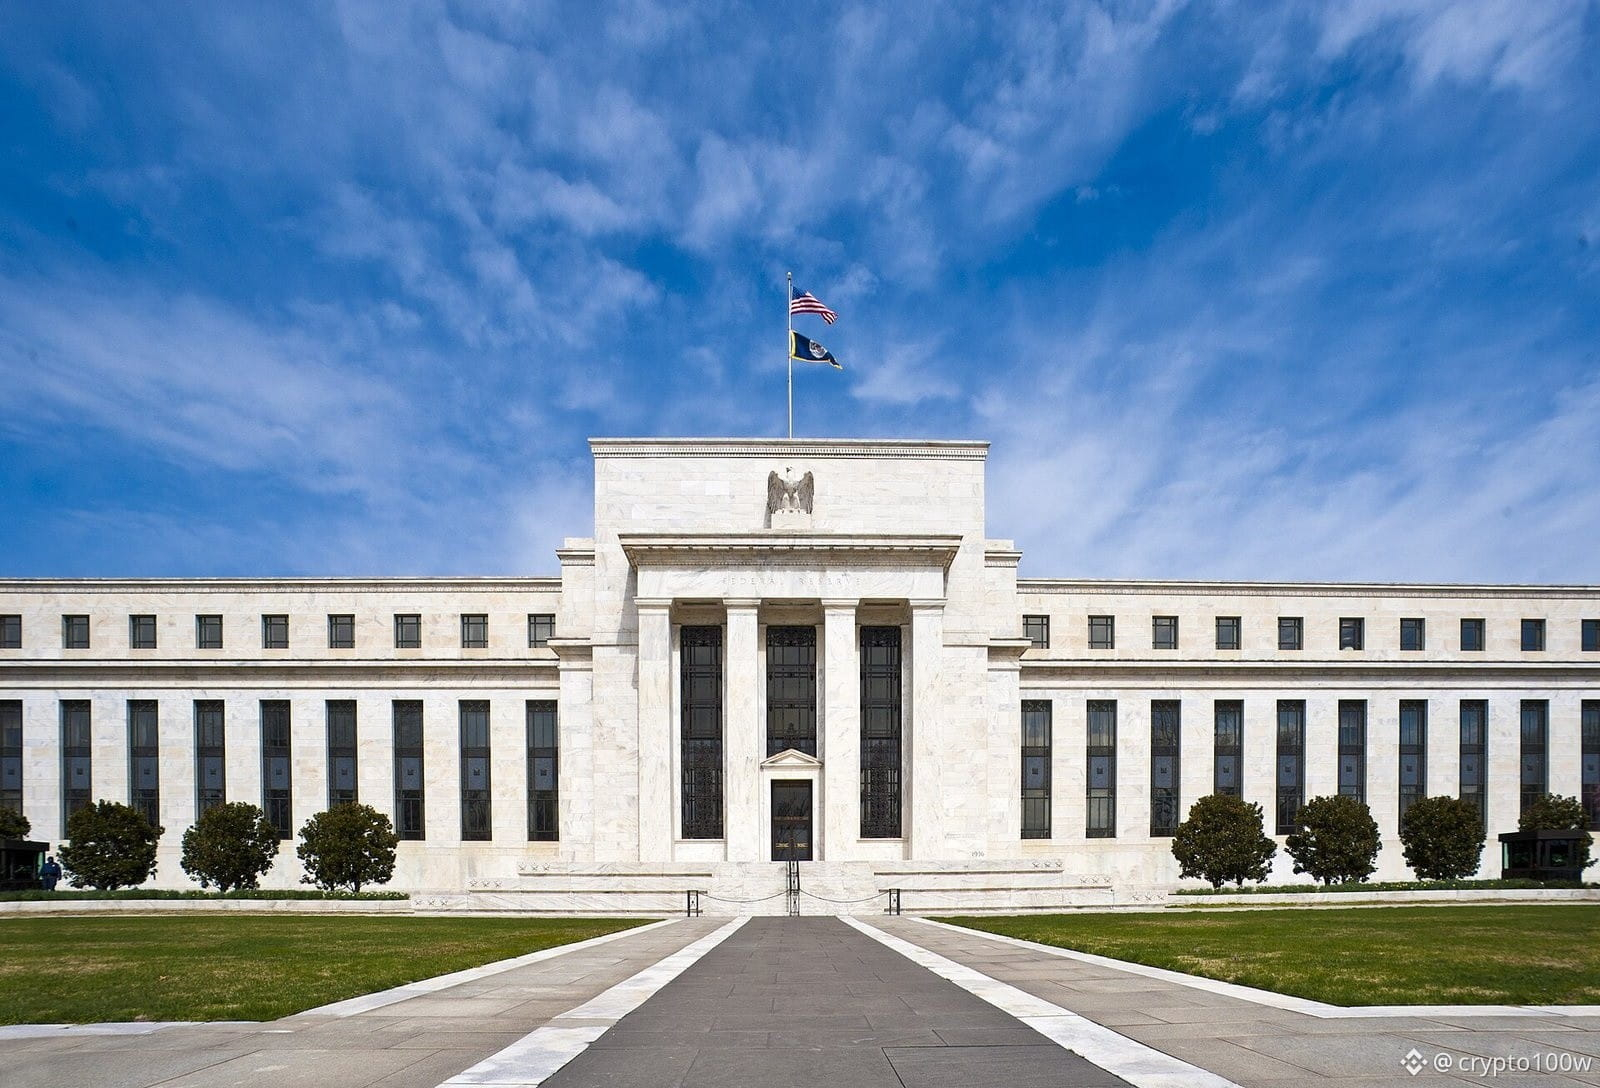
Image 1: FinCEN and the Federal Reserve withdraw proposal to expand the crypto Travel Rule · Image accompanying the source article
Image source: https://www.newsbtc.com/regulation/fincen-withdraws-proposed-crypto-travel-rule-expansion-in-separate-november-move/
FinCEN and the Federal Reserve have withdrawn a proposed expansion of recordkeeping requirements and the “Travel Rule.” The proposal would have brought more crypto transactions under mandatory recordkeeping and information-sharing requirements. The Travel Rule requires exchanges to transmit customer identity information when processing transfers. The controversy over the proposed expansion centered on whether non-custodial wallets and transfers between platforms should also be subject to stricter oversight.
The withdrawal means regulators have opted to pause, for now, their efforts to balance compliance burdens with room for innovation. In the short term, it eases compliance costs for exchanges and wallet providers and reduces the tail risk of a sweeping, across-the-board crackdown on the industry. For crypto holders and trading platforms, this is positive for sentiment: compliance pressure is no longer ratcheting up, and the U.S. market appears more welcoming toward crypto businesses.
However, the regulatory direction has not fundamentally reversed. Keep an eye out for any replacement guidance or state-level rules that may fill the gap. In practical terms, this is a medium-term positive, not a reason to chase prices higher in a single day. The key is to watch whether compliance costs for U.S. exchanges and access to liquidity channels improve as a result.
Source: NewsBTC
Which matters more to you: lower compliance costs or improved access to liquidity channels?
Image 1: FinCEN and the Federal Reserve withdraw proposal to expand the crypto Travel Rule · Image accompanying the source article
Image source: https://www.newsbtc.com/regulation/fincen-withdraws-proposed-crypto-travel-rule-expansion-in-separate-november-move/