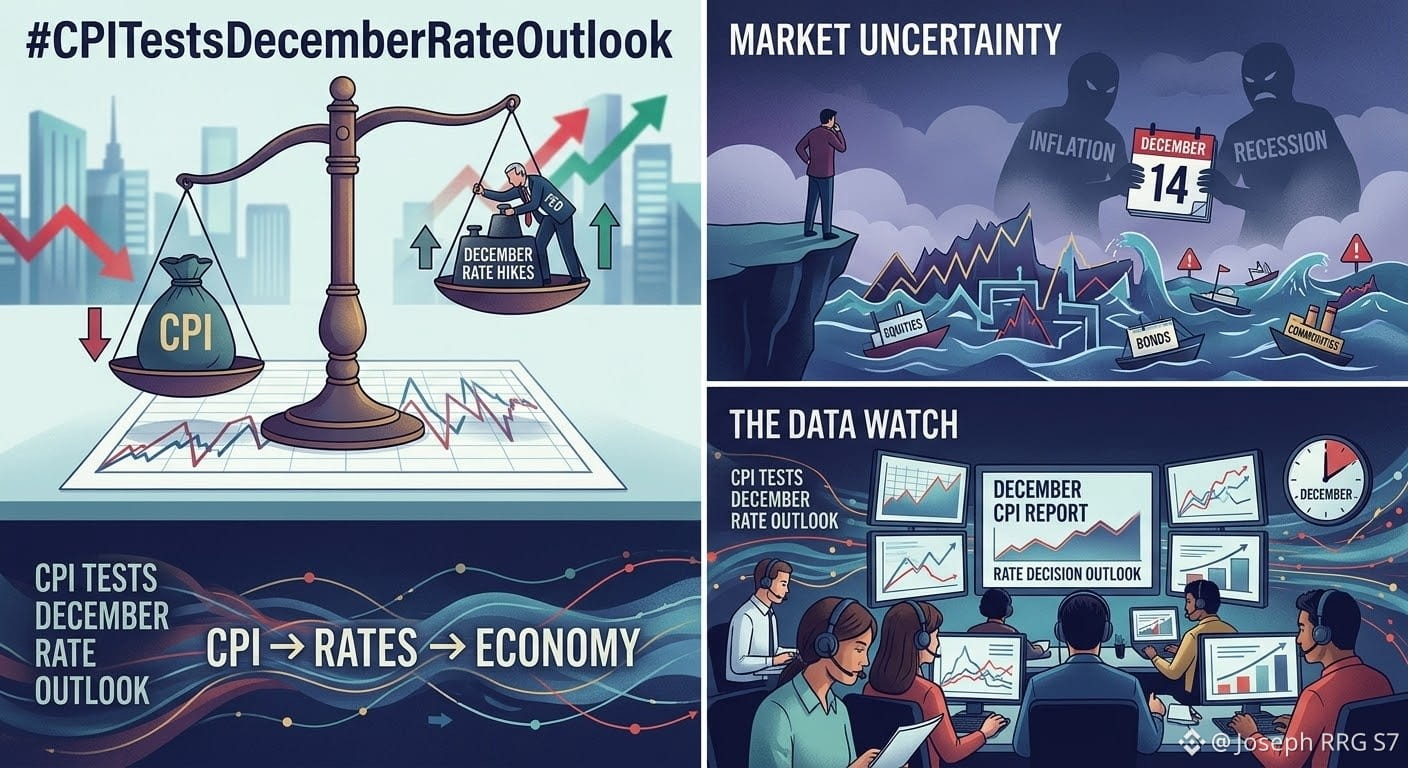
#cpitestsdecemberrateoutlook
CPI data puts December rate expectations to the test:
Financial markets are focused on the upcoming release of the U.S. Consumer Price Index (CPI) for October, scheduled for Tuesday, November 10. This report is shaping up to be a decisive test for gauging the direction of Federal Reserve (Fed) monetary policy ahead of its final meeting of the year, on December 8 and 9.
With the federal funds rate currently in a range of 3.75% to 4.00%, investors are trying to determine whether persistent inflation will force the central bank to make another upward adjustment, or whether the recent moderation will give it room to pause.
The key figures analysts are forecasting
Following the rebound recorded in September—when headline inflation reached 3.7% year over year, with a monthly increase of 0.6%—the market consensus expects the monthly pace of price increases to slow:
Monthly headline inflation: Forecasts point to a moderate increase of between 0.24% (according to the Cleveland Fed's estimate) and 0.3%.
Core inflation (Core CPI): Excluding food and energy, a monthly increase of around 0.3% is projected (roughly 2.5%–2.6% annualized).
A statistical quirk: Because of gaps in last October's price records, the BLS report will not include a standard official year-over-year rate for the headline index, concentrating nearly all the analysis on the monthly change and specific components such as gasoline.
Although prices are expected to cool month over month compared with September, inflation remains comfortably above the Fed's 2% target. This has led futures markets to price in a high probability—close to 80%, according to CME FedWatch data—
$AIN
$ZEC
$BTC
CPI data puts December rate expectations to the test:
Financial markets are focused on the upcoming release of the U.S. Consumer Price Index (CPI) for October, scheduled for Tuesday, November 10. This report is shaping up to be a decisive test for gauging the direction of Federal Reserve (Fed) monetary policy ahead of its final meeting of the year, on December 8 and 9.
With the federal funds rate currently in a range of 3.75% to 4.00%, investors are trying to determine whether persistent inflation will force the central bank to make another upward adjustment, or whether the recent moderation will give it room to pause.
The key figures analysts are forecasting
Following the rebound recorded in September—when headline inflation reached 3.7% year over year, with a monthly increase of 0.6%—the market consensus expects the monthly pace of price increases to slow:
Monthly headline inflation: Forecasts point to a moderate increase of between 0.24% (according to the Cleveland Fed's estimate) and 0.3%.
Core inflation (Core CPI): Excluding food and energy, a monthly increase of around 0.3% is projected (roughly 2.5%–2.6% annualized).
A statistical quirk: Because of gaps in last October's price records, the BLS report will not include a standard official year-over-year rate for the headline index, concentrating nearly all the analysis on the monthly change and specific components such as gasoline.
Although prices are expected to cool month over month compared with September, inflation remains comfortably above the Fed's 2% target. This has led futures markets to price in a high probability—close to 80%, according to CME FedWatch data—
$AIN
$ZEC
$BTC