
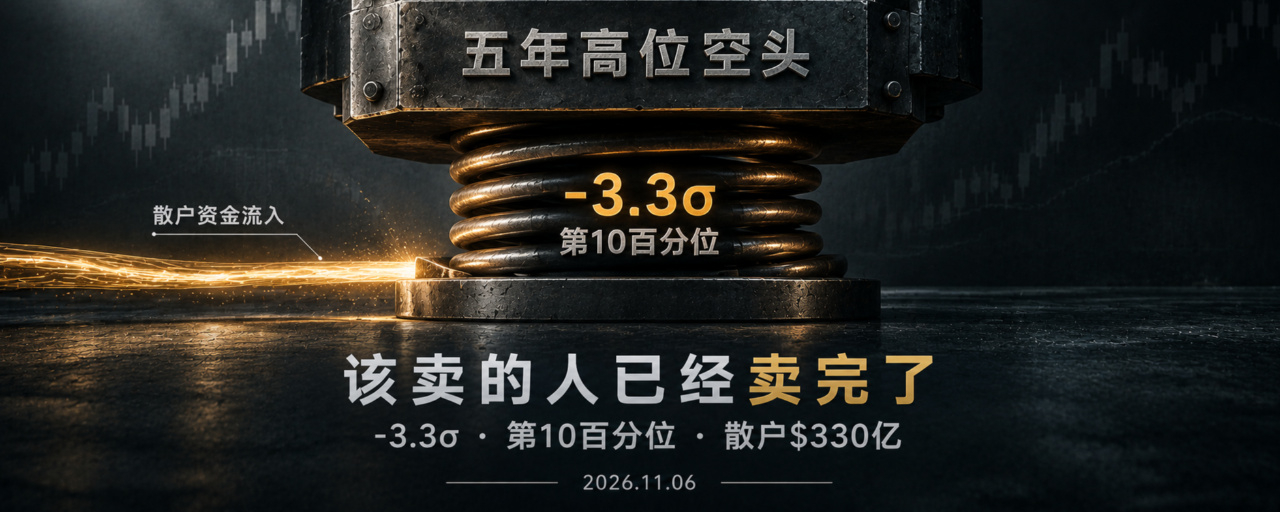

Summary: After the midterm elections were decided, institutions collectively turned bullish. CTA positioning stood at minus 3.3 standard deviations, and short positions were near five-year highs. Yet HSBC remained underweight U.S. tech stocks during the same period, revealing a rift within the consensus.
On November 5, after the midterm election results became clear, U.S. stocks closed higher. The S&P 500 rose 1.58% to 7,688.62, the Dow gained 3.03%, and the Nasdaq rose 1.44%. The VIX fell 20.45% to 16.57, its largest single-day drop since April 2025.
JPMorgan Chase, Citadel Securities, Fidelity, and other institutions issued a flurry of bullish signals over the following day or two. Their reasoning was highly consistent: institutions had already completed large-scale de-risking ahead of the election, short positions were near five-year highs, and those positions themselves were fuel for a rebound.
The bullish case isn’t that “the economy has improved.” It’s that “everyone who needed to sell has already sold.”
Hard data on positioning resets
Citadel Securities’ model provides a quantitative measure of current positioning. CTAs’ net exposure to U.S. equities is around minus 3.3 standard deviations, at the 10th percentile of historical readings since 2018 and the 1.9th percentile of the past year’s range—the lowest level since March 31 this year. Two months ago, the figure was positive 1.7 standard deviations.
Retail investors have continued buying on the other side. Since October 5, they have been net buyers of U.S. equities for 22 consecutive trading days, with cumulative purchases approaching $33 billion—the sixth-longest and fifth-largest buying streak since 2017. Their net purchases so far this year have reached $251 billion, surpassing the full-year record set in 2021.
Corporate buyback windows are also reopening. As of November 2, newly authorized buybacks this year had reached $1.5 trillion, surpassing the previous full-year record. The share of S&P 500 market cap eligible for buybacks is expected to rise to 85% by November 9.
Short covering, retail investors, and buybacks all point in the same direction: marginal selling pressure is easing, while marginal buying demand is recovering.
Valuation compression offers another argument
The Nasdaq 100’s price-to-earnings ratio has fallen to 19.1, its lowest since October 2022 and 24% below its January peak, while its premium to the S&P 500 has narrowed to just 5%. The P/E ratio of S&P 500 semiconductor constituents has fallen to 13.8, down 45% from its January peak. They are trading at a 25% discount to the S&P 500—the steepest since December 2018.
Earnings are moving in the opposite direction. Since June 30, forward EPS estimates for memory, AI infrastructure, and semiconductors have been revised up by 32%, 31%, and 30%, respectively, while their P/E ratios have contracted by 50%, 36%, and 35%. So far this third-quarter earnings season, 83% of companies have beaten earnings estimates, above the historical average of 75%.
Valuations are falling while earnings expectations are rising. The gap between the two forms the valuation-based case for institutional bulls.
A rift within the consensus
The narrative that “institutions are collectively bullish” needs to be taken with a grain of salt when it comes to HSBC.
On November 3, HSBC’s head of multi-asset strategy, Max Kettner, was still warning that “the pain is still ahead,” downgrading the equity allocation from “maximum overweight” to “neutral.” He also explicitly said HSBC would remain underweight U.S. tech stocks, favoring the equal-weight S&P 500 and U.K. equities.
By November 5, Kettner’s message had become “basically, buy everything,” and he described the Anthropic IPO as a “true clearing event” for sentiment toward tech stocks. But “buy everything” describes market action; it is not HSBC’s own positioning recommendation. The same strategist said not to bet on a midterm-election rally just two days earlier, then said two days later that the market was buying everything. Both statements can be true, but they are not the same judgment.
“Institutions are collectively bullish” is a convenient shorthand. Look closer and you’ll find some buying the rebound, some waiting for the IPO, and some saying the market is rallying while remaining underweight the most crowded segment.
This isn’t “new money coming in”; it’s “old positions being rebuilt”
To understand the nature of this rebound, you need to distinguish between two things: short covering and spot buying.
CTAs at minus 3.3 standard deviations means trend-following strategies have cut their positions to extremely low levels. Once the market holds key technical levels, these strategies will be forced to rebuild positions. Scott Rubner of Citadel Securities explicitly said this represents room for “position rebuilding,” not confirmation of “new demand.”
Retail investors’ $33 billion represents genuine buying, but it happened as the S&P 500 fell around 2% over the same period. Retail investors bought on the way down, while institutions turned bullish as the market rose; their timing does not fully overlap. Buybacks are another genuine source of demand, but their seasonal window peaks around November 9. Their persistence afterward depends on corporate cash flows, not the election result.
The bullish case rests on mechanical buying after positions have been cleared out. It can push prices higher without any improvement in fundamentals, but it cannot, on its own, turn a rebound into a sustained trend. Fidelity’s statistics—that markets rose 95% of the time in the 12 months after midterm elections, with an average gain of 14%—reflect historical probabilities, not current positioning.
What to watch next
Whether CTA buying is triggered: minus 3.3 standard deviations is “fuel,” but prices need to hold key technical levels to light the fuse. If the index moves sideways around current levels, the buying won’t happen
Whether HSBC’s stance has truly shifted: Kettner went from “the pain is still ahead” to “buying basically everything” in just two days. The consensus will be complete only if HSBC formally raises its equity allocation and ends its underweight in U.S. tech stocks. If it’s just a change in commentary, the rift remains
The buying gap after the buyback window closes: November 9, when 85% of market cap is expected to be eligible for buybacks, is the peak. After that, buybacks’ marginal contribution to demand will decline. Who steps in then will be a key test of the rebound’s staying power
What happens after short covering is complete: if short positions fall from a five-year high back to neutral, but spot buying doesn’t pick up at the same time, the rebound will run out of fuel
Note: This content is for informational purposes only. Please do your own research.