#美股走弱,加密货币市场普遍承压 Did U.S. stocks drag crypto down? I dug through the liquidation data and found the main culprit wasn’t U.S. stocks
On 11/4, I was wrong to say “defensive assets only”—I admitted it yesterday. But all three of my signals played out: +3.03% wasn’t a trend → Nasdaq -5.52%; oil downgraded → tanker stocks hit the rocks; AI cracks appeared → Philadelphia Semiconductor Index -12.25%.
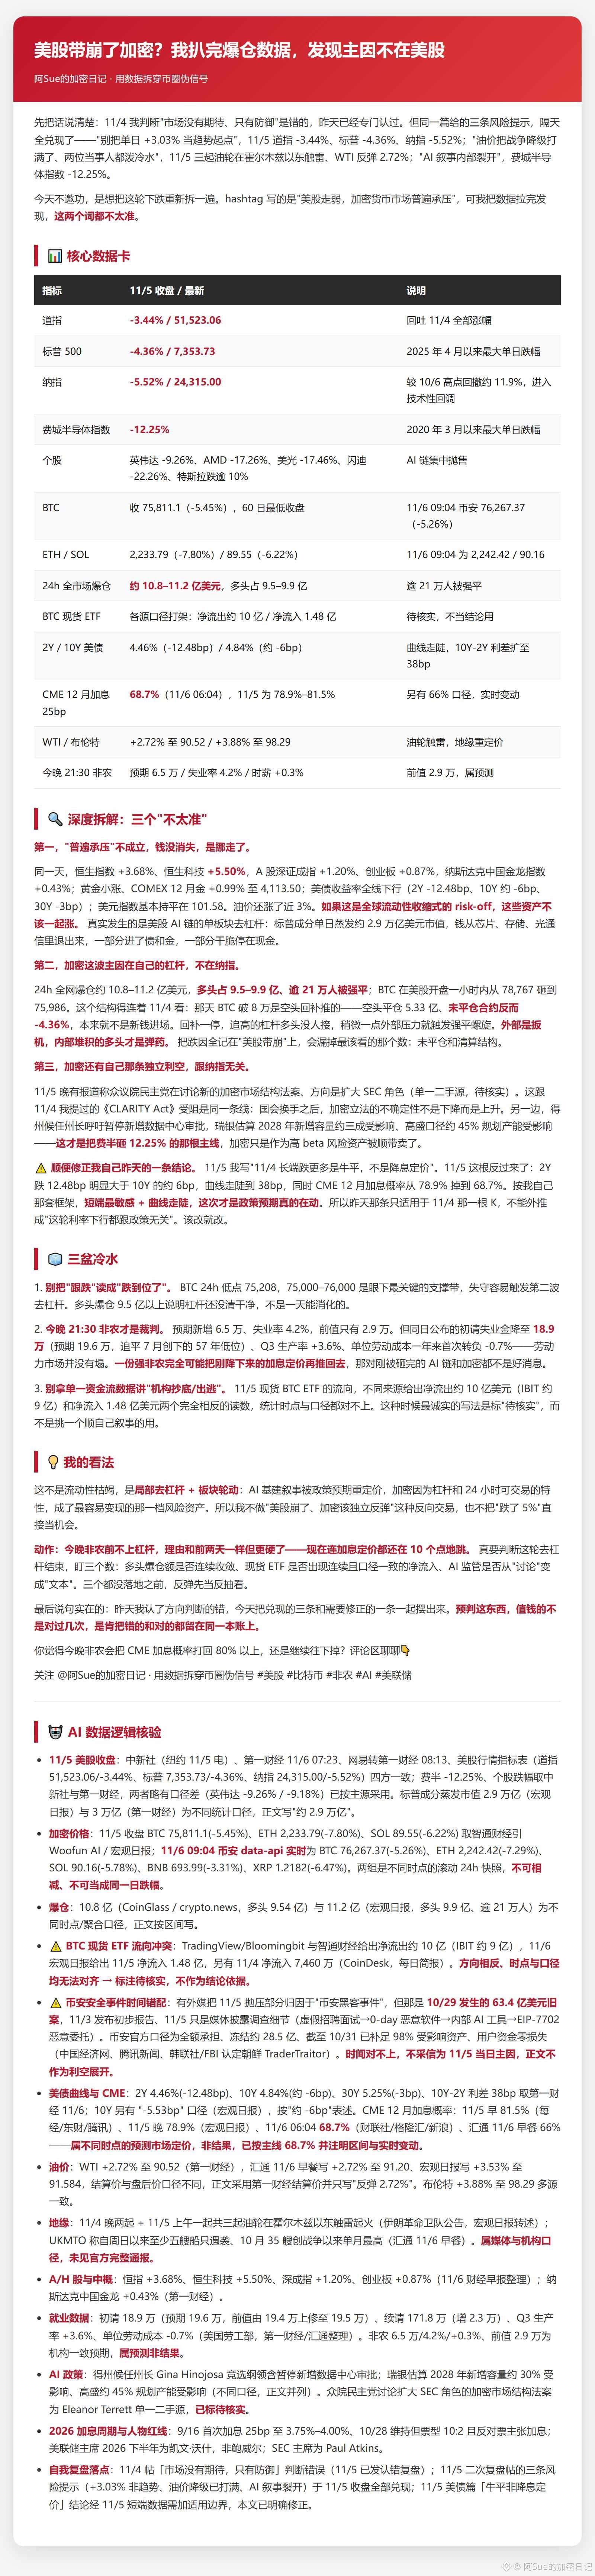
📊 Key data
· Dow -3.44%, S&P 500 -4.36%, Nasdaq -5.52%, Philadelphia Semiconductor Index -12.25%
· BTC closed at 75,811 (-5.45%, a 60-day low); at 09:04 on 11/6, it was 76,267
· ETH -7.80%, SOL -6.22%; about $1.1B liquidated in 24h, including $950M+ in longs
· 2Y yield fell 12.48 bp to 4.46%; 10Y fell about 6 bp; the yield curve steepened to 38 bp
· CME pricing for a December rate hike: 68.7% (78.9%–81.5% on 11/5); WTI +2.72%
🔍 The key contradictions
1: “Broad-based pressure” doesn’t hold up. On the same day, Hang Seng Tech rose 5.5%, gold gained, Treasury yields fell, and oil rose 3%. This was deleveraging in the AI sector, with money rotating into bonds and gold.
2: The main culprit was leverage within crypto. More than $950M in longs were liquidated in 24h, with 210,000 traders liquidated. BTC’s break above 80,000 on 11/4 was short covering (open interest -4.36%), not new money. Once the covering stopped, there was no one left to buy.
3: The Texas governor-elect’s call to halt data-center approvals was the main catalyst behind the Philadelphia Semiconductor Index’s -12.25% drop; House Democrats discussed expanding the SEC’s role (single-source claim, still to be verified). Crypto was sold off alongside other high-beta assets.
🧊 Three reality checks
1. Don’t mistake a drop in tandem for a completed sell-off. BTC’s 24h low was 75,208; a break below 75,000 could trigger a second wave of deleveraging.
2. Tonight’s 21:30 jobs report (65,000 / 4.2%) is the judge. Initial jobless claims matched a 57-year low of 189,000; a strong jobs report could push rate-hike pricing back up.
3. ETF flows are conflicting: about $1B in net outflows versus $148M in net inflows. Don’t cherry-pick whichever figure fits the narrative.
💡 My take
First, I need to correct myself: I wrote, “A bull steepening isn’t rate-cut pricing.” Today, the 2Y yield fell 12.48 bp—more than the 10Y’s 6 bp decline—the curve steepened, and the odds of a rate hike dropped 10 points. This time, the short end is pricing in policy. This view applies only to 11/4.
This isn’t a liquidity crunch; it’s localized deleveraging plus sector rotation. No leverage before the jobs report. Watch for three signals: long liquidations easing, ETF flow figures aligning, and AI regulation taking shape. Treat any rebound as a relief rally for now.
⚠️ Not investment advice. Probabilities can change at any time.
Do you think tonight’s jobs report will push the odds of a rate hike back above 80%, or will they keep falling? Share your thoughts in the comments 👇
Follow @阿Sue的加密日记 · Using data to expose crypto’s false signals
#USStocks #Bitcoin #JobsReport #AI #FederalReserve
On 11/4, I was wrong to say “defensive assets only”—I admitted it yesterday. But all three of my signals played out: +3.03% wasn’t a trend → Nasdaq -5.52%; oil downgraded → tanker stocks hit the rocks; AI cracks appeared → Philadelphia Semiconductor Index -12.25%.
📊 Key data
· Dow -3.44%, S&P 500 -4.36%, Nasdaq -5.52%, Philadelphia Semiconductor Index -12.25%
· BTC closed at 75,811 (-5.45%, a 60-day low); at 09:04 on 11/6, it was 76,267
· ETH -7.80%, SOL -6.22%; about $1.1B liquidated in 24h, including $950M+ in longs
· 2Y yield fell 12.48 bp to 4.46%; 10Y fell about 6 bp; the yield curve steepened to 38 bp
· CME pricing for a December rate hike: 68.7% (78.9%–81.5% on 11/5); WTI +2.72%
🔍 The key contradictions
1: “Broad-based pressure” doesn’t hold up. On the same day, Hang Seng Tech rose 5.5%, gold gained, Treasury yields fell, and oil rose 3%. This was deleveraging in the AI sector, with money rotating into bonds and gold.
2: The main culprit was leverage within crypto. More than $950M in longs were liquidated in 24h, with 210,000 traders liquidated. BTC’s break above 80,000 on 11/4 was short covering (open interest -4.36%), not new money. Once the covering stopped, there was no one left to buy.
3: The Texas governor-elect’s call to halt data-center approvals was the main catalyst behind the Philadelphia Semiconductor Index’s -12.25% drop; House Democrats discussed expanding the SEC’s role (single-source claim, still to be verified). Crypto was sold off alongside other high-beta assets.
🧊 Three reality checks
1. Don’t mistake a drop in tandem for a completed sell-off. BTC’s 24h low was 75,208; a break below 75,000 could trigger a second wave of deleveraging.
2. Tonight’s 21:30 jobs report (65,000 / 4.2%) is the judge. Initial jobless claims matched a 57-year low of 189,000; a strong jobs report could push rate-hike pricing back up.
3. ETF flows are conflicting: about $1B in net outflows versus $148M in net inflows. Don’t cherry-pick whichever figure fits the narrative.
💡 My take
First, I need to correct myself: I wrote, “A bull steepening isn’t rate-cut pricing.” Today, the 2Y yield fell 12.48 bp—more than the 10Y’s 6 bp decline—the curve steepened, and the odds of a rate hike dropped 10 points. This time, the short end is pricing in policy. This view applies only to 11/4.
This isn’t a liquidity crunch; it’s localized deleveraging plus sector rotation. No leverage before the jobs report. Watch for three signals: long liquidations easing, ETF flow figures aligning, and AI regulation taking shape. Treat any rebound as a relief rally for now.
⚠️ Not investment advice. Probabilities can change at any time.
Do you think tonight’s jobs report will push the odds of a rate hike back above 80%, or will they keep falling? Share your thoughts in the comments 👇
Follow @阿Sue的加密日记 · Using data to expose crypto’s false signals
#USStocks #Bitcoin #JobsReport #AI #FederalReserve