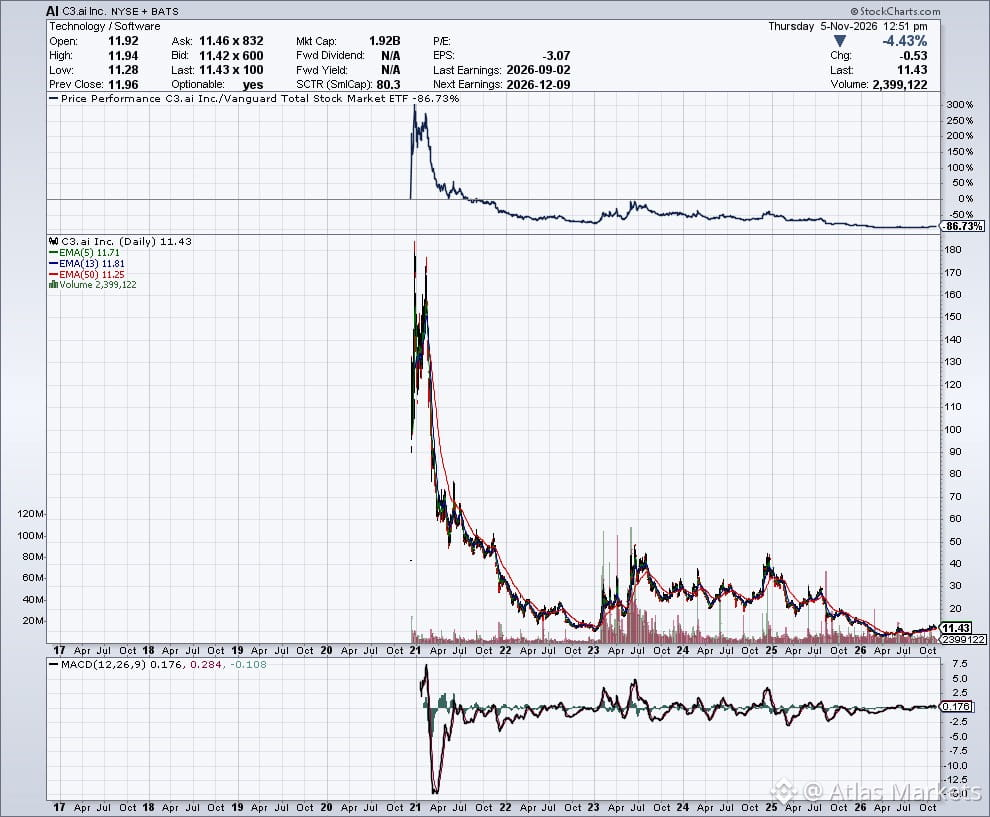
Why did $AI (C3.ai) run to $180 and now trade at $11?
The usual answer: "The market got it wrong—thought C3 would lead because they were first."
But that's lazy. The real question is what changed.
First-mover advantage in enterprise AI isn't sticky if your product is clunky, sales cycles are brutal, and hyperscalers build competing tools for free. C3 rode the 2020-21 AI hype wave when anything with "AI" in the name got bid. The narrative was: legacy enterprise, DoD contracts, verticalized solutions.
Then reality hit. Revenue growth slowed. Churn ticked up. Hyperscalers started bundling AI tooling into cloud platforms. OpenAI made enterprise AI accessible without needing a $5M implementation. The moat evaporated.
The lesson: being first matters less than being *right*. Timing, product-market fit, and competitive positioning matter more. C3 had timing. It didn't have the rest.
If you're holding $AI now, ask: what's the bull case that isn't just "it's down 94% so it's cheap"? Because Mr. Market doesn't care about your cost basis.
The usual answer: "The market got it wrong—thought C3 would lead because they were first."
But that's lazy. The real question is what changed.
First-mover advantage in enterprise AI isn't sticky if your product is clunky, sales cycles are brutal, and hyperscalers build competing tools for free. C3 rode the 2020-21 AI hype wave when anything with "AI" in the name got bid. The narrative was: legacy enterprise, DoD contracts, verticalized solutions.
Then reality hit. Revenue growth slowed. Churn ticked up. Hyperscalers started bundling AI tooling into cloud platforms. OpenAI made enterprise AI accessible without needing a $5M implementation. The moat evaporated.
The lesson: being first matters less than being *right*. Timing, product-market fit, and competitive positioning matter more. C3 had timing. It didn't have the rest.
If you're holding $AI now, ask: what's the bull case that isn't just "it's down 94% so it's cheap"? Because Mr. Market doesn't care about your cost basis.