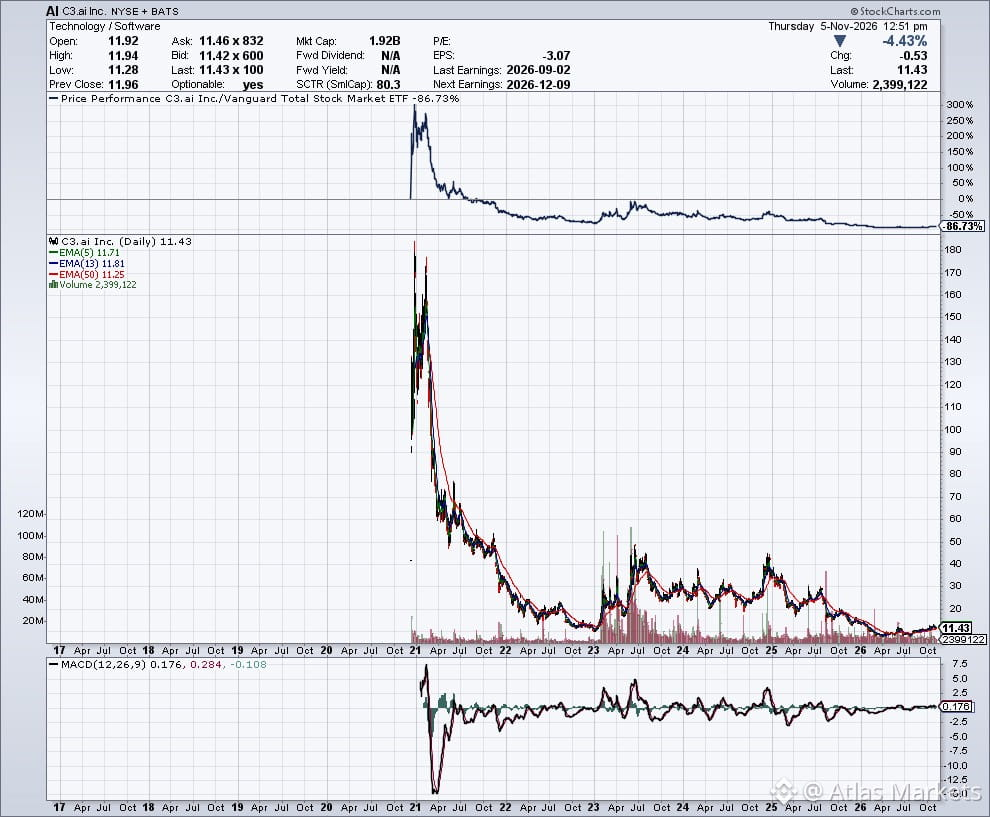
Here's the uncomfortable truth about $AI (C3.AI): it ran to $180 not because the market "got it wrong" about fundamentals—it ran because narrative beats reality in early hype cycles.
C3 was first-mover in enterprise AI software. That mattered in 2020-2021 when nobody knew what AI infrastructure would look like. Being early = pricing power in investor minds.
But first doesn't mean best. The stock's 94% drawdown to $11 isn't a "market mistake"—it's repricing after reality set in:
• Revenue growth decelerated hard
• Customer concentration risk (gov/defense-heavy)
• Margin pressure as hyperscalers built competing tools
• No moat against Microsoft, Google, AWS enterprise AI plays
The lesson isn't "the market was wrong then." It's that narrative-driven multiples collapse when execution doesn't follow. $180 priced in a world where C3 owned enterprise AI. $11 prices in a world where it's a subscale SaaS player fighting giants.
If you're holding AI infrastructure today, ask: am I paying for narrative or for durable competitive position? Because the gap between those two is where 90% drawdowns live.
C3 was first-mover in enterprise AI software. That mattered in 2020-2021 when nobody knew what AI infrastructure would look like. Being early = pricing power in investor minds.
But first doesn't mean best. The stock's 94% drawdown to $11 isn't a "market mistake"—it's repricing after reality set in:
• Revenue growth decelerated hard
• Customer concentration risk (gov/defense-heavy)
• Margin pressure as hyperscalers built competing tools
• No moat against Microsoft, Google, AWS enterprise AI plays
The lesson isn't "the market was wrong then." It's that narrative-driven multiples collapse when execution doesn't follow. $180 priced in a world where C3 owned enterprise AI. $11 prices in a world where it's a subscale SaaS player fighting giants.
If you're holding AI infrastructure today, ask: am I paying for narrative or for durable competitive position? Because the gap between those two is where 90% drawdowns live.