The most counterintuitive point: the bet now isn’t on a rate cut, but a rate hike—the probability of a 25-basis-point hike in December is 81.5%, while a cut is nowhere in sight.
Why? Employment hasn’t collapsed (October ADP payrolls rose by 86,000, beating expectations; November 6 nonfarm payrolls are forecast at 65,000), and inflation is still hot (September CPI was 3.7%, core PCE 3.1%). The Fed just raised rates once in September, and officials are still calling for another hike.
The November 10 CPI report will cover October, when oil prices were high, so it’s unlikely to show much cooling either.
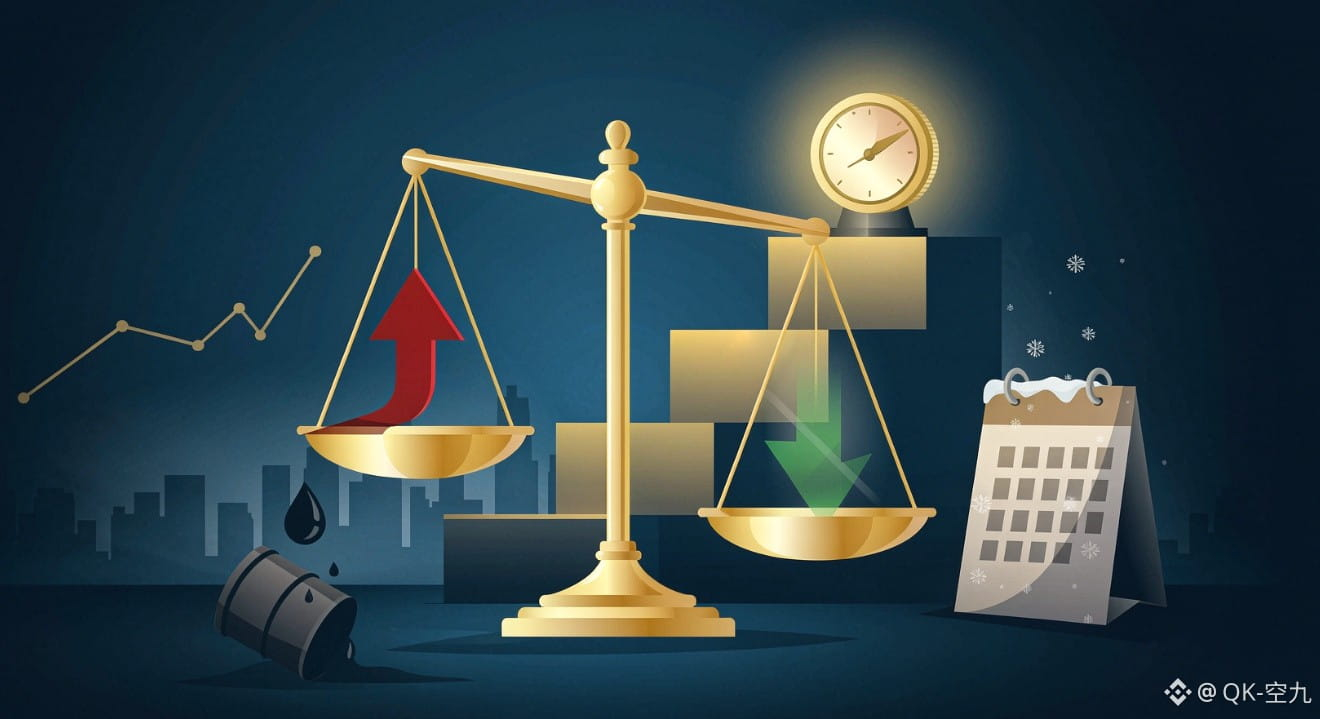
The key timing gap: oil prices plunged 8% in early November, but that won’t show up until the December 10 CPI report. The December 9 meeting will already be over, so policymakers won’t see it.
My assessment: about a 70% chance of a hike, 30% chance of no change, and roughly 0% chance of a cut. If you’re waiting for monetary easing, look to 2027.
For now, the dollar and Treasury yields are more likely to rise than fall. Don’t rush to buy the dip in gold or long-term bonds. #美国中期选举:市场有哪些期待? #美国10月非农出炉:降息还有戏吗?
Why? Employment hasn’t collapsed (October ADP payrolls rose by 86,000, beating expectations; November 6 nonfarm payrolls are forecast at 65,000), and inflation is still hot (September CPI was 3.7%, core PCE 3.1%). The Fed just raised rates once in September, and officials are still calling for another hike.
The November 10 CPI report will cover October, when oil prices were high, so it’s unlikely to show much cooling either.
The key timing gap: oil prices plunged 8% in early November, but that won’t show up until the December 10 CPI report. The December 9 meeting will already be over, so policymakers won’t see it.
My assessment: about a 70% chance of a hike, 30% chance of no change, and roughly 0% chance of a cut. If you’re waiting for monetary easing, look to 2027.
For now, the dollar and Treasury yields are more likely to rise than fall. Don’t rush to buy the dip in gold or long-term bonds. #美国中期选举:市场有哪些期待? #美国10月非农出炉:降息还有戏吗?