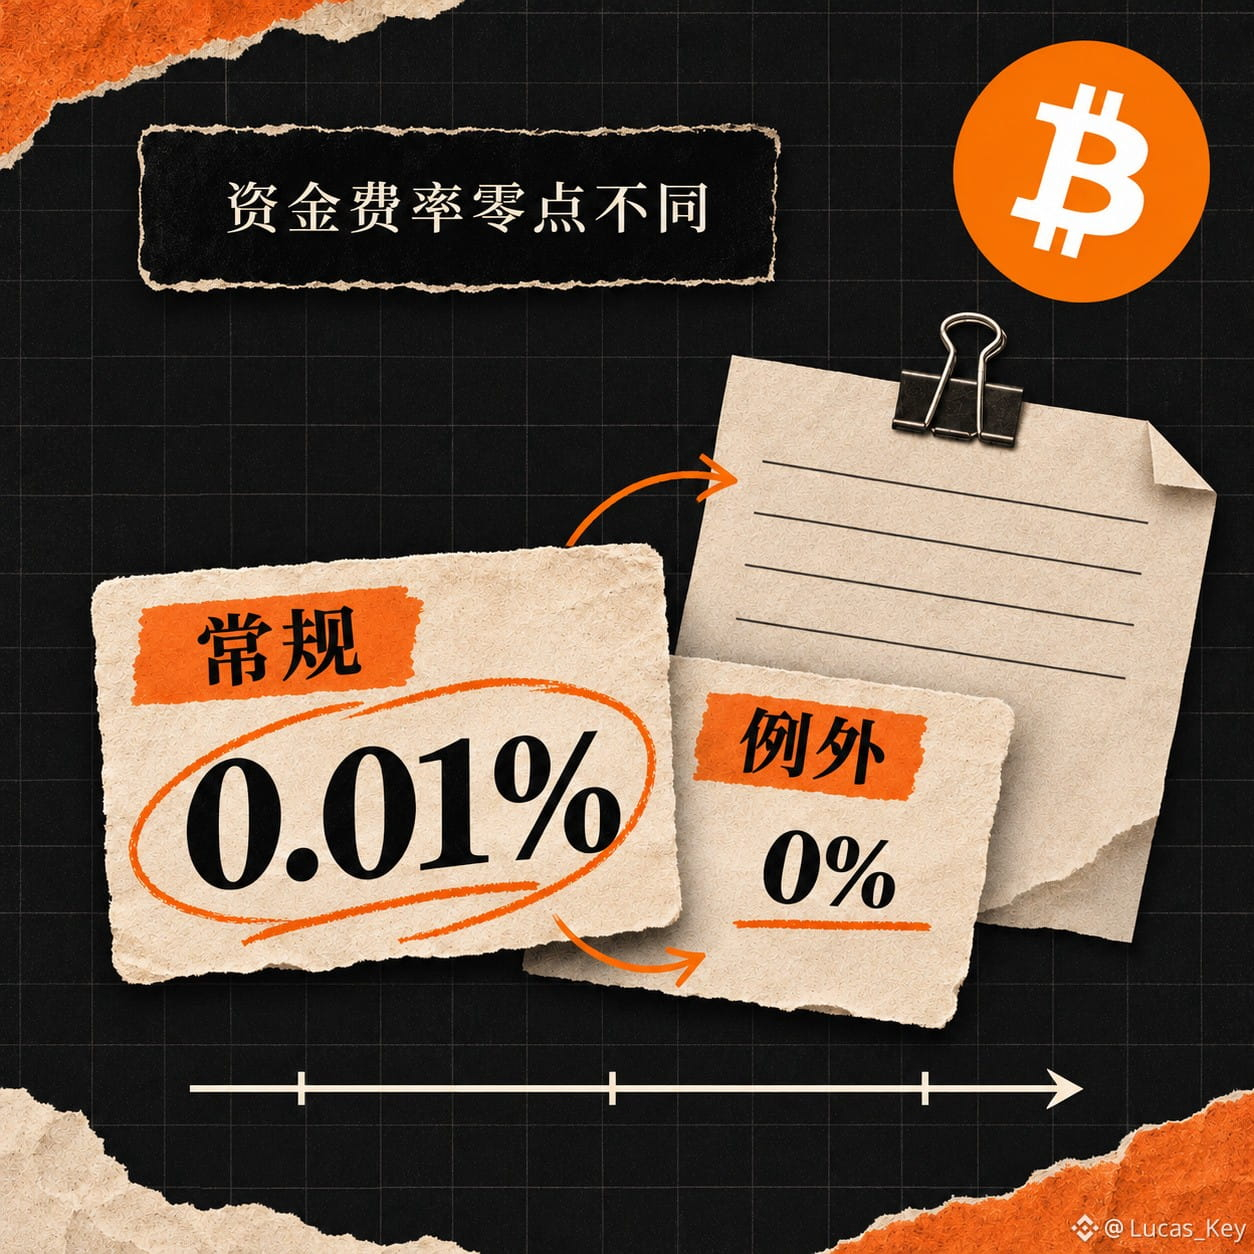
Funding rates are the same kind of metric, but you can't judge which side of the $BTC , $ETH , and $BNB contracts is more crowded just by looking at whether the rate is positive or negative. In the perpetual contract formula Binance updated in September 2025, the interest rate parameter for standard contracts is 0.01% every 8 hours, while BNBUSDT’s is 0%. These are formula parameters, not the actual funding rates displayed on screen today.
Assuming the premium index is exactly zero and the settlement interval remains 8 hours, the formula puts BTCUSDT and ETHUSDT at a 0.01% baseline, while BNBUSDT is at 0%. So saying “longs are overheated” when you see a slightly positive BTC rate, or “nobody is going long” when you see a zero BNB rate, could both lead to a misreading of the contract structure. To determine whether a payment actually occurs, you also need to consider the premium index for that period, the actual rate, and whether you hold a position at settlement.
For example, with a notional position of 10,000 USDT, if the actual funding rate for a period is 0.01%, the funding payment for that period is 1 USDT, transferred between longs and shorts according to the direction of the rate. This is only an illustration of the calculation and does not represent the actual rates of the three contracts right now. When comparing sentiment for BTC, ETH, and BNB, I’d rather first check each contract’s parameters, then see whether actual rates over several consecutive periods and open interest are changing together. Refer to the Binance contract pages for the current data and rules; leverage magnifies losses, so don’t open a position based on a single indicator.
Assuming the premium index is exactly zero and the settlement interval remains 8 hours, the formula puts BTCUSDT and ETHUSDT at a 0.01% baseline, while BNBUSDT is at 0%. So saying “longs are overheated” when you see a slightly positive BTC rate, or “nobody is going long” when you see a zero BNB rate, could both lead to a misreading of the contract structure. To determine whether a payment actually occurs, you also need to consider the premium index for that period, the actual rate, and whether you hold a position at settlement.
For example, with a notional position of 10,000 USDT, if the actual funding rate for a period is 0.01%, the funding payment for that period is 1 USDT, transferred between longs and shorts according to the direction of the rate. This is only an illustration of the calculation and does not represent the actual rates of the three contracts right now. When comparing sentiment for BTC, ETH, and BNB, I’d rather first check each contract’s parameters, then see whether actual rates over several consecutive periods and open interest are changing together. Refer to the Binance contract pages for the current data and rules; leverage magnifies losses, so don’t open a position based on a single indicator.