My observation is that this selloff in mining companies shifting to AI leasing looks more like a repricing of financing costs and policy risks than a collapse in lease demand. Whether this view holds depends on whether signed leases are canceled, whether financing conditions continue to tighten, and whether Texas power and permitting risks spread to more projects.
First, the facts. According to a PANews report citing VanEck research, Bitcoin mining companies transitioning to leasing AI data center infrastructure saw their share prices fall by an average of about 35% in October, but signed leases were not canceled and demand signals continued to strengthen. VanEck attributed the selloff to rising financing costs and macroeconomic sentiment, and said the market was undervaluing the worth of long-term leases. The report also noted that the bottleneck for AI infrastructure is power, not chips, and that these mining companies typically sign 10- to 20-year leases with investment-grade tenants. Based on 2028 EBITDA, their valuations are about half those of data center REITs. CoinDesk reported that the Texas election results introduced new uncertainty around power access and construction permits for miners transitioning to AI, and that companies with already approved projects could benefit from tighter supply.
Based on this, I infer that the market is pricing “contracted cash flows” and “expansion options” separately. Signed long-term leases represent relatively certain revenue, but the falling share prices show that investors are more concerned about discount rates and regulatory hurdles. When financing costs rise and permitting uncertainty increases, the expansion story gets marked down, while the leases themselves do not necessarily deteriorate in tandem. My observation is that if the leases remain in force, the current decline reflects a higher risk premium rather than a refutation of demand.
In different scenarios, if leases are canceled or tenants default, the view above no longer holds. If financing costs decline and project permits move forward, the valuation gap may narrow. If Texas-related risks spread to other states, the repricing will last longer.
Worth watching: whether leases are canceled, changes in financing costs, and progress on project permits. This article does not constitute investment advice.
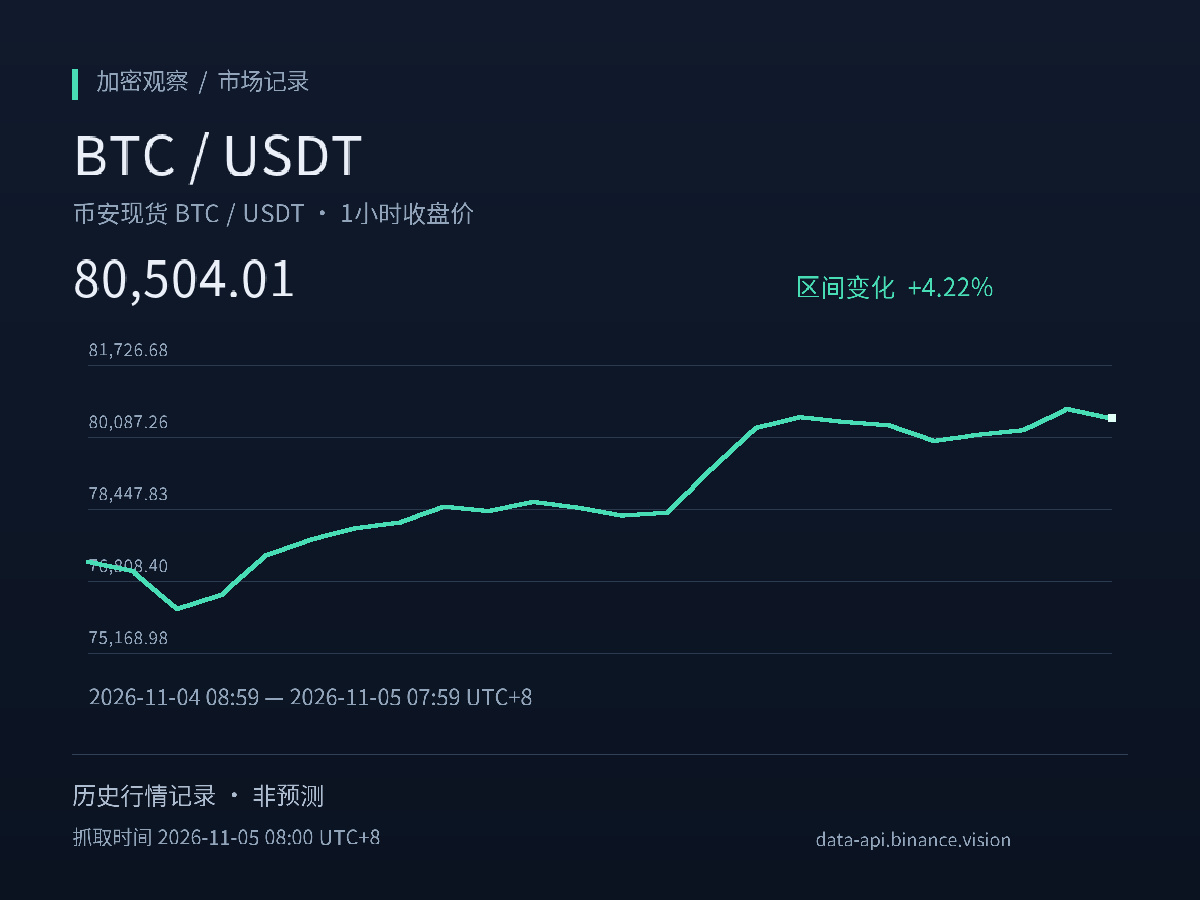
$BTC
#BTC #Macroeconomics
Sources:
PANews (originally published 11-05 07:57 Beijing time)
https://www.panewslab.com/zh/articles/01a1a8fe-cfb5-71a6-9449-648405cb150f
CoinDesk (originally published 11-05 00:08 Beijing time)
https://www.coindesk.com/markets/2026/11/04/wall-street-cuts-bitcoin-miner-price-targets-after-democrats-texas-win-threatens-ai-data-center-boom
First, the facts. According to a PANews report citing VanEck research, Bitcoin mining companies transitioning to leasing AI data center infrastructure saw their share prices fall by an average of about 35% in October, but signed leases were not canceled and demand signals continued to strengthen. VanEck attributed the selloff to rising financing costs and macroeconomic sentiment, and said the market was undervaluing the worth of long-term leases. The report also noted that the bottleneck for AI infrastructure is power, not chips, and that these mining companies typically sign 10- to 20-year leases with investment-grade tenants. Based on 2028 EBITDA, their valuations are about half those of data center REITs. CoinDesk reported that the Texas election results introduced new uncertainty around power access and construction permits for miners transitioning to AI, and that companies with already approved projects could benefit from tighter supply.
Based on this, I infer that the market is pricing “contracted cash flows” and “expansion options” separately. Signed long-term leases represent relatively certain revenue, but the falling share prices show that investors are more concerned about discount rates and regulatory hurdles. When financing costs rise and permitting uncertainty increases, the expansion story gets marked down, while the leases themselves do not necessarily deteriorate in tandem. My observation is that if the leases remain in force, the current decline reflects a higher risk premium rather than a refutation of demand.
In different scenarios, if leases are canceled or tenants default, the view above no longer holds. If financing costs decline and project permits move forward, the valuation gap may narrow. If Texas-related risks spread to other states, the repricing will last longer.
Worth watching: whether leases are canceled, changes in financing costs, and progress on project permits. This article does not constitute investment advice.
$BTC
#BTC #Macroeconomics
Sources:
PANews (originally published 11-05 07:57 Beijing time)
https://www.panewslab.com/zh/articles/01a1a8fe-cfb5-71a6-9449-648405cb150f
CoinDesk (originally published 11-05 00:08 Beijing time)
https://www.coindesk.com/markets/2026/11/04/wall-street-cuts-bitcoin-miner-price-targets-after-democrats-texas-win-threatens-ai-data-center-boom