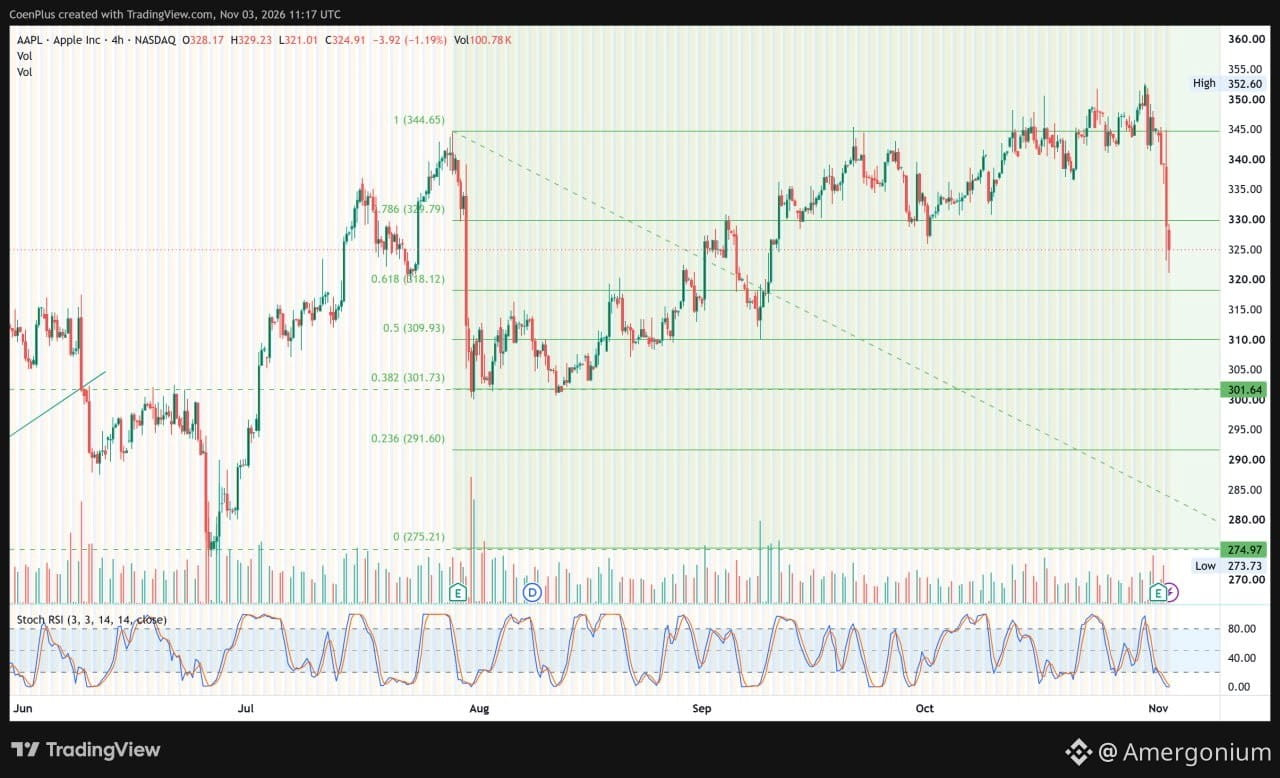
#Apple: strong report and a 5% drop.
Quarter: results beat expectations
revenue 114.5B (+12%),
EPS 2.10 vs. forecast of 1.99, a record year.
iPhone 57.6B (+17%), Mac 10.8B (+24%), Services 31.6B (+10%, in line with expectations)
iPad 6.23B vs. expectations of 6.83
Wearables 8.3B vs. expectations of 8.99B
China +21% YoY, a quarterly record, but below expectations
Full 2026 fiscal year: revenue 478.8B (+15%), EPS 8.98 (+20%).
October–December outlook: the main reason for the drop
For the holiday quarter, Apple forecasts revenue growth of 7–10%, but gross margin of only 45–46% vs. 48.2% a year ago.
Expenses are meanwhile growing by 11–13%.
As a result, revenue will rise by around 8%, and EPS by around 2%. At a valuation of 34 times forward annual earnings, that’s not enough.
Scenarios through the end of 2026:
Base 55%
range 305–345$
Negative 25%
285–304$
Positive: 20%
345–362$AAPLB
Quarter: results beat expectations
revenue 114.5B (+12%),
EPS 2.10 vs. forecast of 1.99, a record year.
iPhone 57.6B (+17%), Mac 10.8B (+24%), Services 31.6B (+10%, in line with expectations)
iPad 6.23B vs. expectations of 6.83
Wearables 8.3B vs. expectations of 8.99B
China +21% YoY, a quarterly record, but below expectations
Full 2026 fiscal year: revenue 478.8B (+15%), EPS 8.98 (+20%).
October–December outlook: the main reason for the drop
For the holiday quarter, Apple forecasts revenue growth of 7–10%, but gross margin of only 45–46% vs. 48.2% a year ago.
Expenses are meanwhile growing by 11–13%.
As a result, revenue will rise by around 8%, and EPS by around 2%. At a valuation of 34 times forward annual earnings, that’s not enough.
Scenarios through the end of 2026:
Base 55%
range 305–345$
Negative 25%
285–304$
Positive: 20%
345–362$AAPLB