PLTR revenue up 96%, yet the stock got dumped 10%—what was the point of that earnings report?
I think this sell-off is a bit unfair. I'm siding with the bulls.
First, the numbers: saying everything beat expectations isn't just a polite way of putting it.
Third-quarter revenue was $2.313 billion, up 96% year over year, versus expectations of $2.18 billion.
Adjusted EPS was $0.44, also above expectations of $0.41.
U.S. commercial revenue was $984 million, up 148% year over year, surpassing government revenue of $953 million for the first time.
Fourth-quarter guidance came in at $2.65 billion, versus expectations of just $2.46 billion.
Full-year guidance was raised straight to $8.53 billion, above the $8.2 billion expected—that's another step up.
So what happened? The stock fell 3.13% in regular trading on Monday, closing at $178.34.
After earnings came out, it initially jumped 4% after hours, then gave it all back before long.
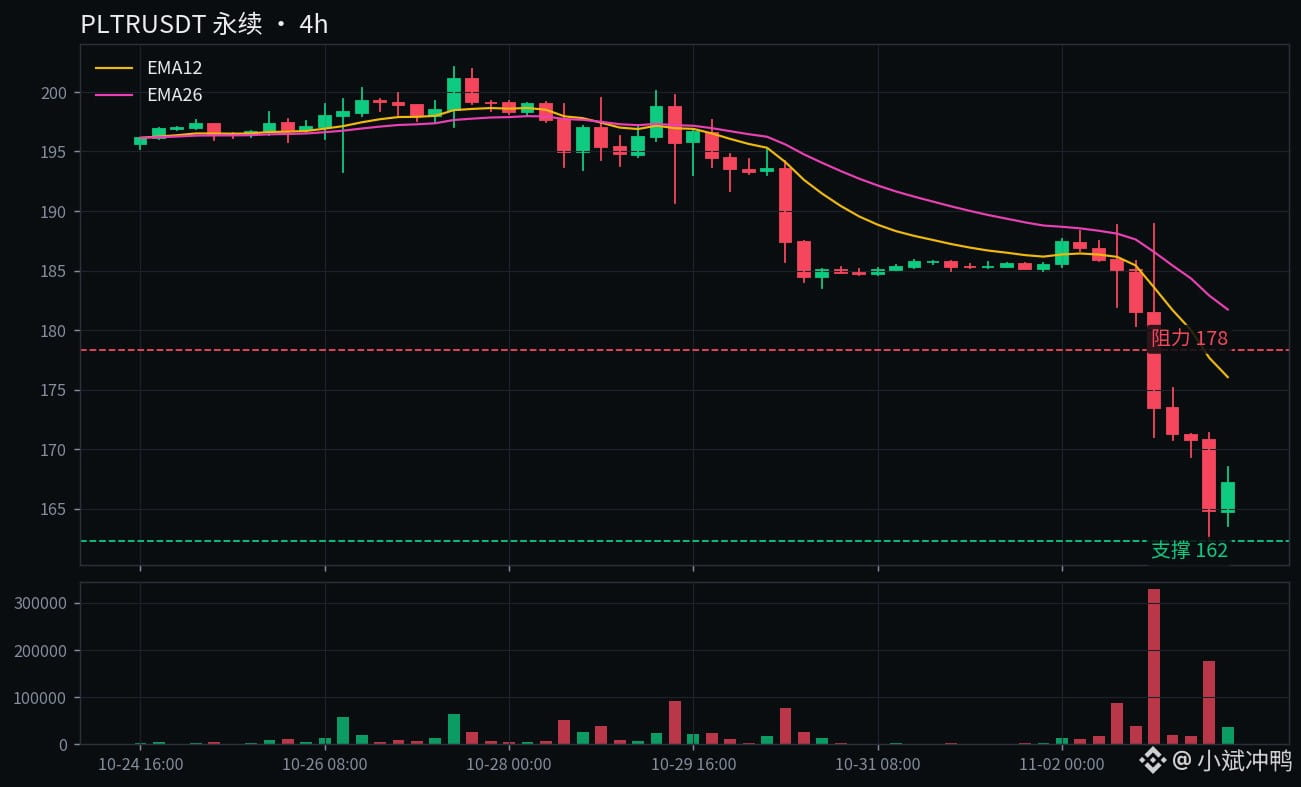
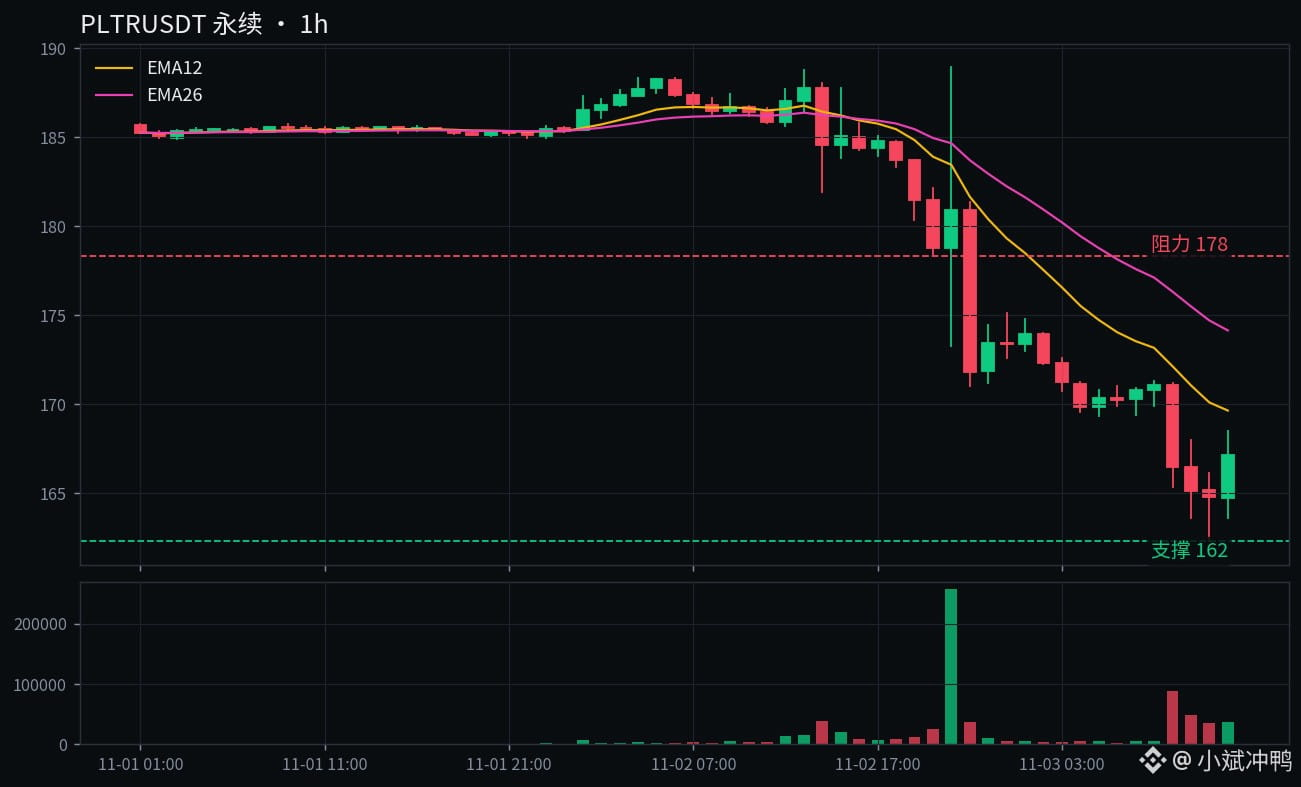
This morning, it was down as much as 8% premarket. The token was down 10.7% over 24 hours, with the price now at $167.07.
The 24-hour low was $162.30, and trading volume was $122 million—volume really picked up.
What do the bulls say? The numbers didn't fall apart, and guidance was raised across the board.
Analyst consensus is still “Buy,” with an average price target of $216—about 30% above the current price.
U.S. commercial revenue surpassing government revenue for the first time isn't just a lucky quarter; the business mix is changing.
The stock was still trading above $210 in early October. The fundamentals haven't changed; the price has simply come back down.
What do the bears say? They have a point, too.
Growth in total commercial contract value plunged from +153% last quarter to +11%. That's the most glaring red flag in the earnings report.
The forward P/E is 97x, compared with a normal range of just 15 to 20x. The valuation really is stretched.
On top of that, concerns about the returns on AI spending are spreading. After Meta and Google, the market has little patience for richly valued AI stocks.
There's another factor: tonight is midterm election vote-counting night, so volatility is high to begin with.
Apple also fell 2.7% after hours the same night after giving weak holiday-quarter gross margin guidance. AI stocks are getting hit as a group.
My take: contract growth really has slowed, but this is a stock with revenue up 96% and guidance raised across the board.
Pushing it right to the $160 support level premarket isn't pricing fundamentals—it's pricing sentiment.
$160 was the starting point of this October rally. If it holds, it can serve as an anchor for an oversold bounce.
If it breaks, the bulls will have to rewrite their story. I accept that condition.
There are two scenarios.
If it gets back above $178.34, Monday's closing price, that signals the bleeding has stopped; then watch $183 to $185.
If it breaks below today's low of $162.30, watch the $160 support level.
If $160 breaks too, the whole thesis is invalidated. The most bearish scenario sees $100—that's the other side's extreme case. I don't agree with it, but we need to know that level is out there.
Put simply, a stock delivers a perfect earnings report and still gets hammered—either it's genuinely too expensive, or sentiment has gone too far.
I'm betting on the latter. Until the numbers crack, I'll treat this as an unjustified sell-off.
Will it get back above $178.34 and bounce, or break below $162.30 and head for $160 support?
I'm betting on the former. What about you?
$PLTR $AAPL
#美股 #earnings
I think this sell-off is a bit unfair. I'm siding with the bulls.
First, the numbers: saying everything beat expectations isn't just a polite way of putting it.
Third-quarter revenue was $2.313 billion, up 96% year over year, versus expectations of $2.18 billion.
Adjusted EPS was $0.44, also above expectations of $0.41.
U.S. commercial revenue was $984 million, up 148% year over year, surpassing government revenue of $953 million for the first time.
Fourth-quarter guidance came in at $2.65 billion, versus expectations of just $2.46 billion.
Full-year guidance was raised straight to $8.53 billion, above the $8.2 billion expected—that's another step up.
So what happened? The stock fell 3.13% in regular trading on Monday, closing at $178.34.
After earnings came out, it initially jumped 4% after hours, then gave it all back before long.
This morning, it was down as much as 8% premarket. The token was down 10.7% over 24 hours, with the price now at $167.07.
The 24-hour low was $162.30, and trading volume was $122 million—volume really picked up.
What do the bulls say? The numbers didn't fall apart, and guidance was raised across the board.
Analyst consensus is still “Buy,” with an average price target of $216—about 30% above the current price.
U.S. commercial revenue surpassing government revenue for the first time isn't just a lucky quarter; the business mix is changing.
The stock was still trading above $210 in early October. The fundamentals haven't changed; the price has simply come back down.
What do the bears say? They have a point, too.
Growth in total commercial contract value plunged from +153% last quarter to +11%. That's the most glaring red flag in the earnings report.
The forward P/E is 97x, compared with a normal range of just 15 to 20x. The valuation really is stretched.
On top of that, concerns about the returns on AI spending are spreading. After Meta and Google, the market has little patience for richly valued AI stocks.
There's another factor: tonight is midterm election vote-counting night, so volatility is high to begin with.
Apple also fell 2.7% after hours the same night after giving weak holiday-quarter gross margin guidance. AI stocks are getting hit as a group.
My take: contract growth really has slowed, but this is a stock with revenue up 96% and guidance raised across the board.
Pushing it right to the $160 support level premarket isn't pricing fundamentals—it's pricing sentiment.
$160 was the starting point of this October rally. If it holds, it can serve as an anchor for an oversold bounce.
If it breaks, the bulls will have to rewrite their story. I accept that condition.
There are two scenarios.
If it gets back above $178.34, Monday's closing price, that signals the bleeding has stopped; then watch $183 to $185.
If it breaks below today's low of $162.30, watch the $160 support level.
If $160 breaks too, the whole thesis is invalidated. The most bearish scenario sees $100—that's the other side's extreme case. I don't agree with it, but we need to know that level is out there.
Put simply, a stock delivers a perfect earnings report and still gets hammered—either it's genuinely too expensive, or sentiment has gone too far.
I'm betting on the latter. Until the numbers crack, I'll treat this as an unjustified sell-off.
Will it get back above $178.34 and bounce, or break below $162.30 and head for $160 support?
I'm betting on the former. What about you?
$PLTR $AAPL
#美股 #earnings