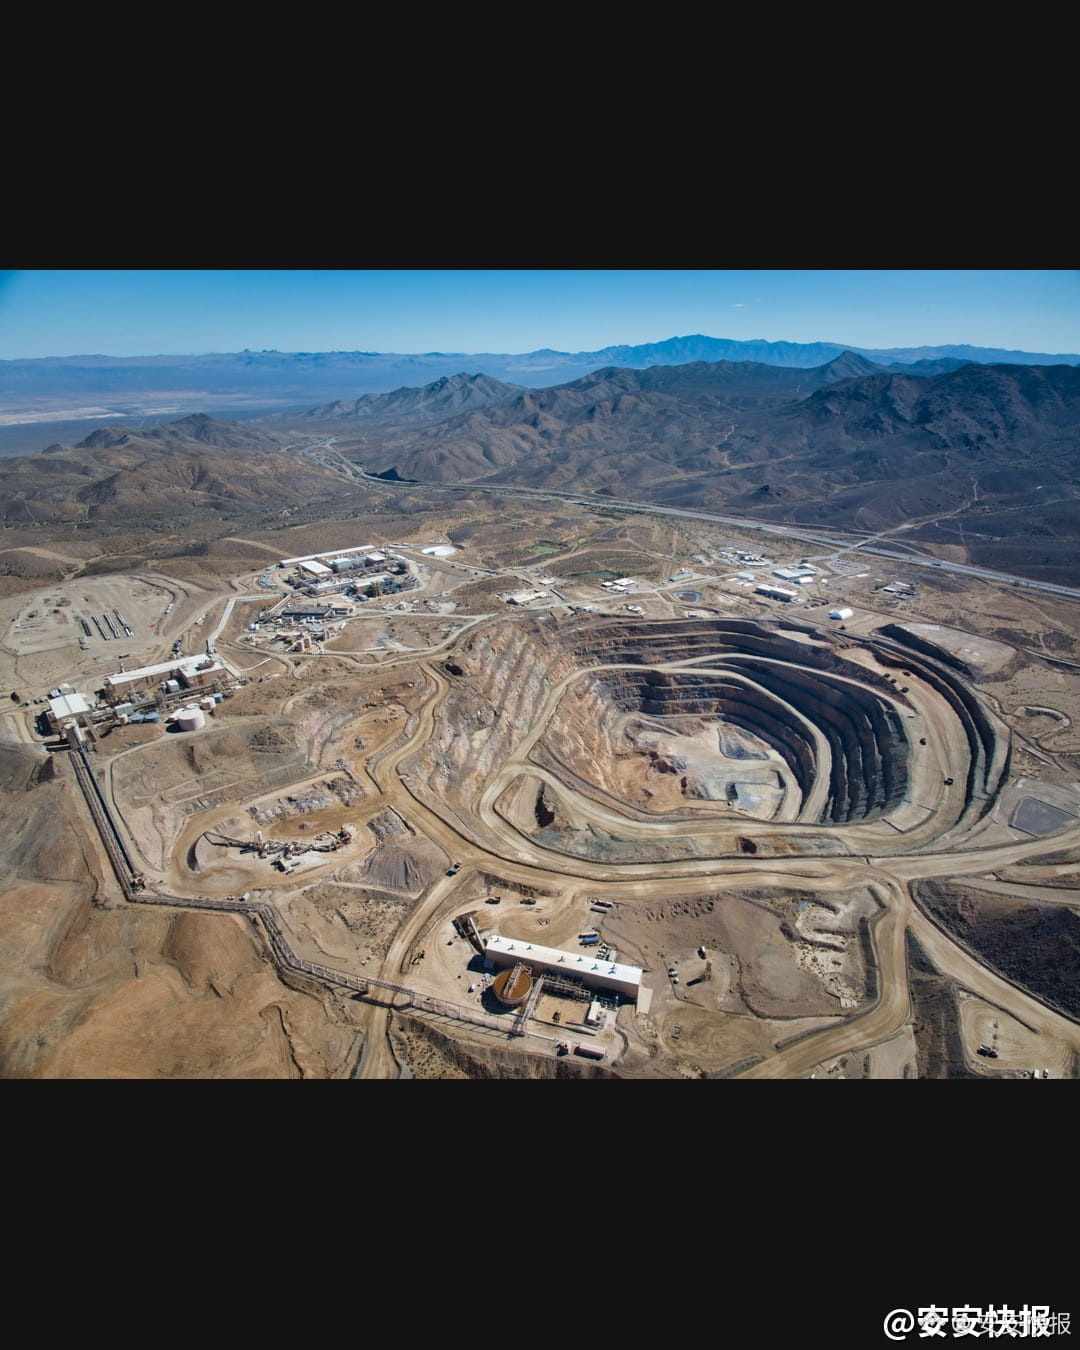
Revenue is expected to more than double, while losses narrow to just the one-cent range—but the most accurate analysts have already lowered their estimates.
MP Materials $MP will report its 2026 Q3 results after the U.S. market closes on Nov. 5. The earnings call is scheduled for 17:00 Eastern Time (06:00 Beijing time on Nov. 6).
Consensus estimates call for a loss of about $0.01 to $0.023 per share, down from a loss of $0.10 in the same period last year—a narrowing of roughly 90%. Revenue is expected to be about $117 million to $117.5 million, up around 118.6% year over year from about $53.55 million.
But consensus reflects estimates that have been cut by about 50% over the past 30 days. The most accurate estimates are even lower than consensus: Zacks ESP is -66.67%, with a Rank of 5.
Last quarter, the company posted a loss of $0.01 per share and revenue of about $108.5 million, up roughly 89% year over year.
What to watch: The key question in this report isn’t whether the company is profitable, but whether it can keep its loss within the one-cent range—and whether a doubling of revenue is genuinely backed by volume. A beat, with management clarifying neodymium-praseodymium output and realized prices on the call, could keep the rare-earths story going. If results are roughly in line with consensus but output or prices fall short, treat it as a routine delivery of expectations and don’t rush to chase the first after-hours move. If revenue comes in near the low end of the range, or losses widen again, reassess with less room for error; wait for the call to break down output, realized prices, and full-year guidance.
Data as of: 2026-11-03 07:17 UTC
For informational purposes only; not investment advice.
MP Materials $MP will report its 2026 Q3 results after the U.S. market closes on Nov. 5. The earnings call is scheduled for 17:00 Eastern Time (06:00 Beijing time on Nov. 6).
Consensus estimates call for a loss of about $0.01 to $0.023 per share, down from a loss of $0.10 in the same period last year—a narrowing of roughly 90%. Revenue is expected to be about $117 million to $117.5 million, up around 118.6% year over year from about $53.55 million.
But consensus reflects estimates that have been cut by about 50% over the past 30 days. The most accurate estimates are even lower than consensus: Zacks ESP is -66.67%, with a Rank of 5.
Last quarter, the company posted a loss of $0.01 per share and revenue of about $108.5 million, up roughly 89% year over year.
What to watch: The key question in this report isn’t whether the company is profitable, but whether it can keep its loss within the one-cent range—and whether a doubling of revenue is genuinely backed by volume. A beat, with management clarifying neodymium-praseodymium output and realized prices on the call, could keep the rare-earths story going. If results are roughly in line with consensus but output or prices fall short, treat it as a routine delivery of expectations and don’t rush to chase the first after-hours move. If revenue comes in near the low end of the range, or losses widen again, reassess with less room for error; wait for the call to break down output, realized prices, and full-year guidance.
Data as of: 2026-11-03 07:17 UTC
For informational purposes only; not investment advice.