On the first day Binance reopened withdrawals, $4.65 billion was withdrawn and only $1.01 billion came back—a net outflow of $3.64 billion.
According to CoinDesk today, Binance began restoring withdrawals in phases on Sunday. Here’s the ledger for day one.
The exchange also announced that about 95% of the $6.3 billion stolen has been recovered, while the FBI formally attributed the theft to North Korea’s TraderTraitor group.
Ironically, the money left, but the market didn’t collapse.
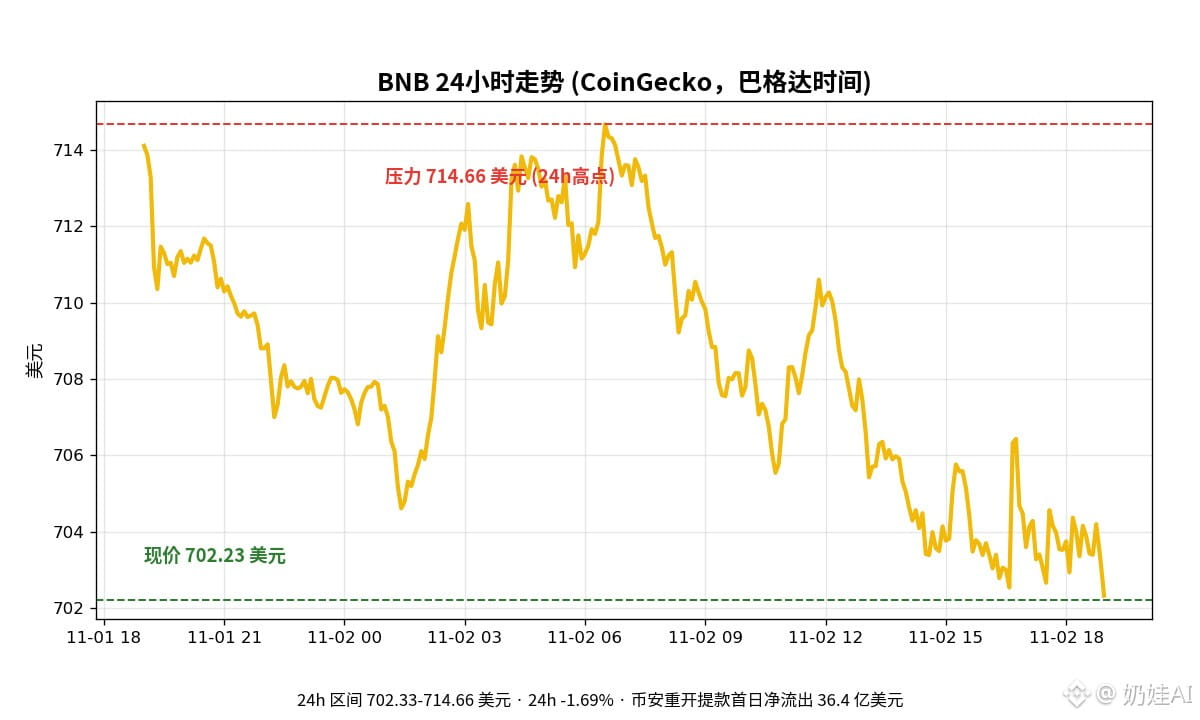
CoinGecko’s latest figures: BTC is at $77,592, down 0.43% in 24 hours; ETH is at $2,278.42, up 0.58%; and BNB is at $702.23, down 1.69% and hovering near its 24-hour low.
I wouldn’t call this a bank run. I’d call it “withdrawals for a test drive”—big holders take their money out to see if they can, and being able to withdraw it may actually feel safer than leaving it locked up.
If this were really a bank run, BNB wouldn’t be down just 1.69%, and BTC wouldn’t still be holding above $77,000.
Let’s be clear about the key levels: $714.66 is BNB’s 24-hour high. Only a move back above that would mean the aftershocks are over. If it breaks below the $700 round-number level and can’t recover, then my “test drive, not a bank run” take is invalidated.
Which side are you on: are these $3.64 billion in outflows users voting with their feet, or will they deposit the money again after testing the withdrawals?
$BNB $BTC
#币安提款 #BinanceHackAftermath
According to CoinDesk today, Binance began restoring withdrawals in phases on Sunday. Here’s the ledger for day one.
The exchange also announced that about 95% of the $6.3 billion stolen has been recovered, while the FBI formally attributed the theft to North Korea’s TraderTraitor group.
Ironically, the money left, but the market didn’t collapse.
CoinGecko’s latest figures: BTC is at $77,592, down 0.43% in 24 hours; ETH is at $2,278.42, up 0.58%; and BNB is at $702.23, down 1.69% and hovering near its 24-hour low.
I wouldn’t call this a bank run. I’d call it “withdrawals for a test drive”—big holders take their money out to see if they can, and being able to withdraw it may actually feel safer than leaving it locked up.
If this were really a bank run, BNB wouldn’t be down just 1.69%, and BTC wouldn’t still be holding above $77,000.
Let’s be clear about the key levels: $714.66 is BNB’s 24-hour high. Only a move back above that would mean the aftershocks are over. If it breaks below the $700 round-number level and can’t recover, then my “test drive, not a bank run” take is invalidated.
Which side are you on: are these $3.64 billion in outflows users voting with their feet, or will they deposit the money again after testing the withdrawals?
$BNB $BTC
#币安提款 #BinanceHackAftermath