
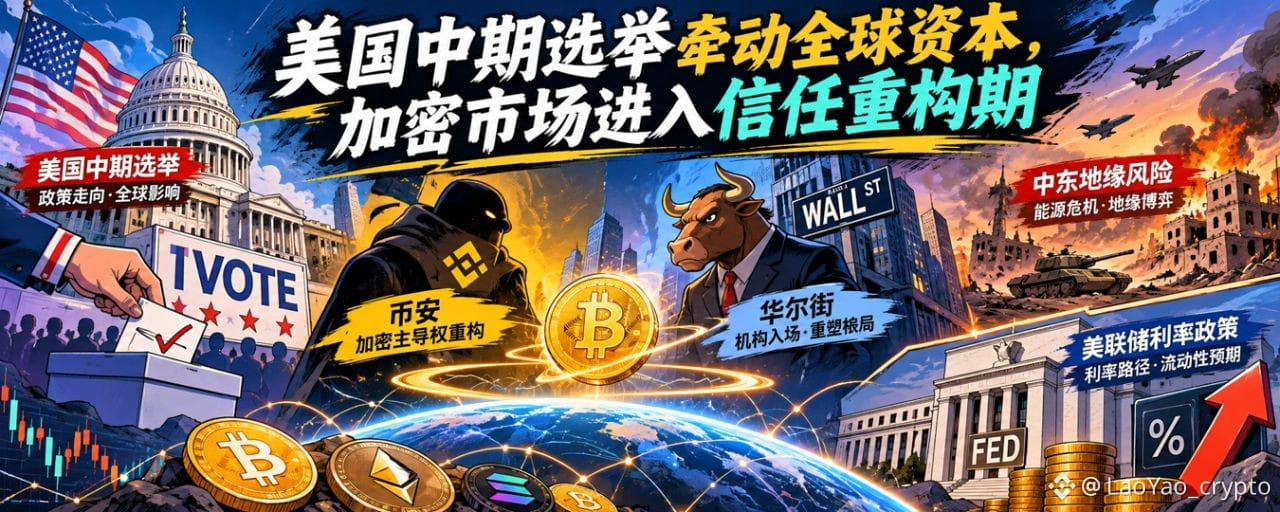
A new week brings two key variables to global capital markets: the U.S. midterm elections and the October nonfarm payrolls report.
If the nonfarm payrolls report determines market expectations for the Fed’s December policy path, the U.S. midterm elections could influence fiscal policy, the tariff system, industrial policy, and the global geopolitical landscape over the next two years.
This week, three key themes converge: the political cycle, monetary policy, and technology capital:
Political developments: The U.S. midterm elections are entering their final stretch, and the battle for control of Congress could reshape policy expectations for the next two years.
Monetary policy: U.S. October nonfarm payrolls and ISM manufacturing and services data will shape market views on labor market resilience, inflationary pressures, and the Fed’s December policy decision.
Technology: Tech giants including Apple and AMD are reporting earnings, putting AI industry capital expenditure and commercial returns under continued market scrutiny.
International developments: The Middle East situation, policy decisions by the Reserve Bank of Australia and the Bank of England, and China’s PMI and foreign exchange reserve data are all shaping global risk appetite.
Note that the United States has switched to standard time, so the Beijing times for major U.S. economic data releases are one hour later than before this week.
Meanwhile, potential risks in AI trading are also building.
Investors are beginning to buy insurance against the massive AI trade. Complex financing networks, supplier financing models, and the actual returns on AI capital expenditure are emerging as new concerns for tech stock valuations.
Crypto markets are in a recovery phase following the Binance hack.
BTC and ETH have rebounded modestly, but risk appetite has clearly contracted, with safe-haven funds concentrating more in Bitcoin and stablecoins.
What truly deserves attention this week is not just whether markets rise or fall, but how politics, interest rates, and financial trust together reshape the direction of global capital allocation.
🧱 Geopolitical tensions: Middle East risks and the U.S. midterm elections converge
① Middle East: Military deployments and diplomatic deadlock coexist
The Middle East situation remains a major source of uncertainty for global energy markets.
Iran says two oil tankers exploded after striking mines near the Strait of Hormuz, while a Pakistani LNG vessel was also attacked.
The news pushed oil prices higher at the open, but they later retreated as markets began reassessing the balance between military risks and diplomatic mediation.
Meanwhile, signs of new diplomatic contacts between the United States and Iran have emerged.
Iran’s foreign minister disclosed what he called a “two-day plan”:
The United States would first fulfill relevant commitments, including unfreezing funds, granting oil waivers, and arranging a ceasefire, after which Iran would reopen the Strait of Hormuz.
Qatar continues to facilitate communication between the two sides, but the United States and Iran have yet to resume direct talks.
② U.S. midterm elections: A contest over policy direction for the next two years
The U.S. midterm elections take place on November 3.
All 435 House seats and around 35 Senate seats are up for election. Any change in control of Congress will directly affect the Trump administration’s room to implement its policies over the next two years.
Early voting has reached or exceeded 50 million. Economic pressures remain one of voters’ biggest concerns, and Texas has set a record for early voting.
📌 Several political variables to watch:
Republican strategy: Trump is focusing on key Senate battlegrounds such as Iowa and Kansas, seeking to retain control of Congress.
White House policy contingency plan: Plans have been drawn up for the possibility that Democrats take control of Congress, with preparations to rely more heavily on executive power to advance the policy agenda.
Michigan race: Divisions have emerged among Democrats, and Haley Stevens has switched her support to Republican candidate Mike Rogers.
Alaska race: Controversy surrounding “Decoy Dan” continues to simmer and could affect the battle for the Senate seat.
The impact of the midterm elections extends beyond domestic U.S. politics. The federal deficit, tariff policy, industrial subsidies, energy policy, and overseas military strategy could all shift as control of Congress changes.
The midterm elections are therefore not just a political vote, but also an important opportunity for global capital to reassess U.S. policy risks.
💹 Capital watch: Three key variables for global markets this week
There is no Federal Reserve rate-setting meeting this week, but U.S. employment and economic data, global central bank policy decisions, and the midterm election results will together shape market expectations for future monetary policy.
① U.S. midterm elections: November 3
All 435 House seats and around 35 Senate seats are up for election.
Key focus: Whether control of Congress changes, and how much room there will be to adjust fiscal, tariff, and industrial policies.
② U.S. October nonfarm payrolls: November 6
Markets expect around 60,000 to 65,000 new jobs, compared with 29,000 added in September. The unemployment rate is expected to remain at 4.2%.
This is the most important U.S. macroeconomic data release of the week.
If employment continues to weaken, markets may raise their expectations for Fed easing;
if employment comes in stronger than expected, it could reinforce expectations that interest rates will remain high.
③ Tech giants’ earnings: Apple and AMD
Apple’s earnings will be watched for the new CEO’s debut, holiday-season guidance, and progress in its AI business.
For AMD, the focus will be on AI chip demand, data center business growth, and forward guidance.
The key question for markets is no longer just the scale of AI investment, but whether massive capital expenditure can translate into actual revenue and profits.
The AI industry is gradually moving from a phase of capital expansion into one where returns on investment are put to the test.
📅 Global financial calendar this week
November 2 | Monday
🇨🇳 China: Caixin Manufacturing PMI (October)
🇺🇸 United States: ISM Manufacturing PMI (October)
Apple earnings (new CEO’s debut; focus on holiday-season guidance and AI progress)
November 3 | Tuesday
🇺🇸 U.S. midterm election day.
jp Japanese markets closed for Culture Day
November 4 | Wednesday
🇨🇳 China: Caixin Services PMI (October)
🇺🇸 United States: ISM Non-Manufacturing/Services PMI (October)
AMD earnings (focus on AI chips and guidance)
November 5 | Thursday
en Bank of England interest rate decision
jp Minutes of the Bank of Japan’s September/October monetary policy meetings
November 6 | Friday
🇺🇸 U.S. October nonfarm payrolls report
jp Bank of Japan Governor Kazuo Ueda speaks at an IMF-related meeting
💸 Web3 overview: Crypto markets enter a credit recovery phase
Over the past 24 hours, crypto markets have entered a period of stabilization and recovery following the shock of the Binance hack.
$BTC and $ETH have staged a modest rebound, but overall market sentiment remains fearful. Total market capitalization has fallen from the start of the week, institutional investors are increasingly cautious, and risk appetite has clearly contracted.
The incident has once again exposed the security risks of centralized exchanges.
However, Binance quickly set in motion asset compensation and operational recovery measures, easing market panic to some extent and preventing a broader systemic run.
Total crypto market capitalization: Around $2.74 trillion. It has stabilized somewhat in the short term, but weekly performance remains weak.
$BTC : Trading between $77.8K and $78.3K, with a slight rebound, but has yet to convincingly reclaim the psychological $80K level.
$ETH: Around $2,280, following BTC’s modest rebound.
$BNB: Around $710, edging up after stabilizing.
📌 Key event: The Binance hack has far-reaching repercussions
The incident took place around October 29–30. The U.S. Federal Bureau of Investigation (FBI) has formally attributed the attack to TraderTraitor, a North Korean state-sponsored hacking group linked to the Lazarus Group.
Impact and response:
Asset losses: According to reports about the incident, around $6.3 billion in crypto assets were involved. The exact accounting of losses and scope of assets remain subject to the final investigation.
Platform response: Binance used company funds, the SAFU Fund, and insurance reserves to cover losses, and pledged that users would not bear them.
Withdrawals resume: The platform is restoring withdrawals in stages, prioritizing services related to BTC, ETH, and major stablecoins.
Fund flows: Net outflows of around $3.6 billion followed the resumption of withdrawals, and markets are still watching subsequent flows.
Market impact: Exchange creditworthiness and custody security are once again in the spotlight.
What makes this incident unusual is that the attackers were not an ordinary cybercrime gang, but a professional hacking group with state backing.
It has prompted the market to recognize anew that the security risks facing centralized exchanges may extend beyond the scope of conventional commercial security defenses.
In the short term, Binance’s asset compensation, resumption of withdrawals, and operational stability should help ease market panic.
But institutional investors will not simply overlook underlying custody and security issues because they were compensated after a single crisis.
📌 Three areas to watch next:
-The subsequent movement of the hackers’ funds, including efforts to trace and freeze the assets.
-Fund flows and user confidence after Binance fully resumes operations.
-External shocks to crypto assets from the U.S. midterm elections, central bank policies, and volatility in AI capital markets.
In the short term, watch whether funds flow back in; over the longer term, watch whether the market is willing to pay the price of trust again.
🧘 Crypto reflections:
Two themes in global markets deserve close attention this week: the U.S. midterm elections and the Binance black swan event.
The former concerns the policy direction of the world’s largest capital market over the next two years,
while the latter exposes weaknesses in the creditworthiness of crypto financial infrastructure.
The two events may appear unrelated, but they point to a shared question:
In an era of growing uncertainty, what is global capital willing to trust, and where is it willing to put its money?
The U.S. midterm elections will not only determine the makeup of Congress, but also influence fiscal policy, trade policy, industrial subsidies, and geopolitical strategy over the next two years.
Nonfarm payrolls will shape how markets adjust short-term interest rate expectations, while the midterm elections could change how investors view the long-term U.S. policy environment.
And the Binance black swan event: Crypto markets are repricing trust
The FBI’s identification of a North Korean hacking group helps the market determine the source of the attack and provides a direction for subsequent tracking efforts.
But the deeper question is this: when attackers have state backing and sophisticated cyber capabilities, can exchanges’ security defenses really provide an effective barrier?
This could shift the balance of power in crypto markets.
Going forward, institutional custody, compliance audits, asset transparency, and cross-platform clearing systems will become increasingly important.
The crypto market remains a “financial island” connected to traditional finance, but not yet fully integrated with it.
That very disconnect points to significant potential for institutional integration in the future.
As institutional capital enters the market, traditional finance’s requirements for custody, security audits, compliance, and transparency will gradually become basic standards for crypto markets.
Global capital flows are forming a new chain of transmission
AI capital expenditure, energy prices, monetary policy, and the crypto credit system are not isolated variables.
We need to clarify how risks are transmitted between different markets, and how capital is reallocated across asset classes, countries, and financial systems.
Three fundamental questions:
👉 How does geopolitics reshape global capital flows?
👉 How does the cost of capital redefine the value of AI and the tech industry?
👉 How does financial trust determine the direction of the next wave of wealth?
⚠️ The above reflects personal views and is for market observation and discussion only.
Geopolitical conditions can change rapidly. Please be mindful of position sizing and leverage risks. This is not investment advice.
📌 LaoYao(@LaoYao_crypto )
Viewing capital through the lens of 心学, and discerning trends through cycles;
Finding certainty amid uncertainty, and anchoring value amid volatility.