

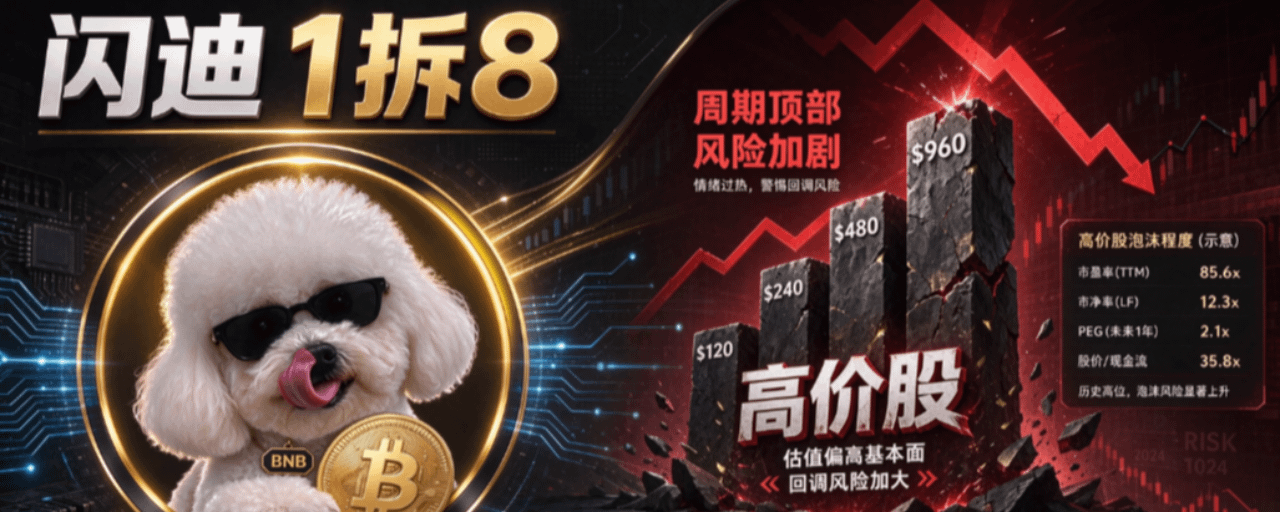

News of SanDisk$SNDK ’s 1-for-8 split is everywhere. Seeing that the “share price will be cheaper,” many investors are drawing direct comparisons with Nvidia and Apple’s post-split performance and preparing to jump in to bet on a price recovery. But history does not simply repeat itself. With today’s high interest rates, marginal shifts in AI capital spending, the memory cycle near its peak, and the many variables surrounding the midterm elections, this split looks more like a risk magnifying glass than a signal to jump in.
I. First, a reminder: What exactly is a 1-for-8 split?
A 1-for-8 stock split turns each share into 8 shares: the share count is multiplied by 8 and the share price is divided by 8. The market value of your holdings, the company’s net assets, its profits, and your ownership percentage remain completely unchanged at the moment of the split. It is not a dividend or a positive earnings catalyst—just a technical adjustment to the share capital, intended to lower the nominal share price, attract smaller investors, and improve liquidity. In a nutshell: a stock split changes the numbers, not the value.
II. A look back at history: Stock splits can have dramatically different outcomes
The market loves to cite Nvidia and Apple, but this is a classic case of survivorship bias:
🚀 Stock splits during a growth-driven upcycle:$NVDA and $AAPL When Alphabet split its stock, demand was surging and results were repeatedly exceeding expectations. The split was merely the icing on the cake; the gains were driven by sustained fundamental performance, not by the split itself.
☕ Stock splits at peak conditions, after expectations are fully priced in: Some high-flying tech stocks and cyclical semiconductor companies have announced splits after major rallies. Retail investors rush in, only for the news to be “priced in” and the stock to underperform after the split. For example, Palo Alto Networks announced a split after a major rally, but its share price continued to weaken afterward. Apple also saw a deep pullback after a split during the dot-com bubble years.
⭐ Takeaway: A stock split amplifies volatility; it doesn’t drive a rally. When fundamentals are improving, it can boost a rise; when a cyclical turning point is near, it can magnify a decline. Cyclical stocks and consumer growth stocks cannot be judged by the same “splits always lead to gains” rule.
III. Four key constraints shaping the current environment (and SNDK’s medium-term trajectory)
Federal Reserve rate environment: High interest rates weigh on AI capital expenditure Memory is a high-beta tech sector and is highly sensitive to Treasury yields. With financing costs high, cloud providers and AI companies may become more cautious about expansion budgets. The foundation of SNDK’s current rally is the scramble for data-center SSDs. If capital expenditure begins to contract at the margin, the memory demand thesis will come under direct pressure.
AI rally: Expectations are fully priced in; the focus is shifting from speculation to order validation AI-related memory optimism has driven share prices higher, with expectations for price increases and AI inference memory demand largely reflected in valuations. The next phase is no longer about “trading on imagination”; investors need to keep tracking NAND contract prices and long-term memory orders from major players. If price increases slow, valuations could be hit hard.
Position in the memory cycle: Currently near a cyclical peak; high gross margins are unsustainable SNDK’s current gross margin of 85%+ is the result of a short-term supply-demand mismatch. Exceptionally high profits will spur Micron, Kioxia, and Samsung to accelerate capacity expansion. As that capacity gradually comes online, NAND prices and gross margins will move back toward the midpoint. That is an iron law of the memory cycle, and a stock split won’t change it.
Midterm election risks: Semiconductor policy uncertainty is adding to volatility The elections will bring debate over chip subsidies, domestic manufacturing, and export controls. The two parties have different approaches to supporting the semiconductor industry, and shifting policy expectations will continue to affect risk appetite for memory and chip stocks, amplifying bouts of volatility. Before the outcome is clear, markets are likely to remain cautious.
IV. Four traps investors must watch out for
The low-price illusion: A lower nominal share price does not mean a cheaper valuation. Only the number is lower; P/E and P/S valuations are unchanged;
The price-recovery myth: Cyclical stocks are more likely to underperform after a split. Don’t use a stock split alone as a reason to buy;
The shareholder-base trap: A split lowers the entry price, drawing in short-term retail traders and increasing intraday volatility and the risk of a sell-off;
The macro blind spot: Focusing only on company-specific news while ignoring the medium-term pressures from interest rates, elections, and the supply cycle.
V. Practical strategies by investor type (matched directly to different trading styles)
Premise: None of the strategies treat a stock split as the primary reason to buy.
Short-term sentiment traders (suited to traders who move in and out quickly) Avoid chasing the price before the split takes effect. If you participate, limit your position to a small size, trade the news-driven momentum window, and set a firm stop-loss in advance. Guard against “buying the rumor and selling the news”: the split record date and effective date are often periods of heavy profit-taking. Don’t treat it as a long-term hold. Also watch for the risk of disrupted liquidity in options contracts after the split.
Swing traders (best suited to cyclical memory stocks like SNDK) Key indicators to track: NAND spot and contract prices, capacity expansion progress at Micron and Kioxia, and capital expenditure guidance from cloud providers.
Signal to add to your position: The supply-demand gap widens again and prices keep rising beyond expectations;
Signals to reduce your position or exit: Price increases lose momentum, manufacturers bring new capacity online, or AI order guidance is lowered;
Approach: Make money from cyclical supply and demand—not from the stock-split theme.
Long-term investors Current levels are not suitable for building a large position. The memory cycle is near a peak, and the risk-reward profile is unattractive. Wait patiently for a cyclical pullback, gross margins to return to a reasonable range, and valuations to normalize before reassessing the durability of long-term AI memory demand.
Risk warning: Diversify across sectors; don’t concentrate your portfolio in memory stocks. U.S. stocks are volatile, so cap the size of any single-stock position and hedge against interest-rate and geopolitical policy risks.#股票财报季
Conclusion
A stock split is neither good nor bad in itself. It simply turns a high share price into a more accessible number, attracting both investors who rationally track the cycle and speculative capital drawn to the lower price. What will always determine SanDisk’s future trajectory is NAND supply and demand, AI capital expenditure, Federal Reserve monetary policy, and changes in industrial policy—not a stock split. Every cyclical boom eventually ends, so don’t let a short-term theme obscure the risk of a cyclical turning point.
Risk disclaimer: This article is for reviewing market information and sharing ideas only; it does not constitute investment advice. U.S. stocks and semiconductor cycles are highly volatile. Make your own decisions and manage risk carefully.