Uncle’s Weekly Report | 10.26–10.30
━━━━━━━━━━━━━━━━━━
I. Markets This Week: Global markets under pressure, with tech assets at the center of the pullback
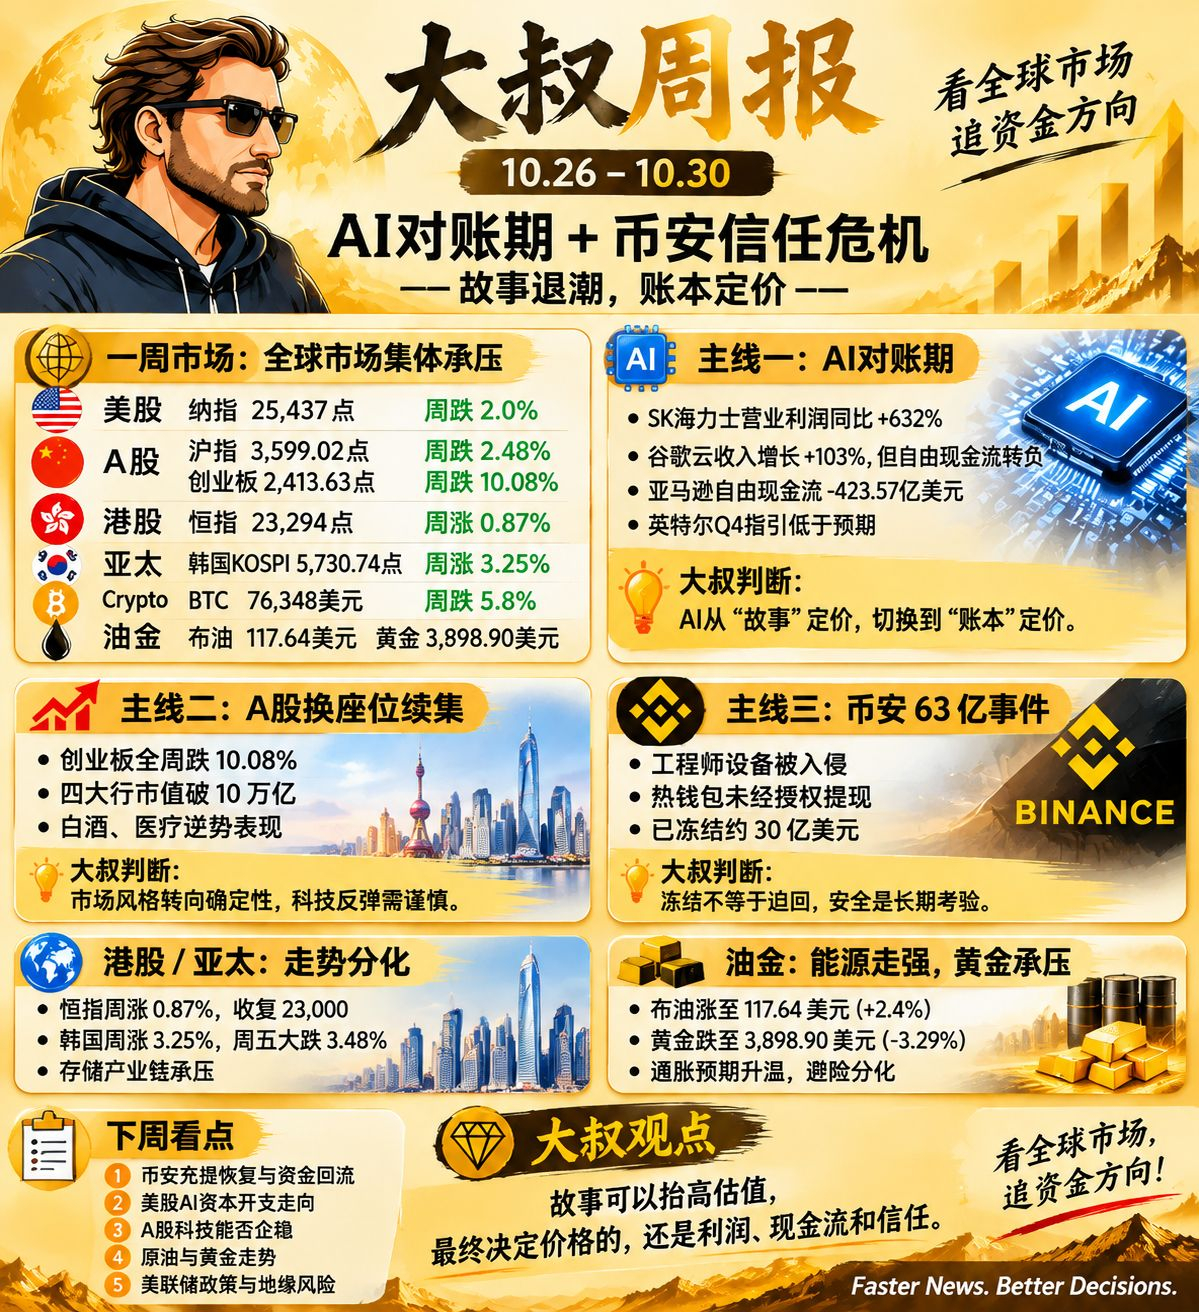
U.S. stocks: The Nasdaq fell about 2.0% this week, including a 2.86% drop on October 30, closing at 25,437. Tech stocks saw a broad pullback as the market began to reassess the payback period for AI investments.
A-shares: The Shanghai Composite closed at 3,599.02, down 2.48% for the week; the Shenzhen Component fell 7.20%; the ChiNext Index fell 10.08%; and the STAR 50 fell 13.73%.
The ChiNext Index is particularly noteworthy: it rebounded about 3.4% midweek, then fell for several consecutive sessions, ending the week down 10.08%. The rebound did not change the weak trend; instead, it highlighted selling pressure on high-beta tech assets.
Hong Kong stocks: The Hang Seng Index closed at 23,294.42, up 0.87% for the week. Compared with the sharp pullback in A-share technology stocks, Hong Kong stocks were relatively stable.
South Korean market: The KOSPI touched an intraday low of 5,599.42 on Friday and ultimately closed at 5,730.74, up about 3.25% for the week. However, it fell 3.48% on Friday alone, with volatility at elevated levels clearly intensifying.
One notable contrast: SK Hynix reported third-quarter revenue of 104.62 trillion won and operating profit of 83.33 trillion won, up 328% and 632% year over year, respectively. Yet even such strong results could not prevent technology stocks from pulling back.
Industry demand and stock valuations are two different things. Strong industry conditions do not mean share prices can keep rising without regard to valuations and expectations.
━━━━━━━━━━━━━━━━━━
II. AI industry: Demand has not disappeared, but the market is now demanding returns on investment
The earnings reports from several technology giants this week showed a common trend: AI investment continues to expand, but the market is paying increasing attention to whether that investment will ultimately translate into profits and cash flow.
1. Amazon: Strong AWS growth, alongside mounting capital expenditure pressure
Amazon’s AWS revenue grew 39.3% year over year in the third quarter, its fastest rate in nearly five years, showing that demand for cloud computing and AI infrastructure remains strong.
On the other hand, Amazon’s free cash flow over the past 12 months was negative $42.357 billion. Behind the rapid growth is continuously expanding capital investment.
The market is no longer asking only how quickly AWS is growing, but when this investment will generate sufficient cash returns.
2. Google: Rapid cloud growth, but pressure remains on the overall balance sheet
Google Cloud’s third-quarter revenue reached $30.7 billion, up 103% year over year, reflecting strong demand for AI-related cloud services.
However, Alphabet’s overall revenue fell short of market expectations, net income declined 25% year over year, and free cash flow turned negative at about $9.1 billion. The share price fell sharply in after-hours trading following the earnings announcement.
The issue is not that the cloud business is failing to grow. Rather, search advertising performance, AI investment, and cash flow pressure have led the market to reassess the quality of overall earnings.
3. Intel: Demand and supply pressures remain unresolved
Intel forecast fourth-quarter revenue of $15 billion to $16 billion, below market expectations. The company also warned that weakness in the PC market could persist through the first half of 2027. Its share price fell about 25% at one point in premarket trading.
This shows that not every company in the AI supply chain benefits at the same time. Growing demand for computing power does not automatically resolve problems such as weakness in traditional businesses, product competitiveness, or supply capacity.
Uncle’s Take:
The AI rally is moving from “storytelling” to “show me the numbers.”
The market has not rejected AI; it is beginning to distinguish between companies that have actually won orders, those with pricing power, and those able to turn revenue into profits and cash flow.
Opportunities in the AI supply chain will remain, but valuation gaps may widen further. Simply having an AI connection is no longer enough.
━━━━━━━━━━━━━━━━━━
III. A-shares: High-beta growth stocks retreat as the market seeks defense and certainty again
The most noticeable change in the A-share market this week was a concentrated correction in technology and growth sectors.
The ChiNext Index fell 10.08% for the week, while the STAR 50 Index fell 13.73%, indicating that high-valuation sectors that had risen sharply earlier are undergoing a concentrated correction.
Meanwhile, low-volatility, high-dividend sectors such as banking held up relatively well. On October 29, the combined market capitalization of China’s four major state-owned banks topped 10 trillion yuan for the first time, with ICBC and China Construction Bank reaching record highs.
This does not mean that capital has fully shifted from technology to banking. But it does suggest that as market risk appetite declines, investors are once again attaching greater importance to certainty and defensive characteristics.
Uncle’s Take:
What matters most to watch in the current A-share market is not whether a particular sector can rebound, but whether technology and growth stocks can truly find a bottom.
Without support from trading volume, stabilization in heavyweight stocks, and sustained recovery within the sector, a one-day rebound is not enough to confirm a trend reversal.
Investors holding high-priced technology stocks at a loss should not rush to add to their positions after a single rebound. For sectors recovering from low levels, it is also important to wait for trend signals rather than judge solely by how cheap prices look.
━━━━━━━━━━━━━━━━━━
IV. Crypto: Binance hot wallet attacked, putting exchange security to the test again
The most closely watched event in crypto this week was the security incident disclosed by Binance.
According to Binance’s announcement, at around 04:05 on October 30, attackers gained access to service containers by compromising the devices of relevant engineers, among other methods. They then submitted unauthorized withdrawal transactions, resulting in an estimated $6.3 billion in hot wallet asset losses.
Binance said it had found no evidence that wallet private keys were leaked. Around $3 billion worth of related assets have been frozen on-chain, and efforts to trace and handle the remaining assets are ongoing.
Binance pledged more than $6.34 billion to cover the losses and said that assets worth more than $5 billion had already been secured. The platform temporarily suspended withdrawals after the incident; withdrawals could resume only after security checks were completed.
Two concepts must be distinguished here: freezing assets is not the same as recovering them, and a commitment to make up the shortfall does not mean all losses have already been recovered.
What this incident truly affects is not just the security of a single platform’s assets, but users’ trust in centralized exchanges.
Uncle’s Take:
The crypto market has long emphasized decentralization, but the vast majority of ordinary users still rely on centralized exchanges to trade and manage their assets.
An exchange’s core competitiveness is not just its liquidity, fees, and range of products, but also its security and ability to manage risk.
A security incident tests the technical system; whether the platform can disclose information transparently, compensate users promptly, and restore services tests its credibility.
━━━━━━━━━━━━━━━━━━
V. Hong Kong stocks, Asia-Pacific and commodities: Even safe-haven assets saw sharp swings
Hong Kong stocks and Asia-Pacific: The Hang Seng Index rose 0.87% for the week, while South Korea’s KOSPI gained about 3.25%, though the Korean market pulled back noticeably on Friday. Asia-Pacific markets did not rise in unison; volatility at elevated levels and pressure on technology stock valuations remain.
Crude oil: The December Brent crude futures contract settled at $117.64 per barrel, up 2.4% on the day. Oil prices remaining elevated mean that energy costs and inflationary pressures are still factors global markets cannot ignore.
Gold: The COMEX gold front-month contract settled at $3,898.90 per ounce, down 3.29% on the day and marking its lowest settlement level in nearly a year. Concerns about tighter monetary policy, changes in demand, and potential forced selling all contributed to increased volatility in gold.
The sharp swings in both gold and crude oil show that the market is not simply following a pattern of safe-haven assets rising. Interest-rate expectations, inflation, liquidity, and changes in positioning can all affect asset prices.
━━━━━━━━━━━━━━━━━━
VI. The Federal Reserve: A 10–2 vote signals policy disagreement
This week, the Federal Reserve kept its federal funds target range at 3.75%–4.00%, with a 10–2 vote.
Two policymakers favored a 25-basis-point rate hike, reflecting differing views within the decision-making body on inflation and the policy path.
Markets should look beyond whether rates are cut and also watch for changes in the Fed’s assessment of inflation, employment, and financial conditions.
With energy prices elevated and inflationary pressures still present, expectations of monetary easing remain fragile. Changes in interest-rate expectations will also continue to affect technology stock valuations and gold prices.
━━━━━━━━━━━━━━━━━━
VII. What to watch next week: The market needs new signals for confirmation
AI earnings and capital expenditure: Continue to watch whether cloud business growth translates into profits and cash flow, and whether clearer evidence emerges of returns on AI investment.
A-share technology sector: Focus on whether the ChiNext and STAR 50 indices can stabilize, whether trading volume improves, and whether heavyweight stocks can find a footing.
Fed policy expectations: Changes in inflation, employment, and energy prices may continue to influence interest-rate expectations.
Binance security incident: Watch the progress of resumed withdrawals, whether asset reimbursement is fulfilled, and the subsequent technical investigation report.
Crude oil and gold: Watch whether high oil prices further intensify inflationary pressures, and whether gold can stabilize after its sharp pullback.
━━━━━━━━━━━━━━━━━━
Uncle’s Take
The most important change in global markets this week was not how much a particular index fell, nor how impressive a company’s earnings report was.
Rather, markets have begun to reassess the real value behind assets.
AI demand remains strong, but capital expenditure must translate into profits. Industry earnings remain robust, but stock valuations cannot keep rising on distant expectations alone. Trading platforms still have vast user bases, but their security and credibility must stand up to real-world tests.
Stories can drive valuations higher, but ultimately, prices are determined by profits, cash flow, and trust.
When markets start checking the books, genuine opportunities will gradually emerge from the concepts.