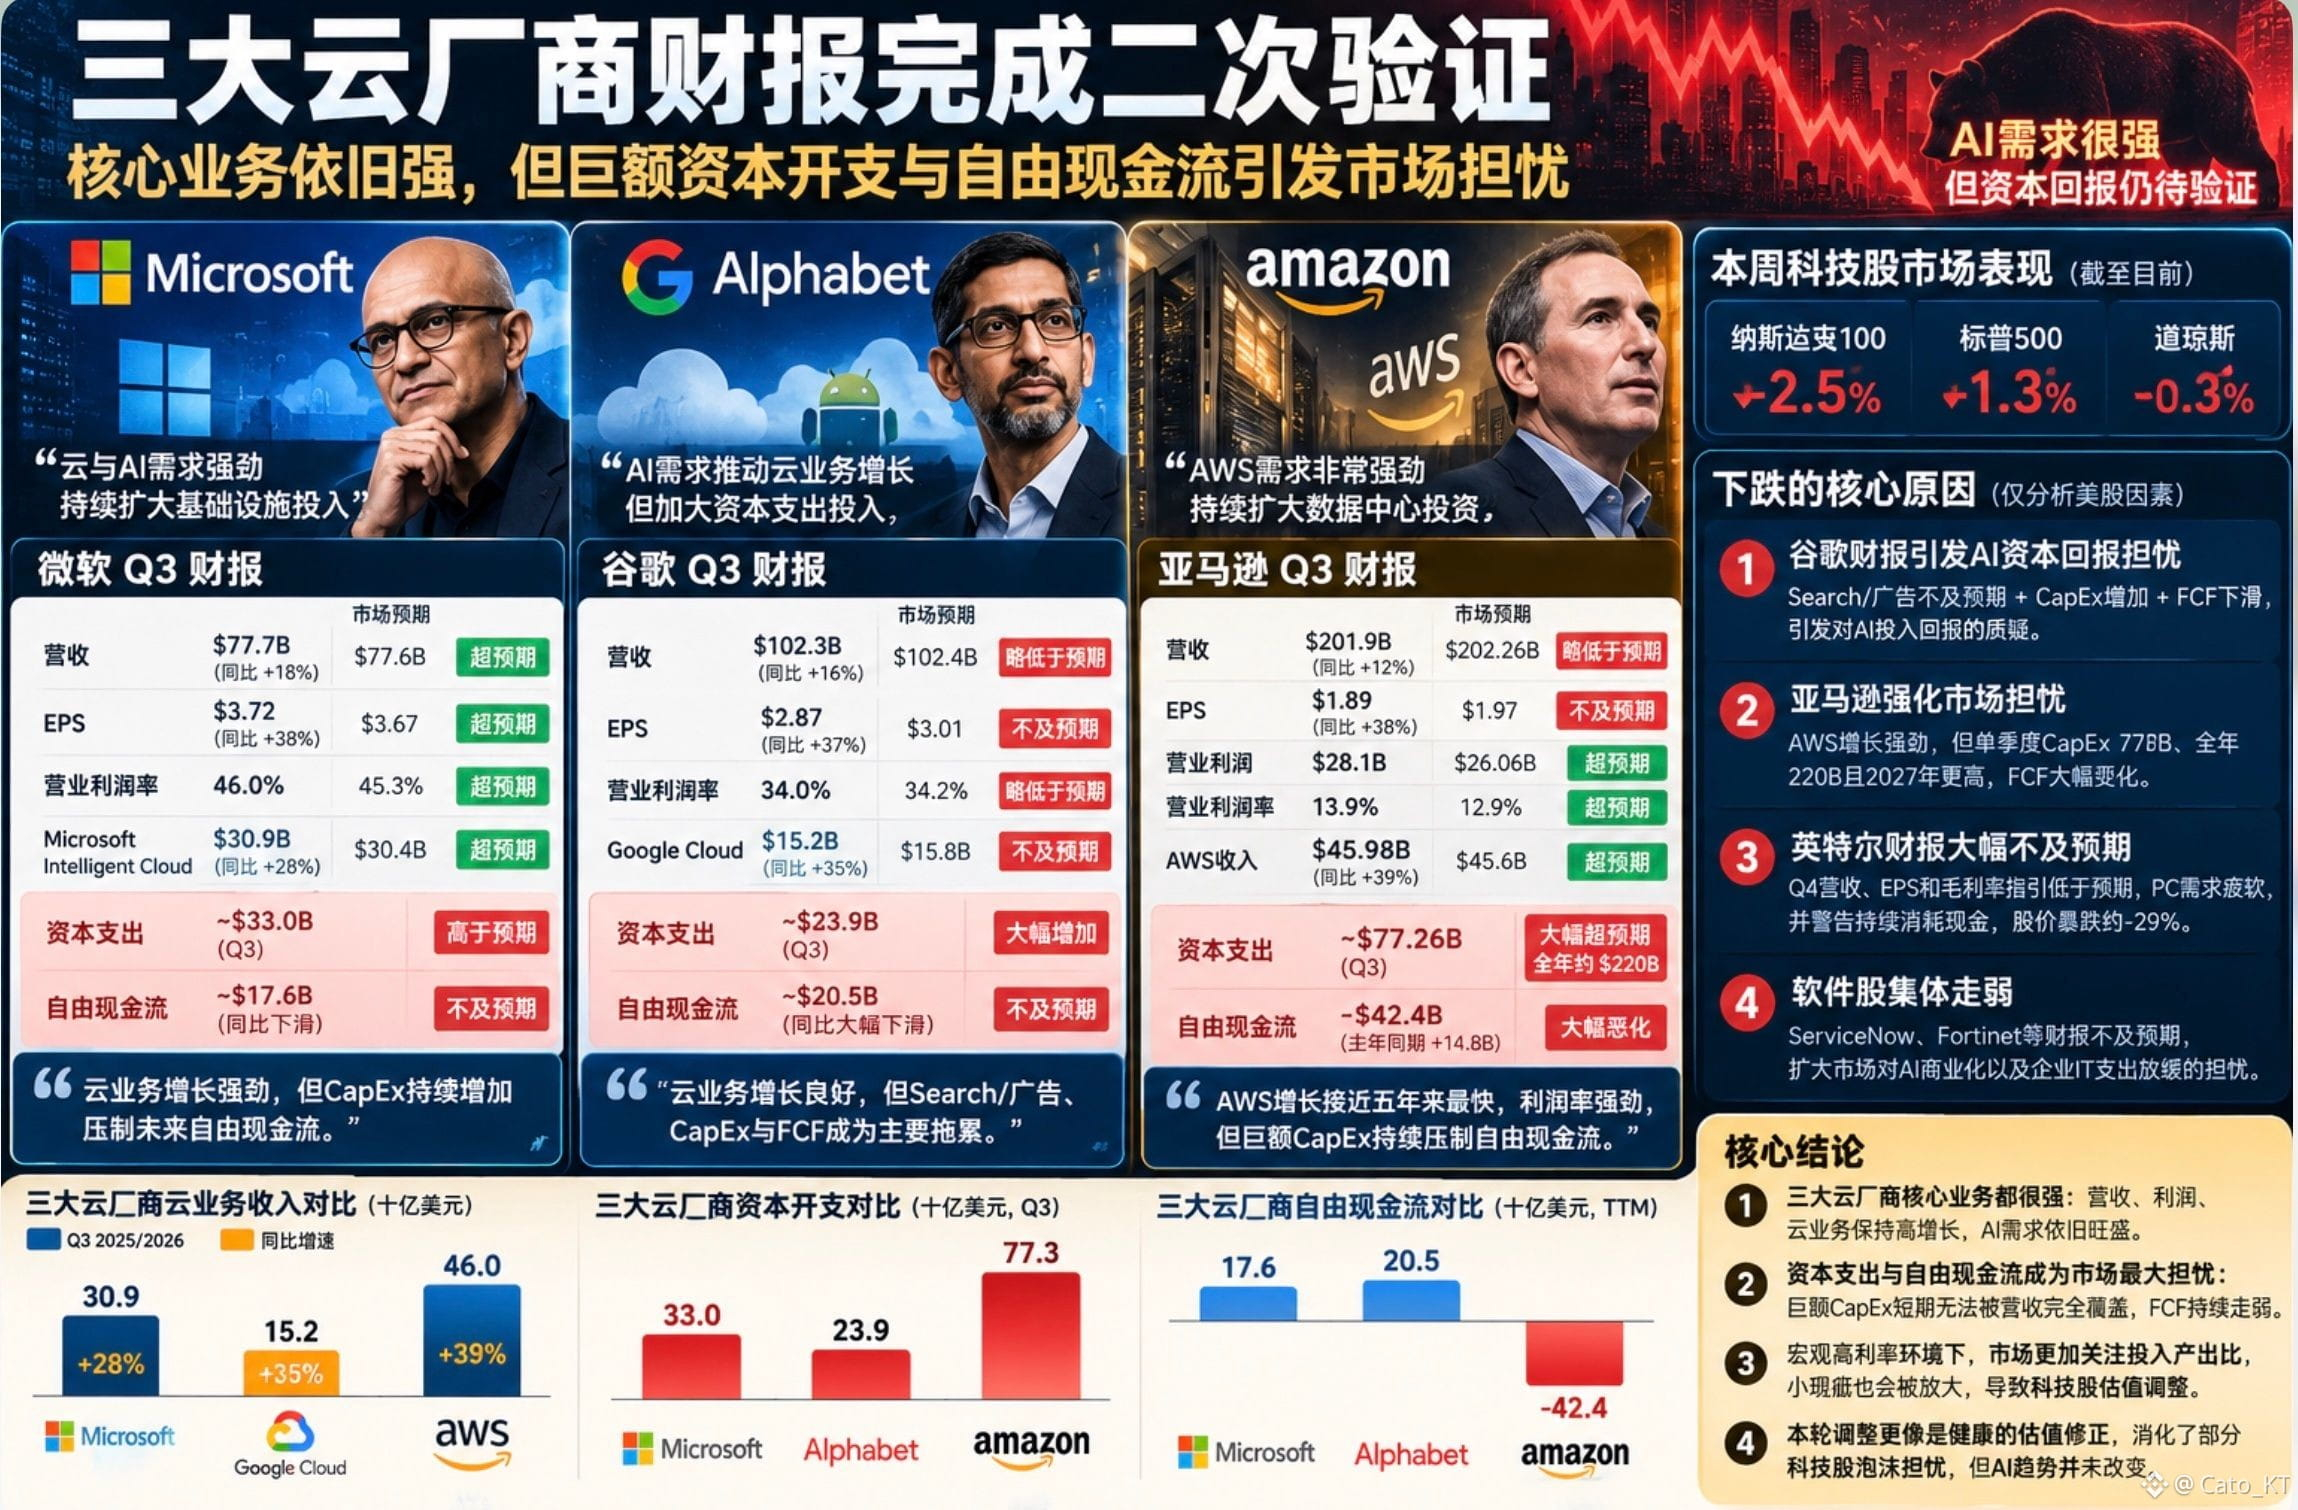
What’s behind Intel’s 29% stock plunge? Where exactly does the trouble lie?
Here’s a quick rundown of the earnings report released early this morning $INTC . In short, Q3 results were good, but Q4 revenue guidance, profitability, and the PC business were all revised down significantly.
In an era when everyone is racing to deliver explosive growth, it might be acceptable not to hit it out of the park—but a major cut to guidance is bound to disappoint the market at the current valuation. Still, that’s only one of the main factors.
Meanwhile, Intel’s core PC business suddenly weakened, while demand for AI and data centers surged. But supply-chain and capacity bottlenecks have kept Intel from fully converting that demand into revenue.
Add to that an incident at its Israeli factory, memory price guarantees, and the cash burn from expanding capacity, and the result is a sharp downward revision to Q4 revenue, margins, and EPS guidance.
In short, Intel’s existing core business has been hurt by external factors, while it has yet to benefit from the red-hot AI trend. This has directly triggered a major valuation reset.
Of course, Q4 is a critical quarter for Intel. After the steep valuation adjustment, will the business continue to deteriorate? Can the company quickly break out of its predicament and return to the mainstream trend in the AI era? These will be the key things the market watches going forward!#