Cloud revenue grew at its fastest pace in three years, yet the stock still got hammered by 10%. I’m having a hard time understanding it, though I kind of get it.
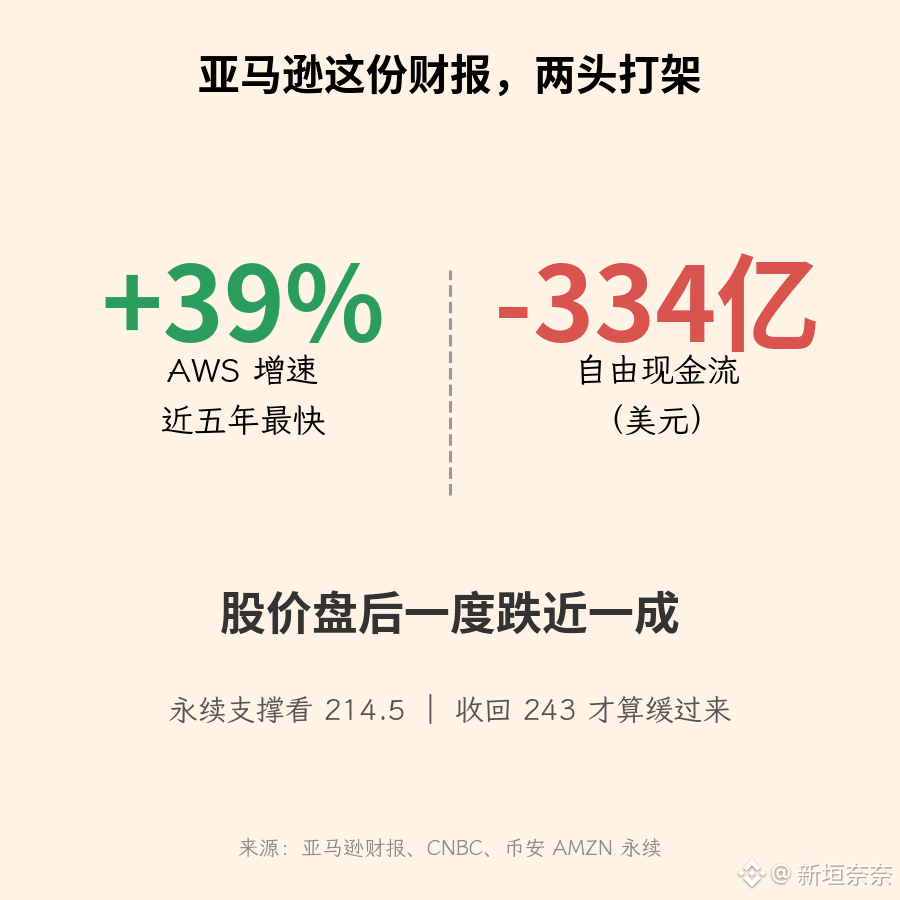
Amazon reported earnings last night. AWS grew 39%, its fastest pace in nearly five years, but both revenue and earnings per share came in slightly below expectations. Free cash flow plunged to negative $33.4 billion, and the company hasn’t budged on its $220 billion in AI spending this year. The market’s message is clear: I see the growth, but I’m not buying it when you’re burning through cash this fast.
The perpetual contract is now at 227, after dipping as low as 214.5 last night. I’d view this area as the first line of support. It won’t have really recovered until it gets back to 243 (the closing price before earnings); until then, I’ll treat any move up as a bounce.
Do you think the AI-spending story has run out of steam, or has this sell-off created an opportunity?
Just my personal opinion, not financial advice.
#亚马逊 #美股财报 #美股 $AMZN $NVDA