

Recently, I started focusing on a U.S. stock:
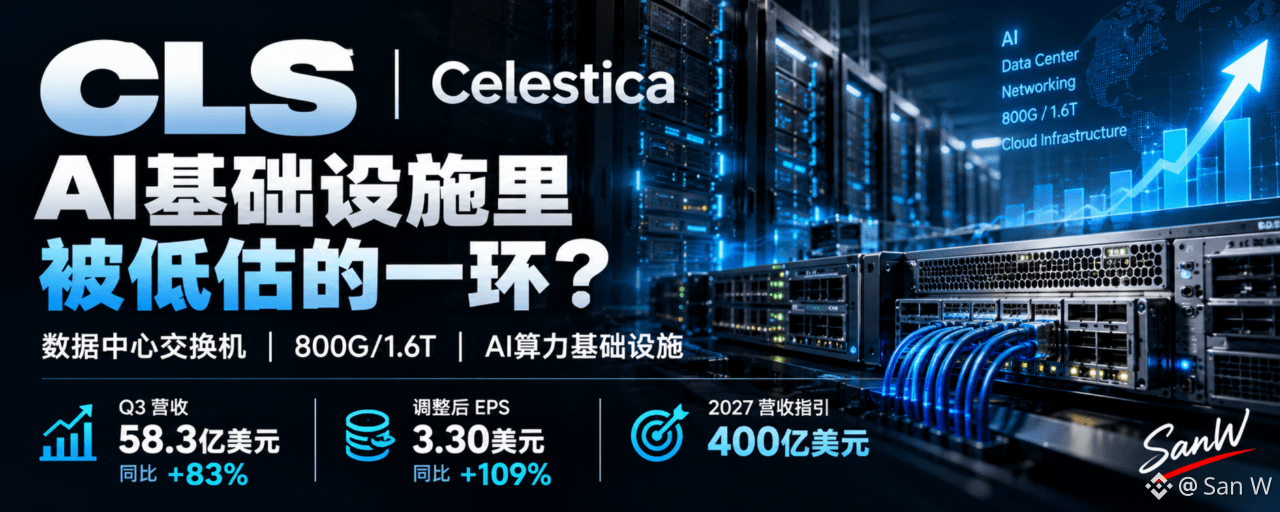
$CLS|Celestica
When many people mention AI infrastructure, their first reaction is:
NVDA, AVGO, data centers, power.
But in fact, there is another very important step that is often overlooked:
High-speed networking equipment + data center hardware platforms.
And $CLS is standing right at this spot.
The latest Q3 2026 earnings report was extremely impressive:
Revenue of $5.83 billion, up 83% year over year
Adjusted EPS of $3.30, up 109% year over year
Adjusted operating margin of 8.5%, another record high.
More importantly,
The company directly set its 2027 revenue target at:
$40 billion, up 90% year over year
Adjusted EPS is expected to be $21.50.
And management explicitly stated that,
the 2028 customer demand forecast,
is still clearly higher than the 2027 revenue guidance.
This shows that what the market is trading on now
is no longer just this year’s performance,
but rather:
how long AI data center infrastructure demand can continue.
Celestica’s core logic, I’m mainly watching three things now:
1. Continued capex growth from hyperscalers
Microsoft, Google, Meta, and Amazon continue to expand AI data centers,
and servers, switches, and networking hardware all need to grow in sync.
2. 800G / 1.6T network upgrades
As AI cluster sizes keep getting larger,
the demand for data transfer between GPUs keeps increasing.
The network is starting to shift from “supporting equipment,”
into one of the core bottlenecks of AI infrastructure.
3. The hardware platform business is scaling rapidly
Celestica’s Hardware Platform Solutions Q3 revenue was about $2.3 billion, up 70% year over year.
This is no longer the logic of traditional EMS manufacturing.
But the risks are also very clear.
The biggest risk for a company like this is not “no growth,”
but rather:
growth expectations are too high.
When the market has already started pricing in hyper-growth in 2027 and 2028,
as long as some future quarter comes in below expectations,
valuation compression can happen very quickly.
So when I look at $CLS now,
I don’t see it as a second NVDA,
but rather as:
a company in the AI infrastructure supercycle that sells “the shovel next to the shovel.”
The bigger the data center,
the more servers there are,
the more complex the GPU clusters become,
the more important the network and hardware platform become.
What really needs to be tracked now is not the daily rise and fall of the stock price,
but rather:
whether the $40 billion 2027 revenue target can be achieved.
If it can,
then the revaluation of $CLS may not be over yet.
If it can’t,
then today’s very high market expectations will also become a source of pressure.
A good company still ultimately has to be validated by results.
$CLS⛰️
Not investment or trading advice.