Net profit missed by 35%, yet SK Hynix rose 11%
Here's the bottom line: I'm on the cautious side, and I'm not chasing this 11% move.
SK Hynix just reported a Q3 that was explosive, yet somehow awkward.
Revenue came in at 104.62 trillion won, topping 100 trillion won for the first time ever, up 328% year over year.
Operating profit was 83.33 trillion won, up a whopping 632% year over year. Gross margin hit 79.7%, versus market expectations of just 76.96 trillion won for operating profit—a beat of 8.3%.
But net profit was 39.78 trillion won, against market expectations of 61.29 trillion won—a 35.1% miss.
SK Hynix shares closed at 1,487,000 won in South Korea, up 146,000 won or 10.89%, and moved back above 1.4 million won for the first time in ten trading days.
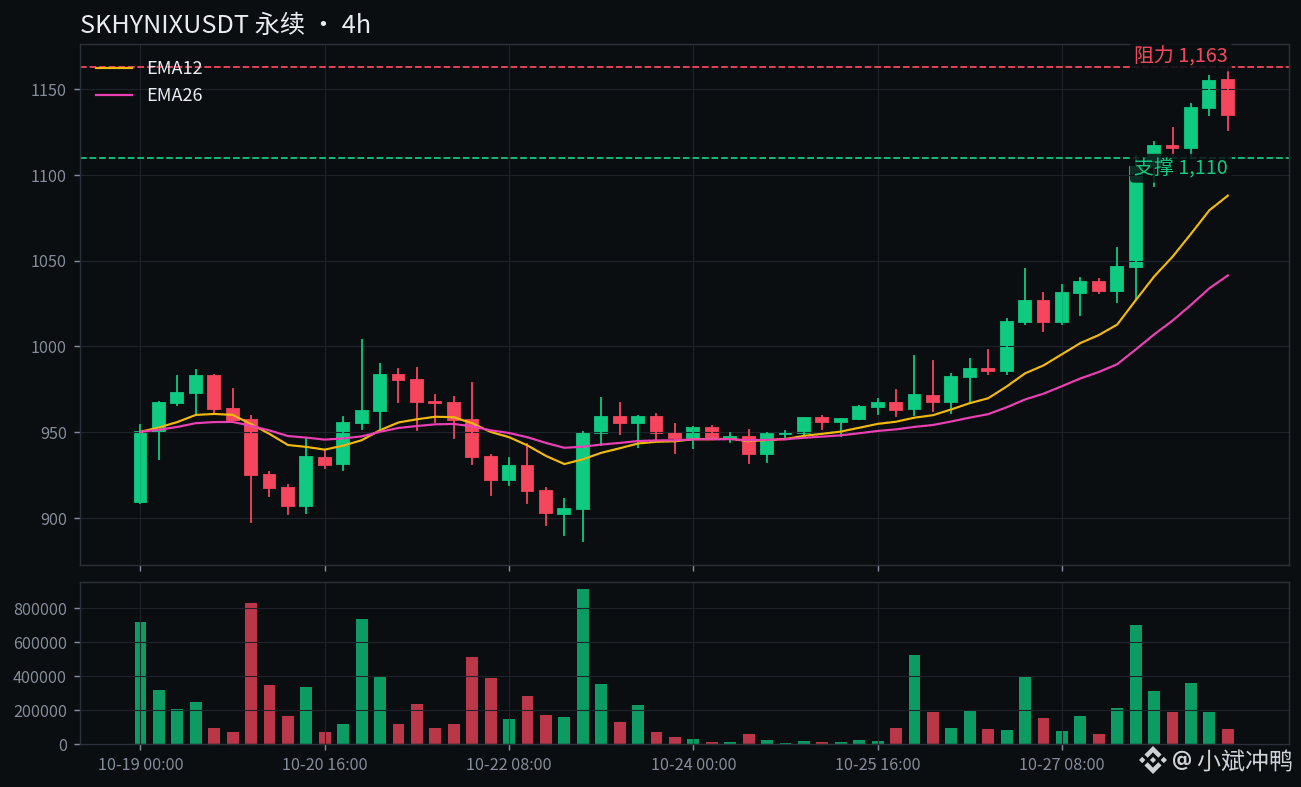
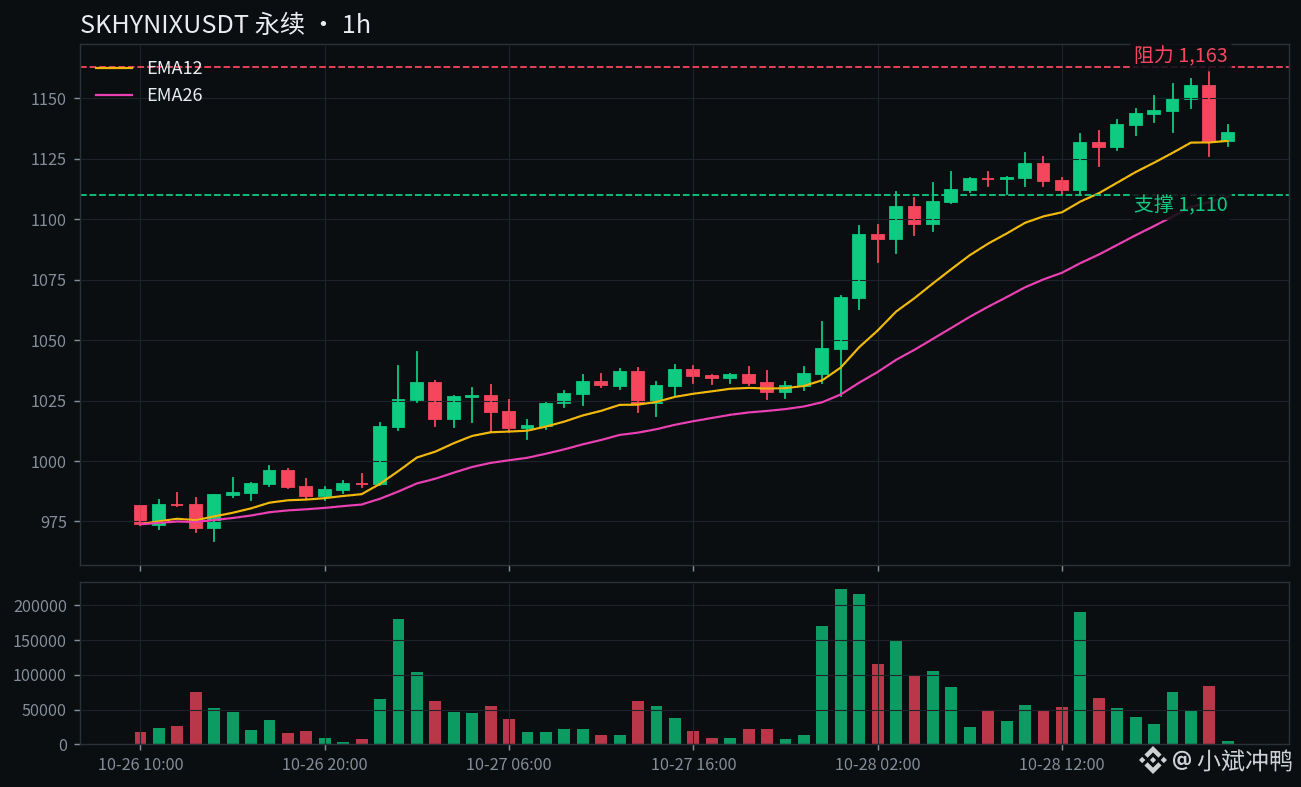
The Binance perpetual contract SKHYNIXUSDT is currently at 1134.85, up 10.40% over 24 hours, with a high of 1162.74 and a low of 1026.18. Contract volume is $2.241 billion and the funding rate is -0.0424%—there's basically no sign of overheated sentiment.
The bulls have a genuinely strong case.
The company itself says the memory shortage will last through 2030. It has expanded its long-term agreement customers from 10 to 14, and more than half of its capacity for 2027 and 2028 is already locked in under long-term agreements.
On top of that, its 2026 shareholder return plan totals 100 trillion won, combining buybacks and dividends. Cash has risen from 27.85 trillion won a year ago to 114.46 trillion won, while debt has fallen from 24 trillion won to 15.8 trillion won.
In plain terms, this isn't just pie in the sky: the company has the goods and the cash to back it up.
The bears have a point, too.
That 35% net profit miss is right there, and profit was also down 58% quarter over quarter. Even allowing for investment gains that lifted the comparison base in Q2, the figure is still hard to stomach.
A 79.7% gross margin is bound to invite questions. How long can it hold up as capacity expands and prices ease? No one can guarantee it.
The position is even more troubling: South Korean shares are still down 15.75% over the past month. The 52-week high is 2,987,000 won, and the current price is still half that. This 11% move looks more like an oversold bounce than the start of a new major rally.
I think the bulls are talking about fundamentals, while the bears are focused on positioning and durability—and neither side is wrong.
But I trust the bears' side of the argument more, because today's gain has already priced in the part of the earnings report that beat expectations.
The peak-out concerns that weighed on the stock ahead of earnings have eased, but they haven't disappeared. The further we go with a gross margin near 80%, the more aggressively the market will question whether it's sustainable.
The scenarios are simple.
If the stock holds above 1162.74, the 24-hour high, then a second leg up is really underway, with 1200 as the next round-number target.
If it breaks below 1110, the intraday pullback area, that means the buyers who chased the move are heading for the exits. It wouldn't be surprising to see it stall and fall back to the 24-hour low of 1026.18.
I'm staying on the sidelines for now. I won't reach in unless it holds above 1163.
If it breaks below 1110, I'll take that as confirmation this was an oversold bounce and won't stick around for the ride.
Will it hold above 1163 and launch a second run toward 1200, or break below 1110 and stall on the way back to 1026?
I'm betting on the latter. What about you?
$SKHY $KORU $SOXL
#半导体 #USStocks