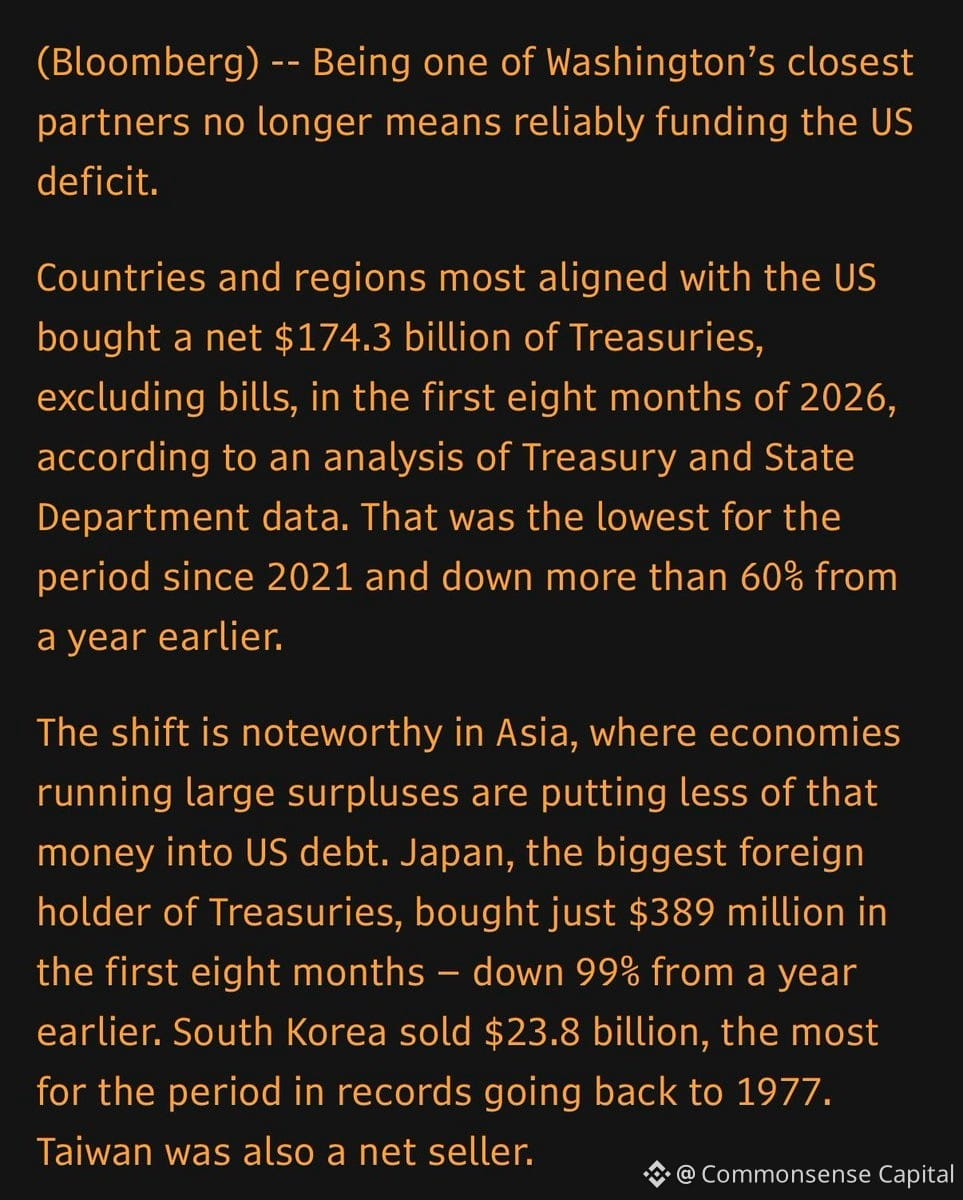
Interesting shift happening in Treasury markets that doesn't get enough attention:
Historically reliable foreign buyers — especially US-friendly nations in Asia — have cut their Treasury purchases by 60%. These were the patient, long-term holders who provided stable demand for decades.
Now? The buyer base is increasingly tactical traders and short-term investors. That's a structural change, not just a blip.
Why it matters: When your bond market depends more on hot money than sticky capital, you get more volatility, higher term premiums, and less predictable funding costs. It's like replacing your mortgage with a credit card — works until it doesn't.
This isn't about doom. It's about recognizing that the US can't assume infinite demand for its debt at rock-bottom rates anymore. Local fiscal needs abroad + diversification away from dollar concentration = less autopilot buying.
Markets adapt. Yields adjust. Life goes on. But if you're wondering why long-term rates stay stubbornly high even when the Fed cuts, this is part of the answer.